
Pelacarsen Trial Failure Might Change The Case For Investing In Ionis Stock (IONS)
- Novartis reported that pelacarsen, co developed with Ionis Pharmaceuticals to lower lipoprotein(a), reduced Lp(a) levels in a large Phase 3 trial but did not cut heart attacks, strokes, or related cardiovascular events. This raises questions about how Lp(a) lowering translates into clinical benefit.
- The pelacarsen setback removes a potential cardiovascular revenue pillar for Ionis Pharmaceuticals and places more pressure on its remaining late stage RNA medicines to support the commercial transition already under way.
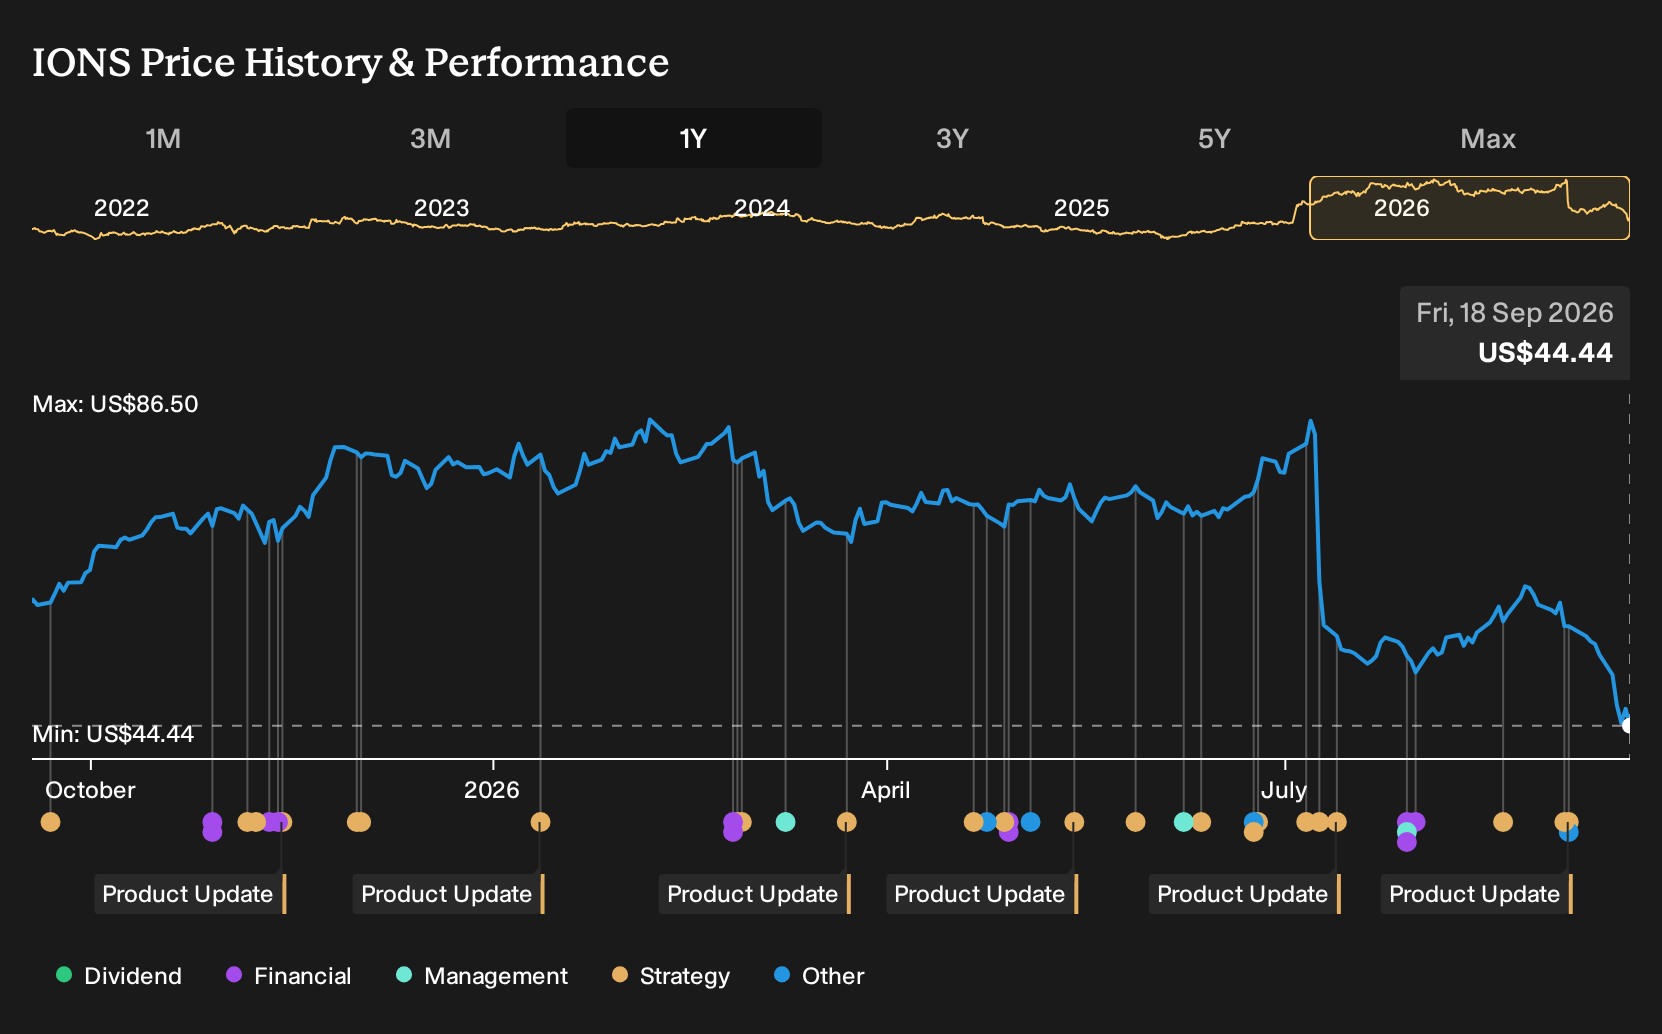
- The following review considers how Ionis Pharmaceuticals' investment narrative could shift after pelacarsen's failure to reduce cardiovascular events.
Ionis Pharmaceuticals Investment Narrative Recap
For Ionis Pharmaceuticals to make sense in a portfolio, you need to believe the core of the story has shifted from one big cardiovascular swing to a broader RNA medicines platform. Pelacarsen weakens one potential revenue stream but does not touch the recently launched products in rare disease and hereditary angioedema, which remain the practical focus for near term execution.
The biggest near term catalyst still sits in how efficiently Ionis ramps Tryngolza and DAWNZERA, and prepares Olezarsen and other late stage drugs for potential approvals. The main risk now is concentration in a smaller set of high stakes filings and launches, where any regulatory delay or pricing pushback could quickly pressure revenue and margins.
The most relevant recent development is the Lp(a)HORIZON update in September 2026, where pelacarsen lowered lipoprotein(a) but did not reduce heart attacks, strokes, or related cardiovascular events. That result affects Ionis Pharmaceuticals at the partnership and royalty level rather than disrupting its existing commercial products.
For catalysts, the pelacarsen outcome effectively increases the importance of Donidalorsen and Olezarsen in severe hypertriglyceridemia, as well as other late stage studies that are expected to read out by 2027. Execution risk rises because fewer programs now carry more weight. Investor attention is likely to stay focused on trial quality, labeling discussions, and payer responses around those assets.
Ionis Pharmaceuticals' current analyst narrative points to US$2.3b in revenue and US$222.2m in earnings by 2029, built on an assumed 37.1% yearly top line growth rate and a swing in earnings of roughly US$787m from the present loss of US$565.2m.
Discover why Ionis Pharmaceuticals' fair value suggests a 98% potential upside to its current price before the gap begins to close.
Exploring Other Perspectives
For a contrasting angle, consider the risk that Ionis Pharmaceuticals remains loss making for a longer period. The most cautious analysts were only modeling about 21.9% annual revenue growth to roughly US$1.6b by 2029 and still saw earnings potentially falling as low as US$763.9m. This pelacarsen result could increase the divergence in those views, so it may be helpful to explore several viewpoints before deciding what makes sense for you.
Explore 3 other Ionis Pharmaceuticals fair value estimates, including one that suggests it could be worth just $60.82!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Ionis Pharmaceuticals research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for Ionis Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Ionis Pharmaceuticals' overall financial health at a glance.
Looking For More Ideas Beyond Ionis Pharmaceuticals?
If the pelacarsen outcome has you reassessing where Ionis Pharmaceuticals fits in your portfolio, it can help to line it up against other options side by side. The Simply Wall St Screener lets you filter for the traits you care about most so you can build a broader watchlist with a clear purpose.
- Prioritise financial resilience and balance sheet strength by reviewing a curated list of solid balance sheet and fundamentals (23 results) that may handle stress better than more leveraged peers.
- If income is your main focus, scan through a group of higher yielding stocks with 6 dividend fortresses and see which ones might complement a growth heavy portfolio.
- For investors hunting for mispriced opportunities, widen the funnel with a focused set of potential 16 high quality undiscovered gems that have strong fundamentals but limited current attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com