
Kobe Steel (TSE:5406) Could Be Trading At A 51% Premium Following Malta Alliance
Malta Inc. has entered a capital and business alliance with Kobe Steel (TSE:5406), which invested in the energy technology firm to link its compression expertise with Malta’s ultra high temperature heat pump systems for industrial decarbonization.
Kobe Steel’s recent move into high temperature heat pump technology comes as the share price has gained 4.02% over the past month and 5.24% across 90 days, while long term momentum remains stronger, with a 1 year total shareholder return of 19.44% and a very large 5 year total shareholder return of 286.98%.
Scan other industrial transition opportunities moving on similar themes as Kobe Steel by reviewing the hand picked list of solid balance sheet and fundamentals (20 results) aligned with decarbonization and heavy engineering.
Kobe Steel trades slightly above the average analyst target and at a steep discount to one intrinsic value estimate. Is the market simply cautious, or is that gap pointing to mispricing as this alliance takes shape?
Preferred P/E of 12.1x: Is it justified for Kobe Steel?
Kobe Steel changes hands at a P/E of 12.1x, which places the current ¥2,069 share price slightly below the broader JP market multiple and broadly in line with similar sized peers.
The P/E ratio compares what investors pay for each unit of earnings. For a diversified materials and machinery group like Kobe Steel, this gauge often reflects how much confidence the market has in future profits from steel, compressors, power and related activities.
On one side, the stock is described as expensive against the JP Metals and Mining industry on a P/E basis, since 12.1x sits above the sector average of 10.8x. On the other side, it is described as good value versus direct peers at 12.8x and against an estimated fair P/E of 16.1x. This is a level the market could feasibly move toward if earnings forecasts and balance sheet risks are assessed more positively.
Explore the SWS fair ratio for Kobe Steel.
Result: Price-to-earnings of 12.1x (ABOUT RIGHT)
Still, the story around Kobe Steel can unravel if earnings in key segments like Steel & Aluminum weaken, or if the recent pullback in year to date returns deepens.
Find out about the key risks to this Kobe Steel narrative.
Another View on Kobe Steel’s value
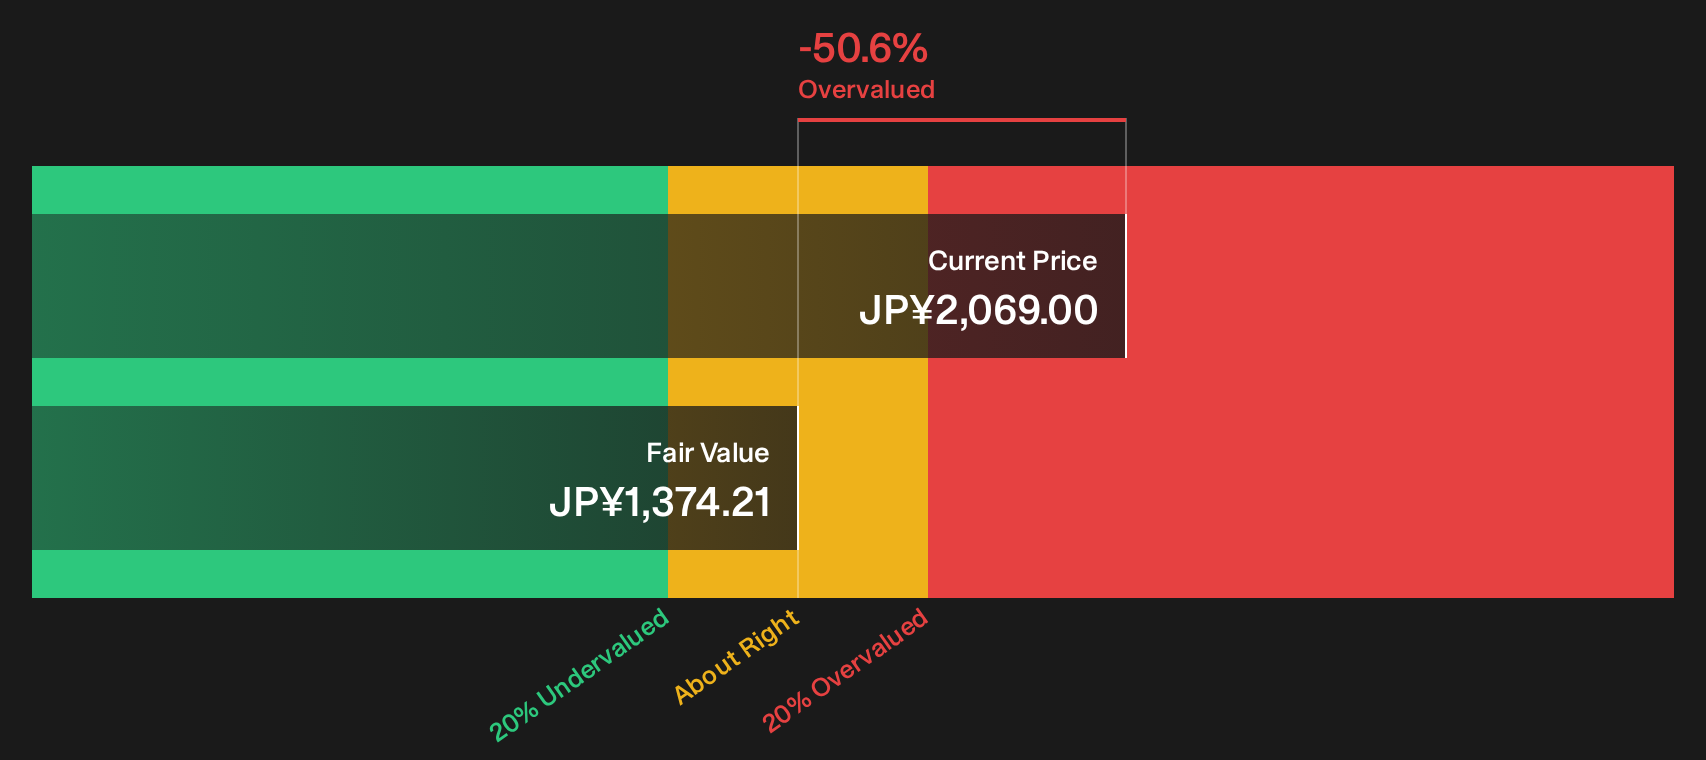
The SWS DCF model paints a very different picture for Kobe Steel. On that approach, the current ¥2,069 price sits well above an estimated future cash flow value of ¥1,374.21. This frames the stock as overvalued on this metric and raises questions about how dependable those cash flows really are.
Our DCF model relies on assumptions about future earnings, margins and reinvestment that may prove too cautious or too optimistic. If market expectations on decarbonization projects or power operations shift, this valuation anchor can move quickly. The key question is which earnings path investors should trust most.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Kobe Steel for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Kobe Steel’s valuation and new alliances can pull you in both directions. Move quickly, test the core numbers yourself, and weigh the balance of 2 key rewards and 3 important warning signs
Looking for more Kobe Steel sized ideas?
If Kobe Steel has sharpened your focus on valuation and execution, do not stop here. Broaden your watchlist now and avoid missing the next opportunity.
- Target resilient compounding potential by scanning a 17 high quality undervalued stocks that combine quality fundamentals with prices that may not fully reflect them.
- Strengthen your income stream by reviewing 14 dividend fortresses that pair higher yields with businesses built to support regular payouts.
- Prioritise capital protection first by tracking 21 resilient stocks with low risk scores where balance sheets and risk scores aim to keep surprises in check.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com