
3 Great Dividend Stocks To Own In September 2026
When interest rates climb and borrowing gets more expensive, dependable cash payouts suddenly matter a lot more. The latest move by the Federal Reserve to lift its benchmark rate to 3.75% to 4% pushes income seekers to look beyond savings accounts and short term fixes. This article breaks down three companies with yields above 3%, where the dividend appears better covered, more consistent, and positioned for long-term stability.
The three stocks covered below are just a sample from this approach, while the full screen surfaces another 2,275 companies with dividend yields above 3% and equally compelling income stories that are not covered here. If you want to quickly identify and analyze candidates that match your own income targets, head straight into the Dividend Powerhouses (3%+ Yield) screener.
Chevron (CVX)
Chevron is a classic integrated energy giant, using its upstream oil and gas production and downstream refining operations to generate the cash that funds its dividend, with most revenue coming from Downstream in the United States at about US$82.5b and internationally at roughly US$78.8b, plus more than US$107.7b from Upstream activities, and a market value near US$415b.
Chemicals, fuel marketing, and crude production all feed into Chevron’s income engine, but it is the scale of those upstream and downstream cash flows that really matters for investors hunting durable dividend income.
"Chevron agreed updated joint venture terms in Venezuela and outlined plans to invest over US$7b across five years, aiming to more than double production in the country from roughly 280,000 barrels per day to about 600,000 barrels per day."
What happens if a single cost or policy shift changes how much of that extra output drops to the bottom line?
When a policy tweak can reshape that cash flow, the full narrative for Chevron shows how Chevron’s Venezuela exposure, capital plans, and dividend potential could be quietly decoupling from headline oil moves.

Accenture (ACN)
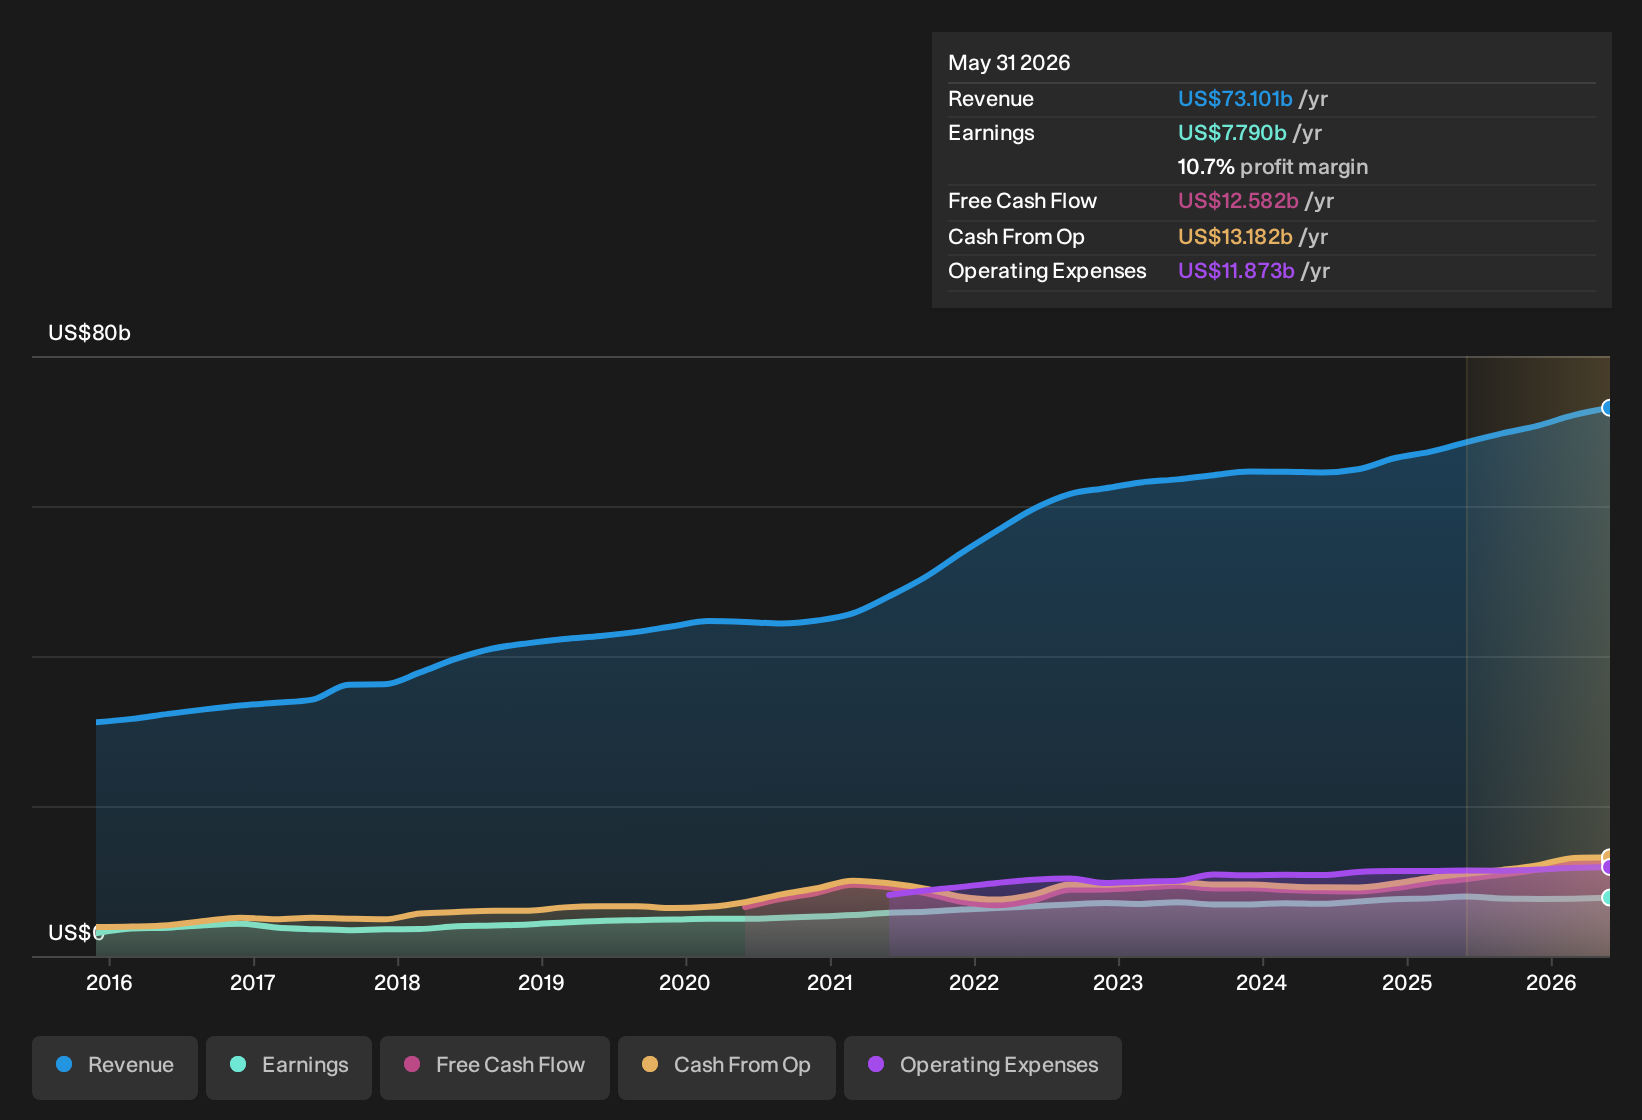
Accenture plugs into this dividend screen through a consulting and outsourcing engine that throws off steady cash, with its Technology and Operations work helping fund a 3%+ yield and giving income investors exposure to AI, cloud and long-term managed services.
Accenture earns roughly US$22.3b from Products clients, US$14.9b from Health and Public Service, US$13.8b from Financial Services, US$12.4b from Communications, Media and Technology, and US$9.8b from Resources, and the stock carries a market value near US$116.4b.
"AI could reduce billable labor needs and compress parts of Accenture’s traditional consulting and delivery model."
What happens to dividend headroom if one quiet shift in how clients buy long-term outsourcing work reshapes that cash engine?
That quiet shift is exactly where the full narrative for Accenture breaks down how Accenture’s AI risk could mask a fresh cycle of higher quality, recurring cash flows.
Novo Nordisk (CPSE:NOVO B)
Novo Nordisk is a global pharmaceutical group focused on diabetes, obesity and rare diseases, with its dividend firepower tied closely to cash from GLP-1 therapies and insulin. Diabetes and Obesity Care contribute about DKK 309b in revenue versus roughly DKK 20b from Rare Disease, and the stock is valued near DKK 1,245.3b.
Novo Nordisk brings something different to this dividend screen, because its GLP-1 and insulin franchises link everyday patient demand directly to the kind of recurring cash flow income investors look for when yield, coverage and stability all matter at once.
"In recent years, the company has been riding an extraordinary wave of success thanks to the global weight-loss drug boom. Its GLP-1-based drug semaglutide, originally developed for type 2 diabetes, turned out to be incredibly effective for weight loss."
What happens to Novo Nordisk’s dividend dependability if a single unseen pressure on cash conversion widens the gap between headline profits and free cash flow?
If that gap is what you care about, the full narrative for Novo Nordisk explains how Novo Nordisk’s cash engine, dividend profile and GLP-1 momentum could still be accelerating.

Seeking Fresh Alternatives Before They Fly
Markets move fast and the richest income and growth stories often gain momentum quietly before a full breakout. Spot fresh ideas while they are still under the radar for now, and consider them carefully.
- Identify cash generative businesses with resilient balance sheets using the curated list of solid balance sheet and fundamentals (23 results) before the crowd re-rates those fundamentals.
- Explore structural shifts in materials demand by scanning the focused 16 top copper producer stocks that highlights producers associated with the next leg of interest.
- Monitor early developments in automation and industrial efficiency through a targeted set of 95 robotics and automation stocks before broader attention potentially affects valuations.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com