
Does Apollo Contract Win Change The Bull Case For CACI Stock?
- CACI International announced a new Apollo contract with a ceiling of US$1.5b to support U.S. Central Command, expecting to book US$1.2b, alongside a role supplying optical imaging payloads for Vantor’s planned Vantor Pulse satellite fleet.
- The USCENTCOM work and the Vantor satellite engagement both lean on CACI International’s information advantage and space-based sensing capabilities, highlighting execution demands across complex, data-heavy defense missions.
- We will now look at how CACI International’s Apollo contract for USCENTCOM could influence its investment narrative around government technology demand.
Scan beyond CACI International and size up other defense and space-focused contractors through our curated list of 38 power grid technology and infrastructure stocks to see who else is positioning for complex mission support.
CACI International Investment Narrative Recap
To own CACI International, you need to believe it can keep winning complex national security and space contracts while turning a growing backlog into steadier earnings and cash generation. The recent Apollo award for USCENTCOM and the Vantor Pulse work both speak to demand for its information advantage and sensing platforms, which could support near term execution momentum.
The flip side is concentration and execution risk. CACI remains heavily tied to U.S. government budgets, competes hard for takeaway work, and already carries debt that analysts flag as not well covered by operating cash flow. If fixed price delivery, talent costs, or space manufacturing issues flare up, that becomes the near term pressure point.
The Apollo contract looks like the hinge event here. A one year plus four option periods award with a US$1.5b ceiling, and US$1.2b expected to be booked, directly connects to CACI International’s core pitch around information integration, irregular warfare support, and higher value tech work inside the defense market.
Your question is whether Apollo helps or stretches the business. It reinforces the catalyst of more complex, software heavy missions that align with the earnings growth analysts have outlined. At the same time, it increases delivery demands in a tight cleared labor market and adds more large scale work that has to be managed while debt and fixed price exposure remain key watch items.
CACI International's current earnings of US$535.8 million are projected to reach US$727.8 million by 2029, which implies earnings would rise by about US$192 million as analysts look for revenue to compound at roughly 8.3% a year and support an eventual revenue level of US$12.2b in 2029.
Uncover why CACI International's fair value indicates a 16% potential upside to its current price, which could narrow quickly as sentiment catches up.
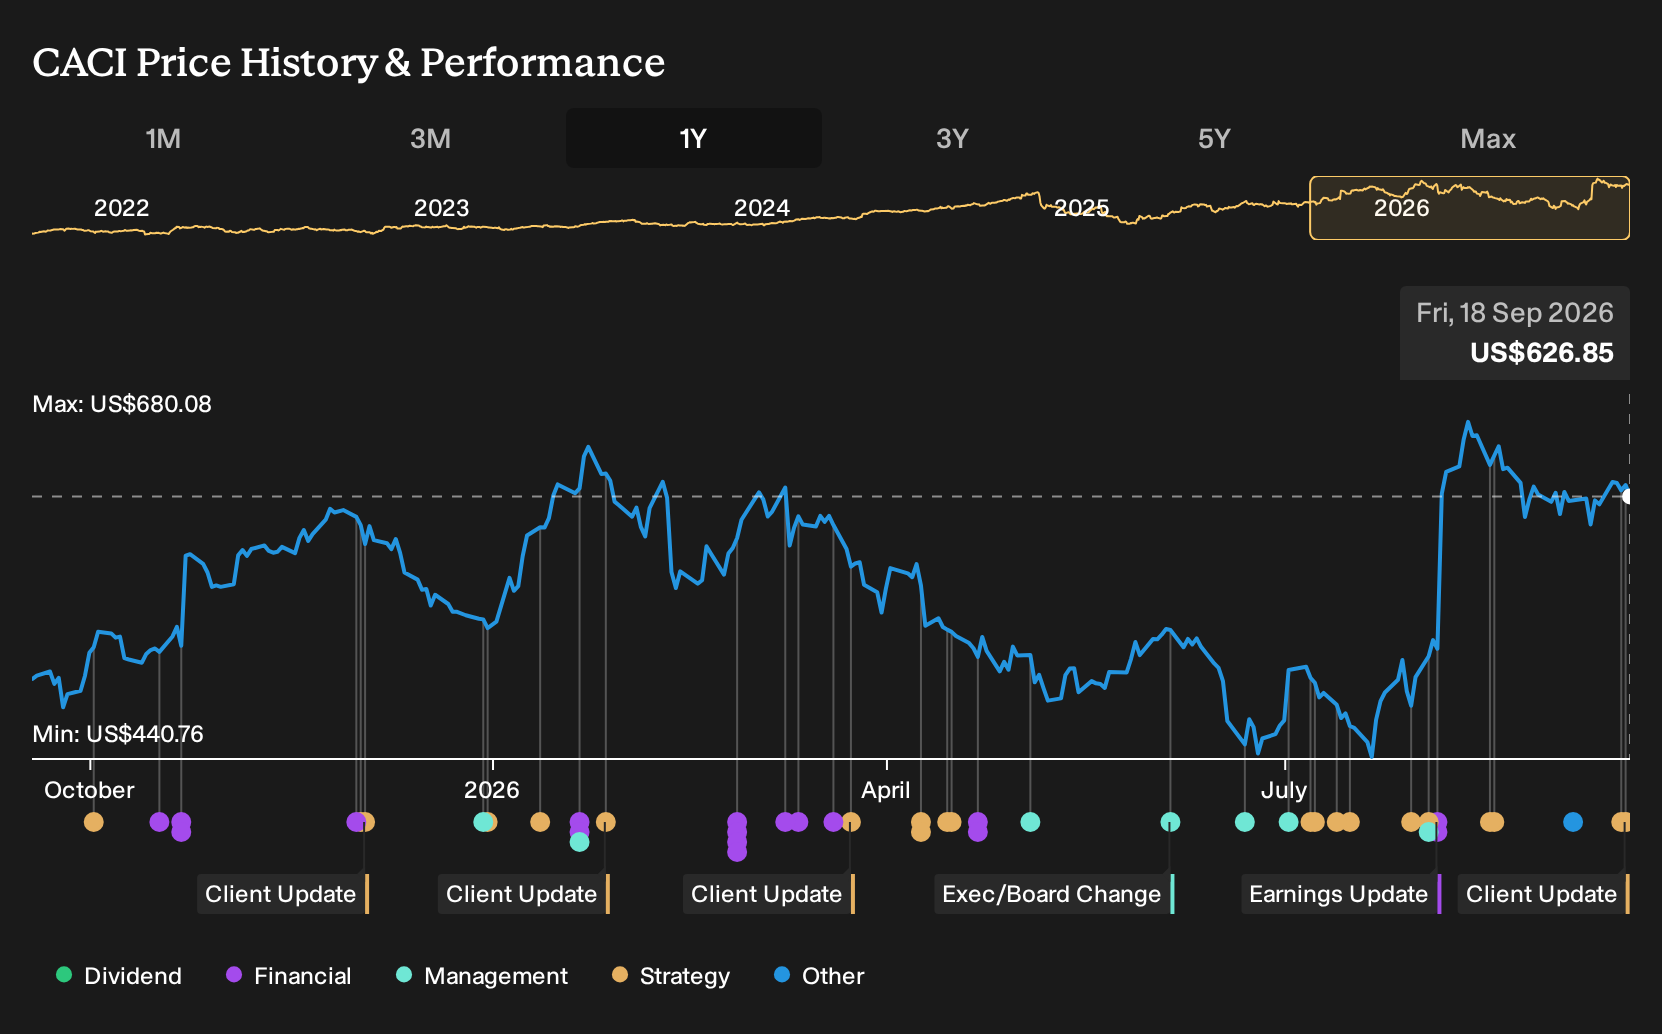
Exploring Other Perspectives
One alternate view says the bigger risk for CACI International is long term budget pressure. The most bearish analysts were assuming revenue of about US$11.7b and earnings near US$616.7m by 2029, well below consensus. That group already leaned cautious before Apollo and Vantor Pulse, so opinions may move around as new information lands.
Explore 3 other CACI International fair value estimates, including one that suggests it could be worth just $724.50.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your CACI International research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for CACI International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate CACI International's overall financial health at a glance.
Looking for more CACI International investment ideas?
If the CACI International story has you thinking about where else complex government spending and steady balance sheets might intersect, use the Simply Wall St Screener to widen your watchlist with a few targeted starting points.
- For investors hunting for potential mispricings backed by solid fundamentals, check companies on our 33 high quality undervalued stocks and see which ones merit a closer look.
- If resilience and capital strength sit high on your checklist, narrow in on businesses from the list of solid balance sheet and fundamentals (23 results) and focus on those with the support to handle tougher conditions.
- Income focused readers can review stocks in the 6 dividend fortresses and see which high yield payers match their risk tolerance and payout preferences.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com