
How Annex 1 Upgrades At West Pharmaceutical Services (WST) Have Changed Its Investment Story
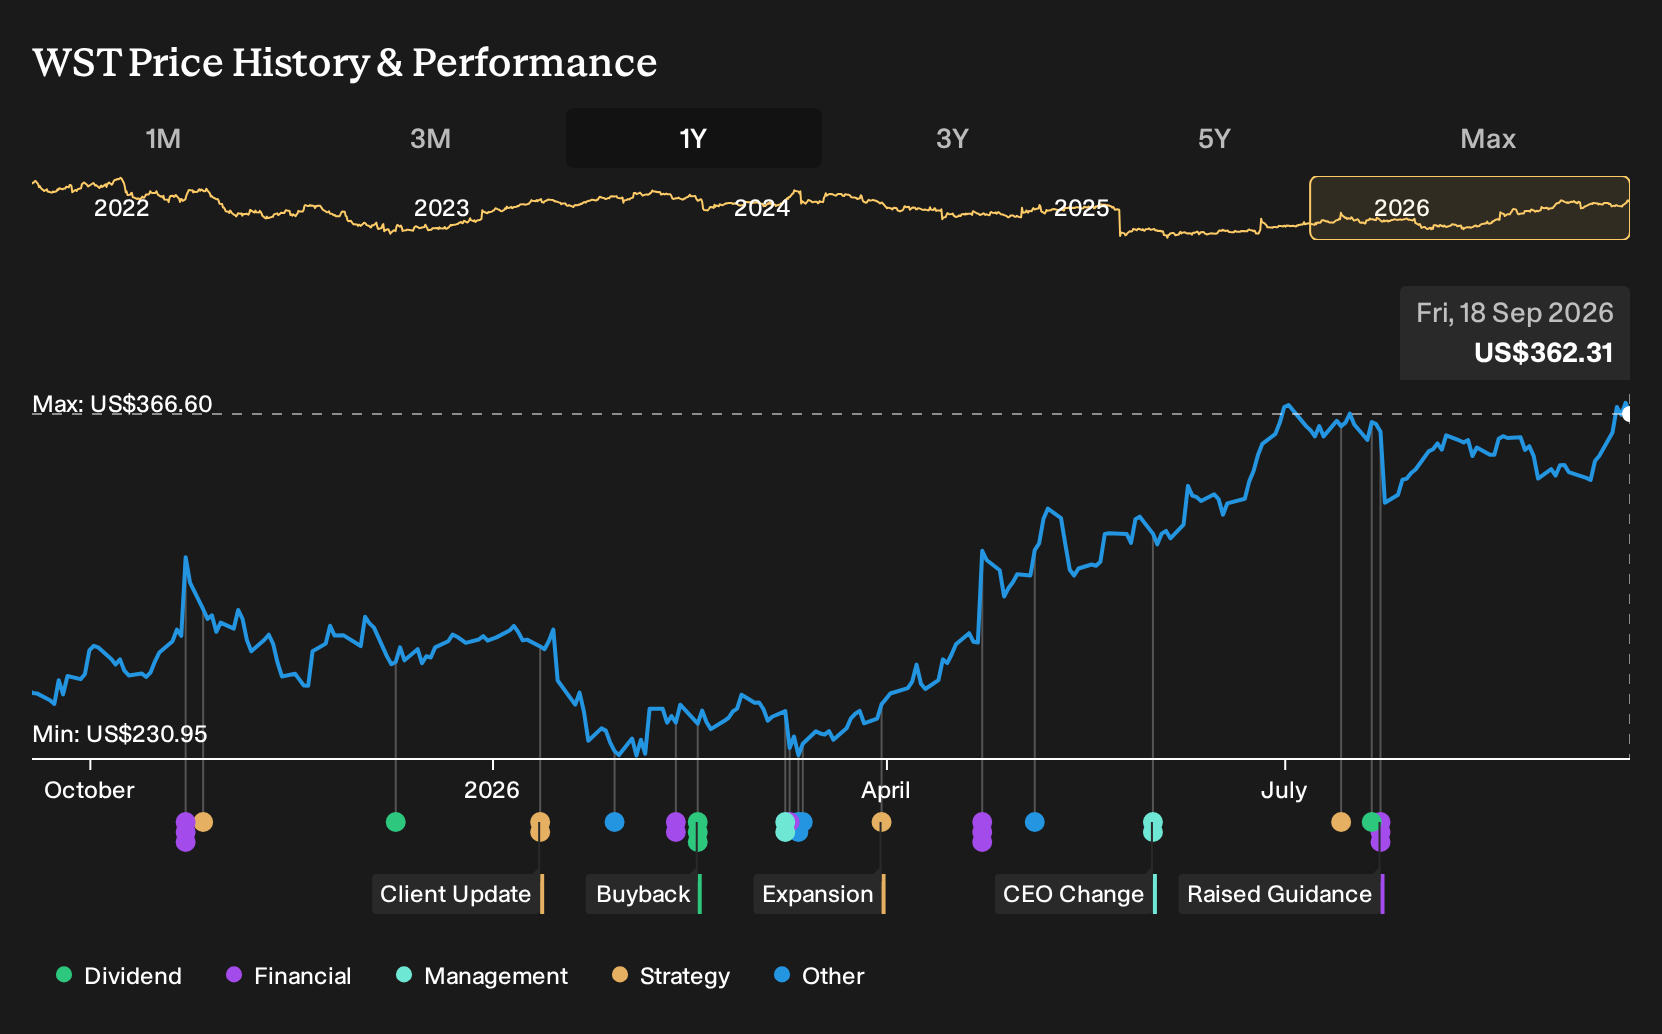
- West Pharmaceutical Services is reported to be well positioned for growth, supported by demand for high-value components, expanding biologics exposure, and regulatory-driven Annex 1 sterility and contamination-control projects. Recent performance has been pressured by weaker West Vantage results linked to a cyber incident and tariff-related cost inflation.
- An interesting angle for investors is how regulatory Annex 1 compliance work could support revenue and margin resilience, even as the West Vantage segment contends with operational disruption and higher costs.
- We will now look at how West Pharmaceutical Services' investment narrative is shaped by Annex 1 driven demand and West Vantage pressures.
Compare how West Pharmaceutical Services stacks up against other high quality healthcare suppliers by scanning a curated list of list of solid balance sheet and fundamentals (23 results) for your watchlist.
West Pharmaceutical Services Investment Narrative Recap
For you to own West Pharmaceutical Services, you need to believe that demand for high value components, biologics exposure and Annex 1 driven projects can outlast the current noise in West Vantage. The short term hinge is execution. Can core proprietary products keep running smoothly while the disrupted segment is repaired and cyber issues are contained?
The biggest operational risk right now sits in West Vantage. Weaker performance, higher tariffs and cyber related disruption create real pressure on costs and delivery. If mitigation work on pricing, supply chains and automation holds, the impact from this setback may be more of a timing issue than a structural break.
One announcement that matters most for this Annex 1 story is the plan for an automated line for high value product delivery devices, targeted between 2025 and early 2026. That initiative speaks directly to capacity, sterility and efficiency, all of which are central to handling growing biologics and GLP 1 related demand.
For you as a shareholder, that project links the current Annex 1 opportunity with future margin support. It could help offset tariff related cost pressure and the drag from contract manufacturing transitions into drug handling. The payoff still depends on disciplined execution, stable customer demand across facilities and tight control of cyber and restructuring risks.
West Pharmaceutical Services' narrative projects US$4.0b revenue and US$812.6m earnings by 2029. This assumes 6.4% yearly revenue growth and an earnings increase of about US$247.7m from US$564.9m today.
Uncover how West Pharmaceutical Services' fair value indicates an 11% potential upside to its current price before the market closes that discount.
Exploring Other Perspectives
Fair value estimates for West Pharmaceutical Services from the Simply Wall St Community span roughly US$313 to US$404, across 2 separate perspectives. Opinions already stretch wide before the recent cyber and tariff issues. You now need to weigh those pre event views against risks around execution, pricing and restructuring that could reshape the earnings path.
Explore another West Pharmaceutical Services fair value estimate, including one that suggests as much as 14% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your West Pharmaceutical Services research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for West Pharmaceutical Services. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate West Pharmaceutical Services' overall financial health at a glance.
Looking For More Investment Ideas Beyond West Pharmaceutical Services?
If you want to stress test your view on West Pharmaceutical Services, compare it with other opportunities that fit different risk and income profiles using the Simply Wall St Screener. Mix and match these tools to see how the stock lines up against potential alternatives across quality, yield and resilience.
- For investors who want potential upside with tighter risk controls, start by reviewing a focused group of 30 resilient stocks with low risk scores that keep volatility in check while still aiming for solid fundamentals.
- If you care most about reliable income, scan a curated set of 6 dividend fortresses that combine higher yields with business models built around ongoing cash returns to shareholders.
- When you are hunting for underappreciated opportunities, widen your search to a hand picked pool of 16 high quality undiscovered gems that pair financial strength with lower visibility on the market radar.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com