
Earnings Beat Might Change The Case For Investing In Supernus Stock (SUPN)
- Supernus Pharmaceuticals recently reported Q2 revenue of US$211.3 million, up 27.7% year on year, and lifted full year revenue and operating income guidance above prior indications.
- The Q2 update highlighted sustained traction from key CNS products and steady execution of the commercial plan, which together support management’s increased confidence in the company’s earnings power.
- We will now look at how Supernus Pharmaceuticals' stronger Q2 revenue and higher full year guidance could reshape its broader investment narrative.
Scan how Supernus Pharmaceuticals fits into the broader opportunity set by comparing its momentum against a curated 33 high quality undervalued stocks that also pair solid fundamentals with upgraded guidance stories.
Supernus Pharmaceuticals Investment Narrative Recap
To own Supernus Pharmaceuticals, you need to believe its core CNS portfolio can support a shift from recent losses toward more durable profitability. The stronger Q2, with revenue of US$211.3 million and higher full year guidance, reinforces that story in the near term. The key short term catalyst remains ongoing execution behind Qelbree, GOCOVRI and ONAPGO. The biggest immediate risk is still pricing pressure and payer pushback, especially where gross to net has already been heavy.
The latest numbers do not remove that risk. They simply show the commercial engine working harder against it. Rising SG&A and R&D, alongside reliance on a handful of lead products, still leave the business exposed if demand softens or new launches underperform. For a holder, the question is whether the current momentum in prescriptions and guidance is enough to offset those structural pressures while the pipeline, including SPN-820 and SPN-443, continues to progress.
The most relevant recent development tied to this Q2 beat is management’s decision to lift full year revenue and operating income guidance. That move points to greater confidence in how the Supernus Pharmaceuticals portfolio is performing in market, from ADHD to Parkinson’s disease. It also sharpens focus on execution. Hitting those upgraded ranges now serves as a clear operational yardstick over the next few quarters.
Higher guidance also interacts directly with the firm’s existing catalysts. Stronger cash generation can give Supernus more flexibility to support the ONAPGO rollout, fund late stage trials like SPN-820, and absorb elevated R&D without deepening losses. The flip side is that any miss against this higher bar could magnify concerns about pricing, competition from larger CNS players, and the time it may take for the pipeline to translate into a more balanced revenue mix.
Supernus Pharmaceuticals' narrative projects US$1.2b revenue and US$168.8 million earnings by 2029. This assumes 15.7% yearly revenue growth and an earnings increase of about US$197.8 million from current earnings, which are a US$29.0 million loss.
Uncover why Supernus Pharmaceuticals' fair value indicates a 50% potential upside to its current price, which could narrow quickly.
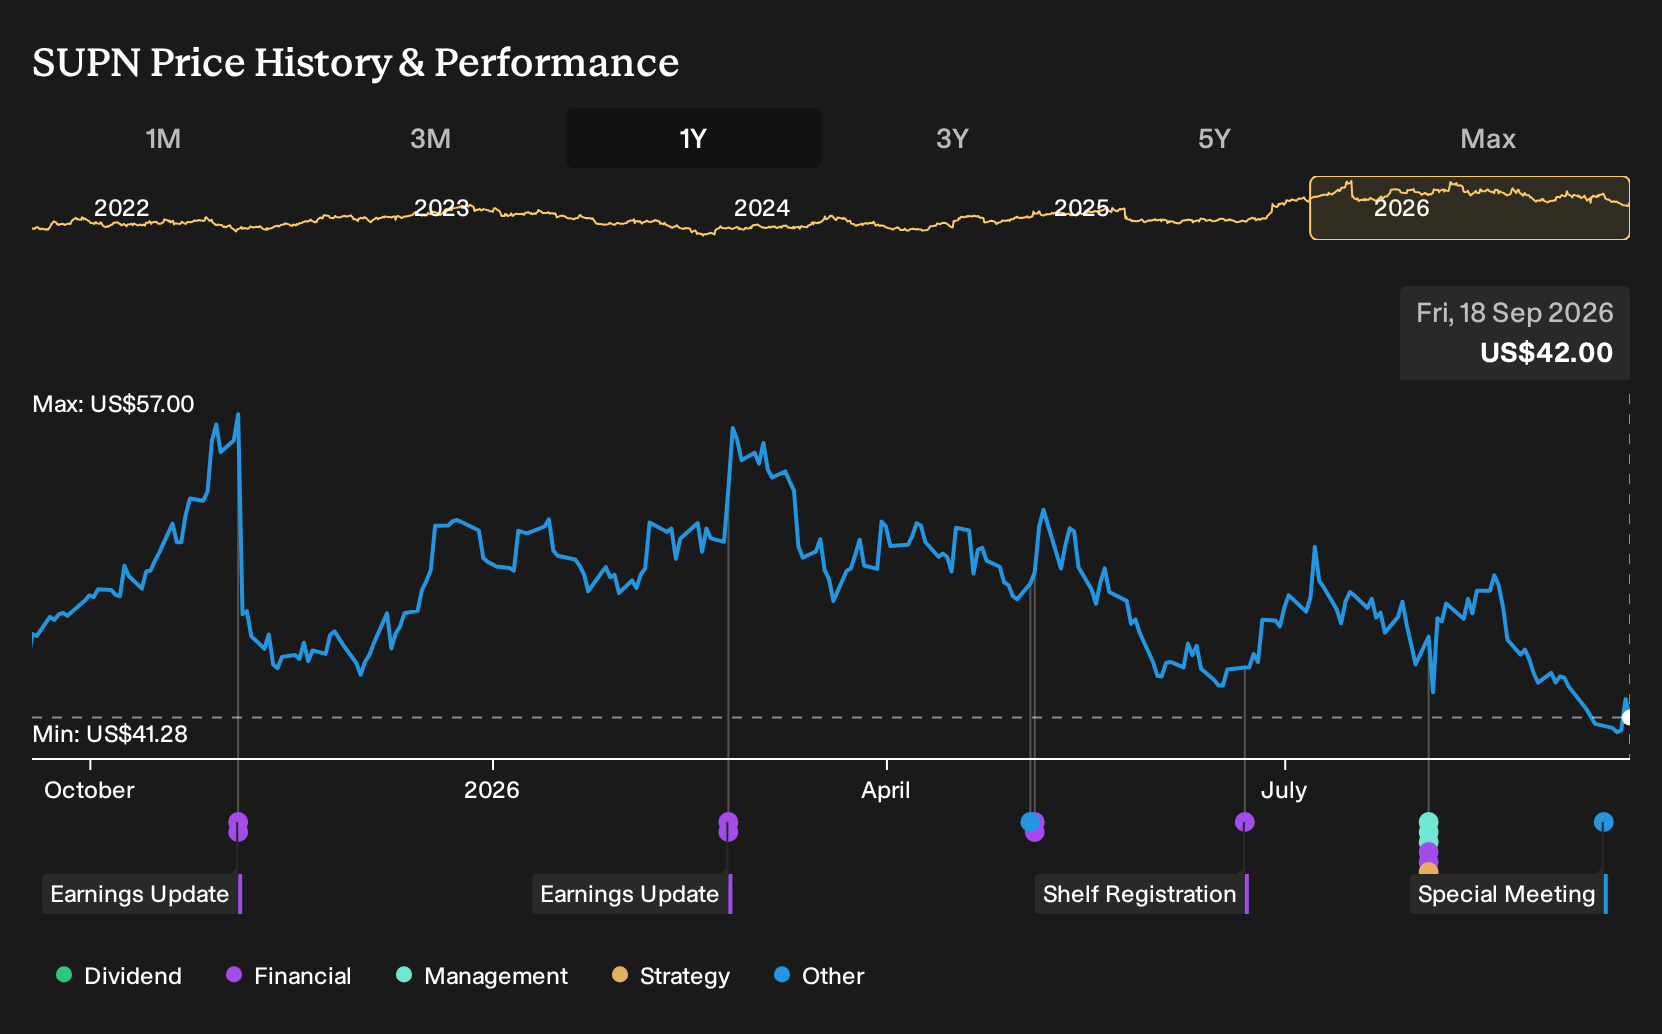
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span a wide range, from about US$62.8 to roughly US$210.3 per share. This highlights how far apart views on Supernus Pharmaceuticals can be. Consider those opinions in the context of drug pricing pressure, concentrated product exposure, and pipeline uncertainty, then explore more community viewpoints before forming a stance.
Explore another Supernus Pharmaceuticals fair value estimate, including one that suggests an upside of as much as 401% from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Supernus Pharmaceuticals research is our analysis highlighting 3 key rewards that could impact your investment decision.
- See our latest analysis for Supernus Pharmaceuticals. The report includes a comprehensive fundamental analysis summarized in a single visual: the Snowflake, which makes it easy to evaluate Supernus Pharmaceuticals' overall financial health at a glance.
Looking For More Investment Ideas Beyond Supernus Pharmaceuticals?
Once you have a view on Supernus Pharmaceuticals, it can help to widen the lens and compare it with other businesses that share similar qualities or offer very different risk and reward profiles. A targeted screener can quickly surface candidates that match the themes you care about most, from valuation support to balance sheet strength or under-the-radar opportunities.
- If you want a starting pool of companies that combine quality metrics with room for a potential re rating, scan a curated set of 33 high quality undervalued stocks that already pair solid fundamentals with supporting data.
- When capital preservation matters just as much as upside, narrow your search to a 30 resilient stocks with low risk scores that may suit a more cautious investing style.
- For investors hunting for potential future Supernus like stories before they are widely followed, filter the market through a 16 high quality undiscovered gems that focuses on strong fundamentals hiding in plain sight.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com