
How Weaker Traffic Will Impact Cracker Barrel Stock Investors
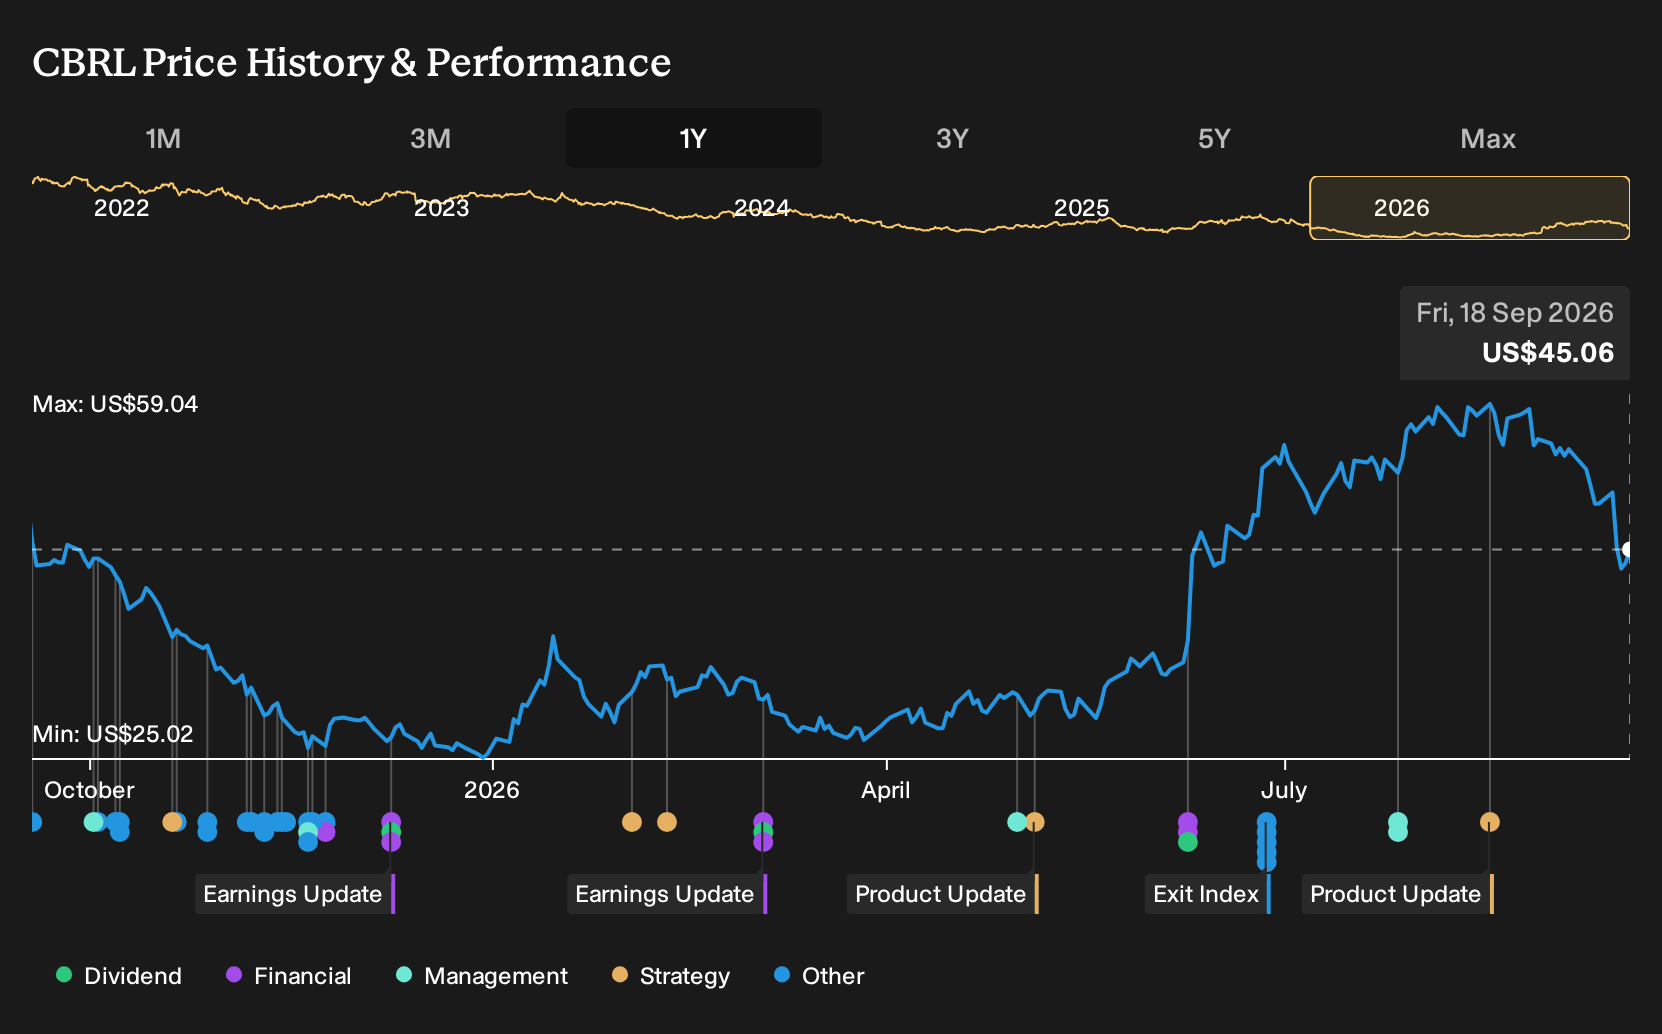
- Cracker Barrel Old Country Store recently reported softer restaurant traffic tied to higher gas prices and changing consumer spending, while management reaffirmed fiscal 2026 revenue guidance despite these pressures.
- The rising use of GLP-1 weight loss drugs is starting to reshape guest eating patterns, creating a new structural headwind for Cracker Barrel’s sit-down dining model.
- We will explore how Cracker Barrel's investment narrative holds up as GLP-1 driven eating shifts continue to pressure already fragile restaurant traffic trends.
Scan how other restaurant and consumer-facing operators are handling similar headwinds by reviewing our curated list of solid balance sheet and fundamentals (23 results) to compare them with Cracker Barrel Old Country Store.
Cracker Barrel Old Country Store Investment Narrative Recap
For Cracker Barrel Old Country Store, the core belief is that efforts to improve guest experience, refine pricing and refresh stores can offset pressure on traffic and margins. Recent commentary on softer visits tied to gas prices and GLP-1 usage directly tests that view. The key short term catalyst is whether these operational tweaks can stabilize guest counts without eroding perceived value.
The biggest risk right now is that weaker dining room traffic combines with already thin 0.8% net margins and high debt, leaving little room for error if costs flare up again. If GLP-1 driven eating shifts prove sticky, investors need to watch whether digital, off premise and menu simplification can realistically absorb that drag.
The reaffirmed fiscal 2026 revenue guidance is the most relevant recent announcement in this context. It signals management still sees the guest journey work, menu adjustments and pricing capability as enough to support the top line despite softer traffic and GLP-1 headwinds. That stance effectively sets a benchmark investors can track against reported sales over the next few quarters.
For you as a shareholder, this guidance frames the near term debate. If reported revenue stays on track, it supports the case that Cracker Barrel Old Country Store’s transformation around service standards, restaurant processes and refreshed formats is gaining traction. If sales or mix trend below that bar, concerns around low returns, refinancing costs on the US$300m convertible debt and ongoing G&A pressure move quickly back into focus.
Cracker Barrel Old Country Store's current analyst narrative points to revenue of US$3.5b and earnings of US$42.7 million by 2029, supported by assumed yearly sales growth of 1.8% and a projected earnings increase of about US$16.5 million from the current US$26.2 million level.
Uncover why Cracker Barrel Old Country Store's fair value indicates a value roughly in line with its current price.
Exploring Other Perspectives
One argument from the more bearish side is that Cracker Barrel Old Country Store’s highway heavy footprint could struggle if travel patterns keep evolving. Those analysts were already working with softer assumptions, such as revenue growth of 1.6% a year and earnings of about US$34.5 million by 2029. You can treat this as a reminder that analyst opinions span a wide range, and that both consensus and bearish forecasts were set before this latest traffic and GLP-1 news. As a result, they may shift as fresh data arrives.
Explore 3 other Cracker Barrel Old Country Store fair value estimates, including one that suggests as much as 62% downside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Cracker Barrel Old Country Store research is our analysis highlighting 1 key reward and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Cracker Barrel Old Country Store. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cracker Barrel Old Country Store's overall financial health at a glance.
Looking For More Ideas Beyond Cracker Barrel Old Country Store?
If the Cracker Barrel Old Country Store story has you reassessing where traffic, pricing power and balance sheet strength intersect, it can help to widen the lens and compare it with other businesses facing very different sets of pressures and opportunities.
- For readers focused on value with quality backstops, scan through 33 high quality undervalued stocks that pair discounted pricing with stronger underlying fundamentals.
- If income is a priority, review 6 dividend fortresses to see which high yielding companies have the balance sheet support to maintain those payouts.
- For those who care most about resilience, filter for 30 resilient stocks with low risk scores that score well on capital strength and business risk metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com