
Is Attribution Launch Altering The Investment Case For LiveRamp (RAMP)?
- Albertsons Media Collective recently launched an Incrementality-Based Multi-Touch Attribution solution, developed in partnership with LiveRamp, to give advertisers a unified, deduplicated view of incremental sales impact across major digital platforms in a privacy-conscious environment.
- This first-to-market, grocery-exclusive collaboration showcases how LiveRamp’s Cross-Media Intelligence infrastructure is being used in retail media to connect impression-level exposure with transaction data and to simplify measurement for large brands such as PepsiCo.
- The next consideration is how LiveRamp Holdings’ broader investment narrative could be affected by powering this incrementality-based, multi-touch attribution platform.
See how LiveRamp Holdings fits into the broader shift toward data-driven advertising by reviewing a curated set of retail and consumer-focused platforms in our 16 high quality undiscovered gems.
LiveRamp Holdings Investment Narrative Recap
To own LiveRamp Holdings, you need to believe privacy conscious data collaboration and measurement remain essential for large advertisers as customer journeys get more complex. The Albertsons Media Collective launch leans into this idea by putting LiveRamp’s infrastructure directly in the path of retail media budgets, which supports the broad data connectivity story rather than changing it.
The sharper near term swing factor still looks like execution on mid single digit to high single digit revenue growth, while earnings expectations trend lower over the next few years. Concentration in large enterprise clients and rising competition in clean rooms and identity are unchanged as key risks, and this announcement alone does not meaningfully reduce them.
The Albertsons incrementality based multi touch attribution product is the clearest recent proof point that LiveRamp’s Cross Media Intelligence stack is being used in real, high stakes measurement workflows. It puts the platform inside a grocery exclusive environment, alongside Meta and Google pipes, with PepsiCo already testing outcomes.
For you as an investor, the relevance sits in execution. If LiveRamp can replicate this type of integration with other retail and media partners, it may support the idea that usage based pricing and data collaboration tools keep volumes stable, even if headline revenue growth slows. Failure to broaden beyond a handful of large arrangements would reinforce the existing concentration and competitive risks.
What The LiveRamp Holdings Consensus Is Pricing In
LiveRamp Holdings is being modeled as a slower growing, still profitable data infrastructure play, and the analyst numbers around 2029 set a clear bar for what the market is already weighing.
Based on current consensus, LiveRamp Holdings is pegged to grow revenue by 8.0% a year over the next few years, while profit margins move from 17.8% today to 12.5% in 2029. Earnings sit at $144.8 million today and are projected to be $127.5 million by 2029, which is a decline of $17.3 million from current levels.
On those 2029 figures, analysts see LiveRamp Holdings earning $2.74 per share, with the equity valued on a P/E of 19.7x compared with 15.8x today. That framework also assumes the share count shrinks by 7.0% a year and that investors use an 8.6% discount rate when weighing future cash flows. Together, these inputs outline the risk and return profile currently being applied.
If you accept the consensus case, by 2029 LiveRamp Holdings would be generating about $1.0b in revenue and $127.5 million in earnings, with the stock supported by a $40.58 price target, 7.3% above the recent $37.61 share price. The relatively small gap between those numbers suggests analysts broadly see the stock as close to fairly valued on these inputs, with target prices ranging from $38.0 on the low end to $50.0 on the high end.
LiveRamp Holdings' current consensus outlook points to revenue of $1.0b and earnings of $127.5 million by 2029, based on 8.0% yearly revenue growth and an earnings decline of $17.3 million from $144.8 million today.
Uncover why LiveRamp Holdings' fair value indicates an 8% potential upside to its current price that could narrow quickly.
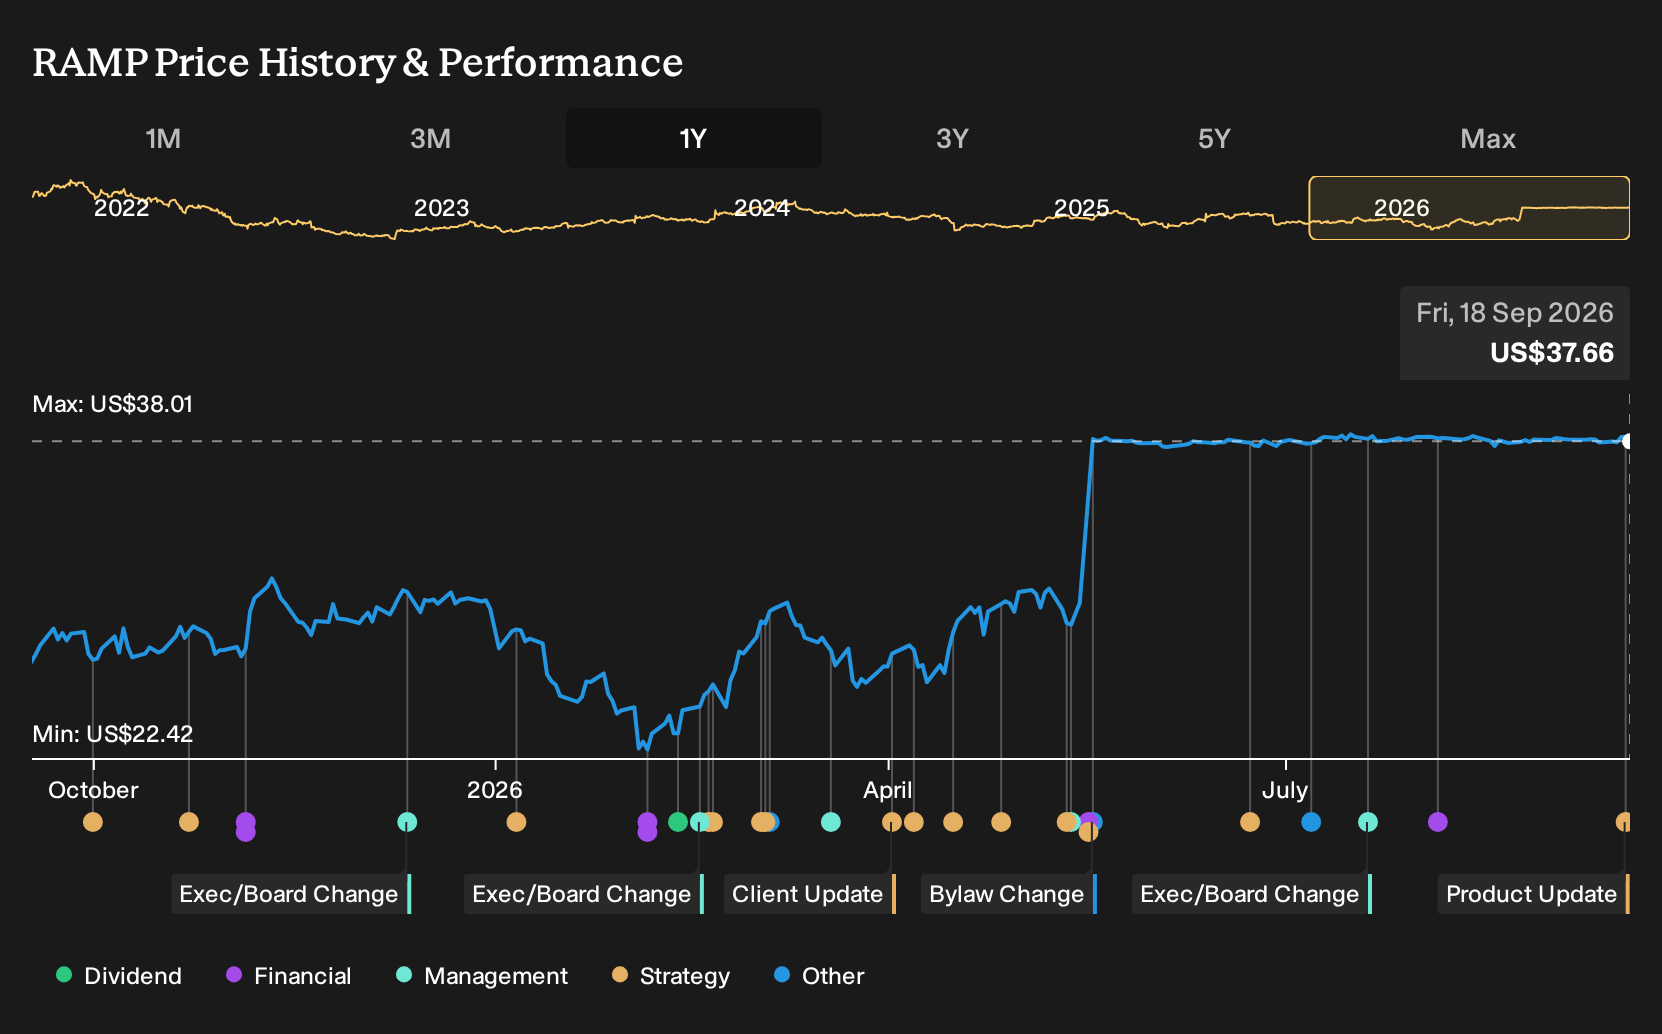
Exploring Other Perspectives
Privacy risk is the big swing factor that separates the lowest estimates from the baseline view on LiveRamp Holdings. Before this Albertsons Media Collective launch, the most cautious analysts were modeling earnings of about $112.9 million by 2029 on roughly $1.0b of revenue. That is a materially harsher read on regulation and data usage. You should treat this new attribution deal as a fresh input and explore how both stories might evolve from here.
Explore 3 other LiveRamp Holdings fair value estimates, including one that suggests as much as 25% downside from the current price!
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your LiveRamp Holdings research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for LiveRamp Holdings. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate LiveRamp Holdings' overall financial health at a glance.
Looking For More LiveRamp Holdings Investment Ideas?
If the LiveRamp Holdings story has you thinking about where else data, cash flow resilience, and balance sheet strength might matter, it can help to widen the lens and compare it with other businesses using the Simply Wall St Screener.
- For investors who want potential upside with a margin of safety, scan companies that combine quality fundamentals with valuations that look modest using our 33 high quality undervalued stocks.
- If steady income is a priority, focus on businesses that pair higher yields with sturdier financial profiles by reviewing a curated set of 6 dividend fortresses.
- When capital preservation is front of mind, narrow your watchlist to companies that score well on financial strength metrics via a 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com