
Armstrong World Industries (AWI) Could Be 22% Undervalued On Its Energy Efficient Growth Story
Armstrong World Industries (AWI) just highlighted its community footprint, with the Armstrong World Industries Foundation awarding more than $600,000 in 2026 Better Building Grants to 10 nonprofits focused on facility upgrades and essential services.
Recent trading has been less supportive, with Armstrong World Industries’ share price down 10.6% over the past month and lower year to date, although the 3-year total shareholder return of about 130% and 5-year total shareholder return of roughly 67% still point to longer term momentum that predates this latest pullback.
Spot similar community-focused stories and price pullbacks by scanning our hand-picked 30 resilient stocks with low risk scores, which pairs solid financial profiles with more resilient trading histories than Armstrong World Industries recently delivered.Armstrong World Industries now combines community investment with a share price that has pulled back and sits below analyst targets. Does that shift the risk reward balance toward buyers, or is the recent slide a warning signal?
Most Popular Narrative: 22% Undervalued
Analysts following Armstrong World Industries see a fair value of $204.10 against a last close of $159.63. This frames the recent pullback as a potential discount rather than a permanent reset in expectations.
The acceleration of TEMPLOK and other energy-efficient ceiling solutions, supported by the inclusion of phase change materials in key tax credits and major design software, positions Armstrong to benefit from increasing building decarbonization and energy savings requirements, potentially driving higher future sales volumes and AUV, and enhancing gross margins.
See why 2 investors see Armstrong World Industries as 22% undervalued.
Result: Fair Value of $204.10 (UNDERVALUED)
Still, the narrative around Armstrong World Industries depends on commercial construction not softening further and on acquisitions delivering the benefits that analysts have built into their models.
Find out about the key risks to this Armstrong World Industries narrative.
Another View: Armstrong World Industries And The Cash Flow Gap
The analyst narrative points to Armstrong World Industries being undervalued based on earnings forecasts and target P/E, yet the Simply Wall St DCF model paints a very different picture. On a future cash flow basis, the stock at $159.63 screens as expensive versus an estimated value of $84.83.
That gap suggests you are paying a premium price today for cash flows the model treats cautiously. The question is whether you trust the earnings based story more than the cash flow math, or take this as a signal to build in a wider margin of safety.
Look into how the SWS DCF model arrives at its fair value.
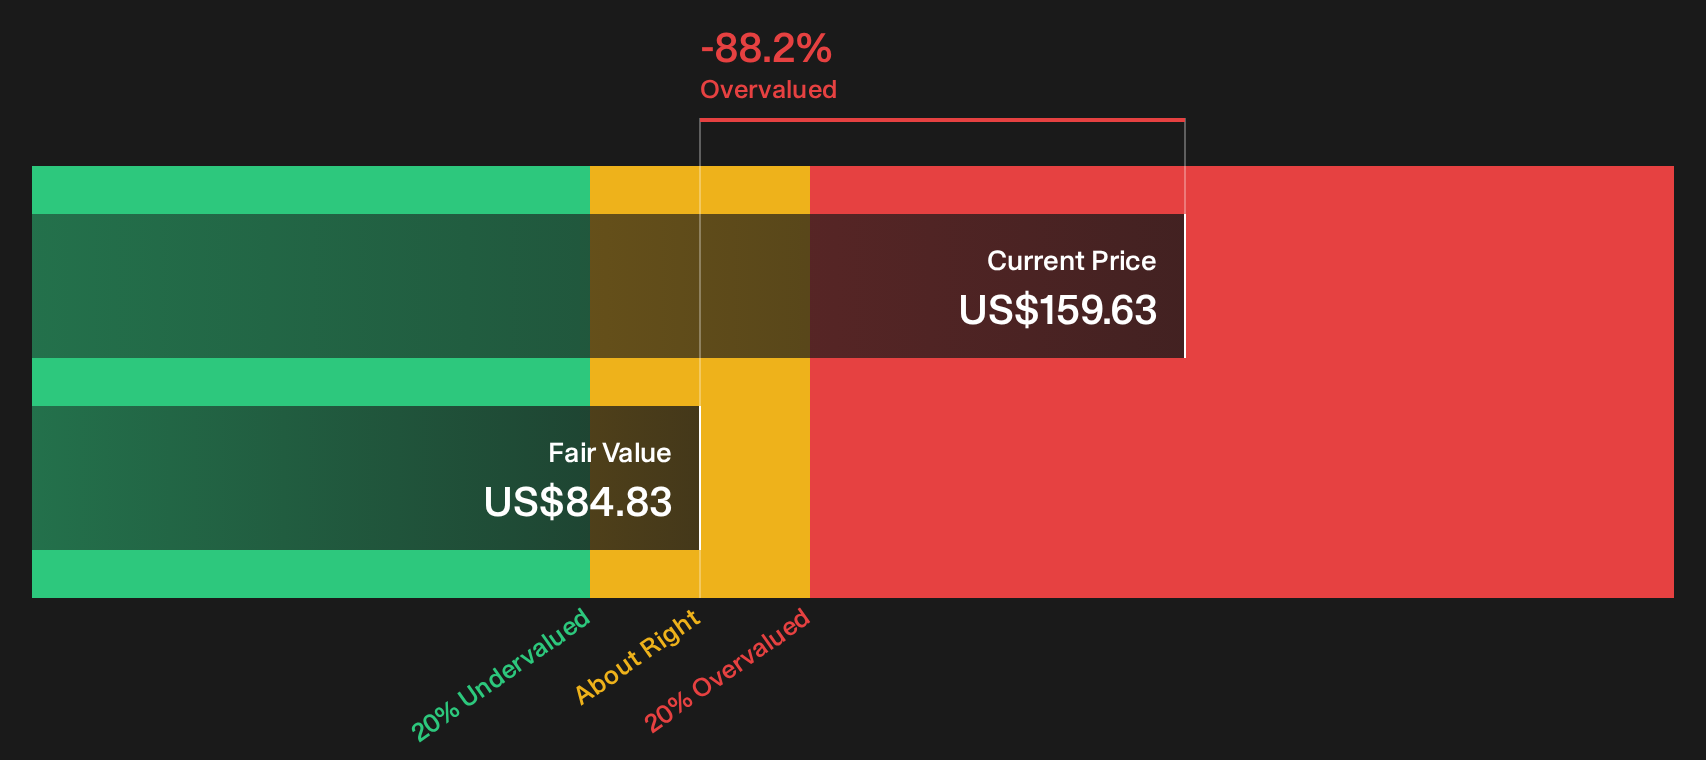
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Armstrong World Industries for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed messages around Armstrong World Industries leave you unsure, treat that as your prompt to move fast. Review the facts and make your own call based on the 3 key rewards and 1 important warning sign.
Looking for more Armstrong World Industries style investment ideas?
If Armstrong World Industries has caught your attention, do not stop there. Use the Simply Wall St screener tools to quickly surface other opportunities that fit your style.
- Target value opportunities by reviewing companies on the 33 high quality undervalued stocks that share solid fundamentals with more appealing price tags.
- Strengthen your income stream by scanning the 6 dividend fortresses that focus on reliable payouts with yields that may suit long term holders.
- Prioritise resilience by working through the list of solid balance sheet and fundamentals (23 results) to find businesses backed by stronger financial footing than many broad market options.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com