
Is Tightening Tampa Apartments Altering The Investment Case For Colliers Stock?
- Colliers International Group reported that Tampa's multifamily market has experienced a pricing power reset, with slowing new construction reducing incoming apartment supply and strengthening rental absorption across existing properties as of September 2026.
- The shift toward tighter multifamily conditions in Tampa highlights how Colliers' on the ground brokerage and advisory data can inform views on demand for its wider real estate services tied to existing income producing assets.
- We will now examine how Colliers International Group's investment narrative could be influenced by tighter Tampa multifamily supply and stronger absorption.
Compare Colliers International Group's view on tightening Tampa apartments with other real estate focused plays by reviewing the curated list of solid balance sheet and fundamentals (7 results).
Colliers International Group Investment Narrative Recap
Owning Colliers International Group means believing the business can convert its global brokerage, outsourcing, engineering, and investment management platform into steadier fee income over time while managing debt that is not well covered by operating cash flow. The Tampa multifamily update points to pockets of healthier leasing demand, but on its own it does not materially shift the near term outlook.
The key near term swing factor is still transaction and leasing activity across major regions, particularly where industrial and capital markets exposure is high. The biggest risk remains pressure on margins and earnings if deal volumes stay soft or fundraising in investment management lags, given Colliers International Group also leans on acquisitions for growth.
Recent commentary around Tampa multifamily conditions effectively acts as a micro case study for Colliers International Group. Slower new construction and stronger apartment absorption speak to the type of on the ground data the firm can monetize through brokerage, leasing, and advisory work tied to income producing assets.
For you as a shareholder, the relevance sits in execution. The more Colliers International Group can turn localized pockets of healthier demand into leasing mandates, capital markets deals, and property management assignments, the more it supports the catalyst of higher recurring fees, while still leaving the broader risks around leverage, transaction cyclicality, and technology driven fee pressure firmly in view.
Colliers International Group Forecasts and What They Assume
Colliers International Group's current analyst narrative points to revenue of $7.8 billion and earnings of $185.4 million by 2029. That profile builds on an assumed 9.3% yearly revenue growth rate and an earnings move of about $77.6 million, from $107.8 million today to the 2029 consensus figure.
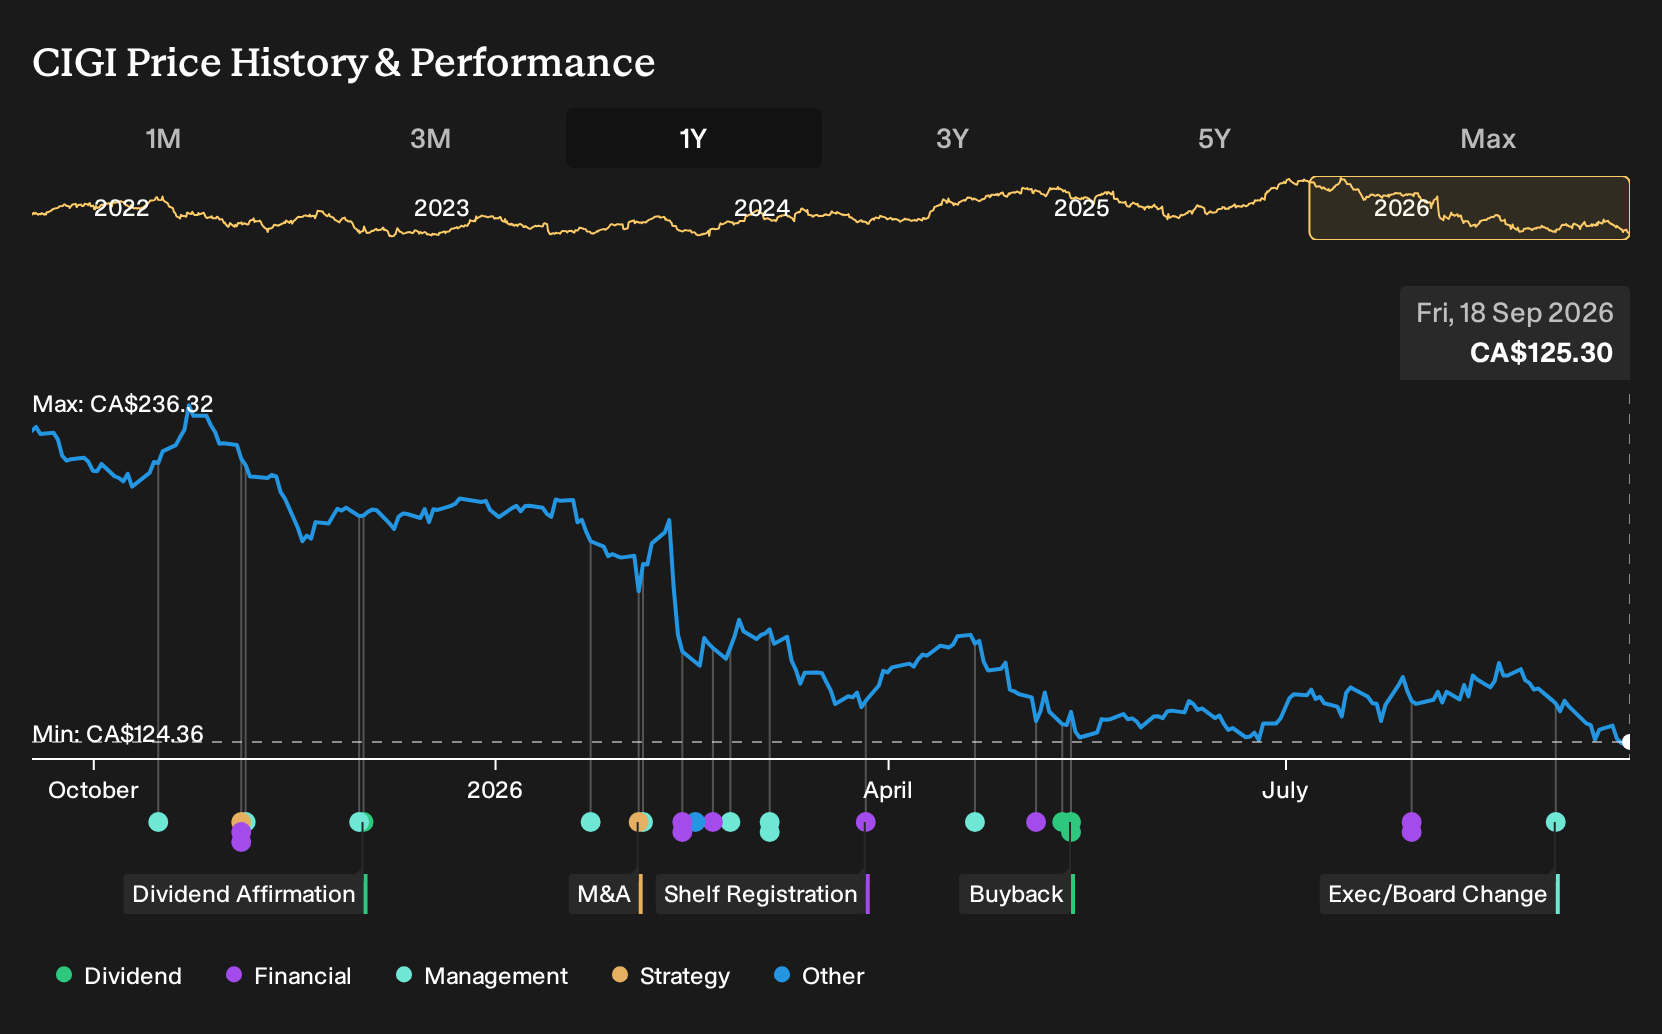
Discover how Colliers International Group's fair value indicates a 53% potential upside to its current price, which may not last much longer.
Exploring Other Perspectives
One alternate view on Colliers International Group leans heavily on margin pressure. The most cautious analysts were looking for revenue of about $7.5b and earnings near $178.0 million by 2029, which is below the consensus $7.8b and $185.4 million. Tampa’s tighter apartments data could challenge or reinforce those expectations, so it may be useful to explore both angles.
Explore 3 other Colliers International Group fair value estimates, including one that suggests it could be worth just CA$129.08.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider relying on your own analysis.
- A great starting point for your Colliers International Group research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Colliers International Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Colliers International Group's overall financial health at a glance.
Looking for more Colliers International Group sized ideas?
If the Colliers International Group story has you thinking about what else might fit your portfolio, it can help to scan for other businesses with characteristics that match your risk and income goals using the Simply Wall St Screener.
- For investors hunting for quality at a reasonable price, start with companies that screen as 4 high quality undervalued stocks and see which ones match your own thesis.
- If resilience matters most to you, focus on balance sheets that look robust by filtering through the list of solid balance sheet and fundamentals (7 results) and narrowing down candidates from there.
- Those seeking income can concentrate on stocks with higher yields by reviewing a curated set of 1 dividend fortresses and checking which payouts align with their tolerance for risk.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com