
Japan Rate Shift Puts Regional Bank Stocks Like Shiga Bank In Focus
Japan has finally moved off rock bottom interest rates, and that shift is rippling through every corner of the domestic financial sector. A higher policy rate can reshape how banks, insurers, and lenders earn money, and it can also expose who has been leaning most on cheap funding. If you care about where capital could quietly migrate next, this article walks through three Japanese financial stocks exposed to this new rate reality.
The three Japanese financial stocks covered next are only a starter set, and the full screen surfaced 8 more domestically focused banks and lenders with equally compelling stories that are not included in this article. To identify and analyze your own highest conviction ideas in this space, head straight into the Japanese Domestic-Focused Banks and Financials screener.
North Pacific BankLtd (TSE:8524)
North Pacific BankLtd is a Sapporo based lender focused on classic deposit and loan services for households and corporates across Japan, which fits cleanly with the Japanese Domestic-Focused Banks and Financials theme, and carries a market value of about ¥494.6b.
This is a pure domestic banking story, with all reported revenue of about ¥232.2b coming from Japan and earnings forecast to grow 20.88% a year, yet a P/E of 17.7x, high bad loans at 11.2% and relatively thin reserves. The benefit from higher local rates will depend on how one unseen pressure plays out.
That unseen pressure is exactly what the 2 key rewards and 3 important warning signs could be clarifying for North Pacific BankLtd as higher rates start to bite and reward.
Shiga Bank (TSE:8366)
Shiga Bank is a regional lender anchored in Otsu that fits cleanly into the Japanese Domestic-Focused Banks and Financials theme, with all ¥139,740 million in revenue coming from banking activities in Japan and a market value of about ¥662.7b.
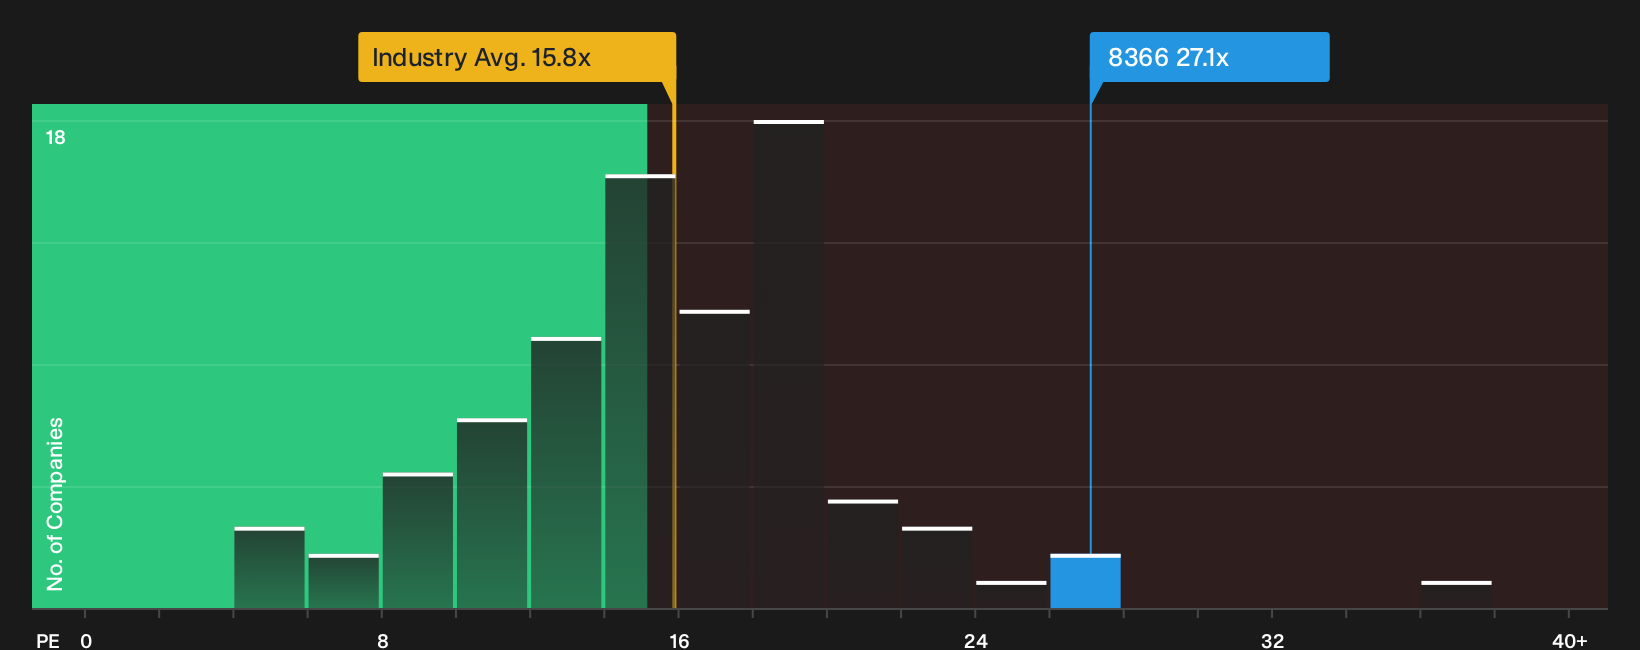
Shiga Bank is closely linked to the Bank of Japan’s rate environment, with all income tied to domestic banking and recent guidance indicating earnings growth in line with rising net interest income. The premium P/E and relatively thin loan loss reserves keep attention focused on what could happen if a single key assumption fails.
If that single assumption breaks, the 2 key rewards and 2 important warning signs could show whether Shiga Bank’s premium is masking fragility or signaling early repricing strength.
77 Bank (TSE:8341)
77 Bank is a Sendai based lender focused on domestic banking for households and corporates, a straightforward fit with the Japanese Domestic-Focused Banks and Financials theme, and it carries a market value of about ¥934.1b.
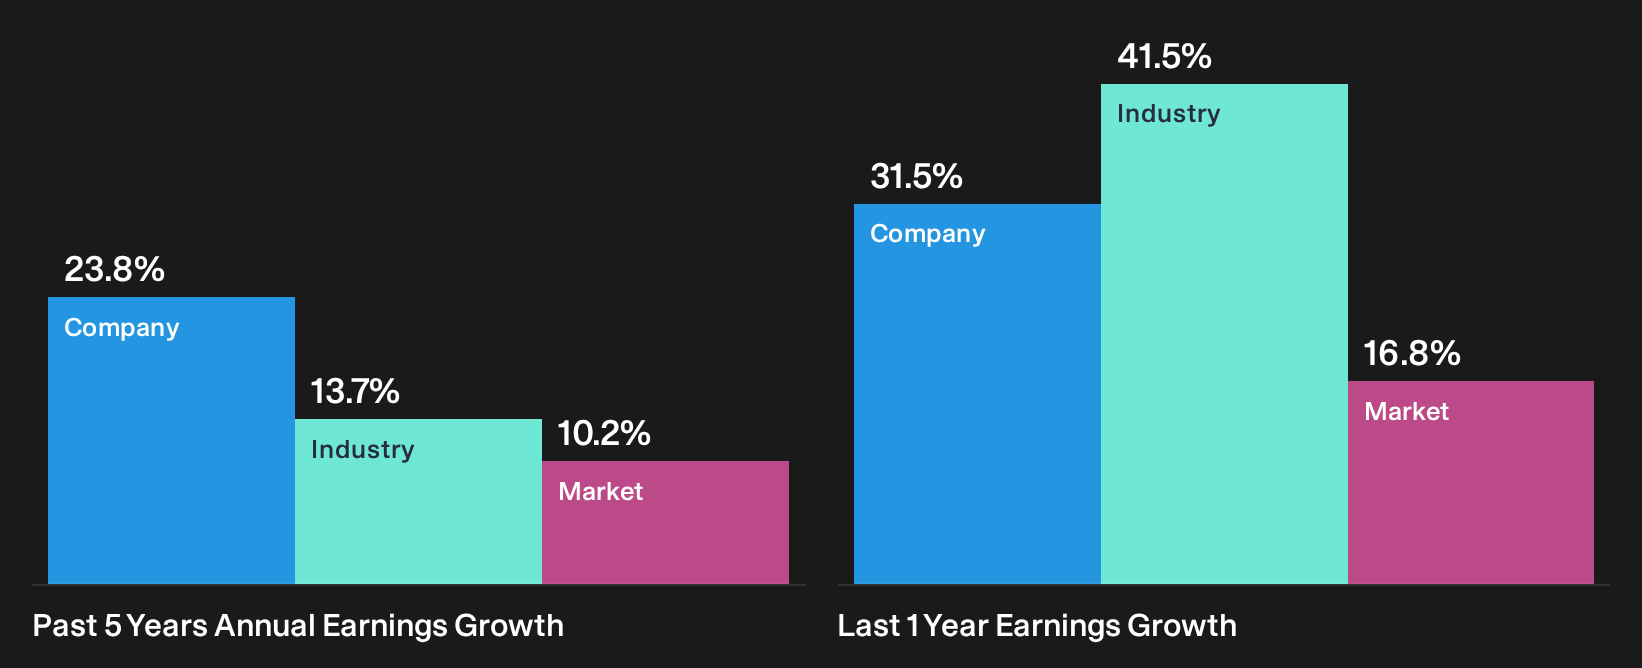
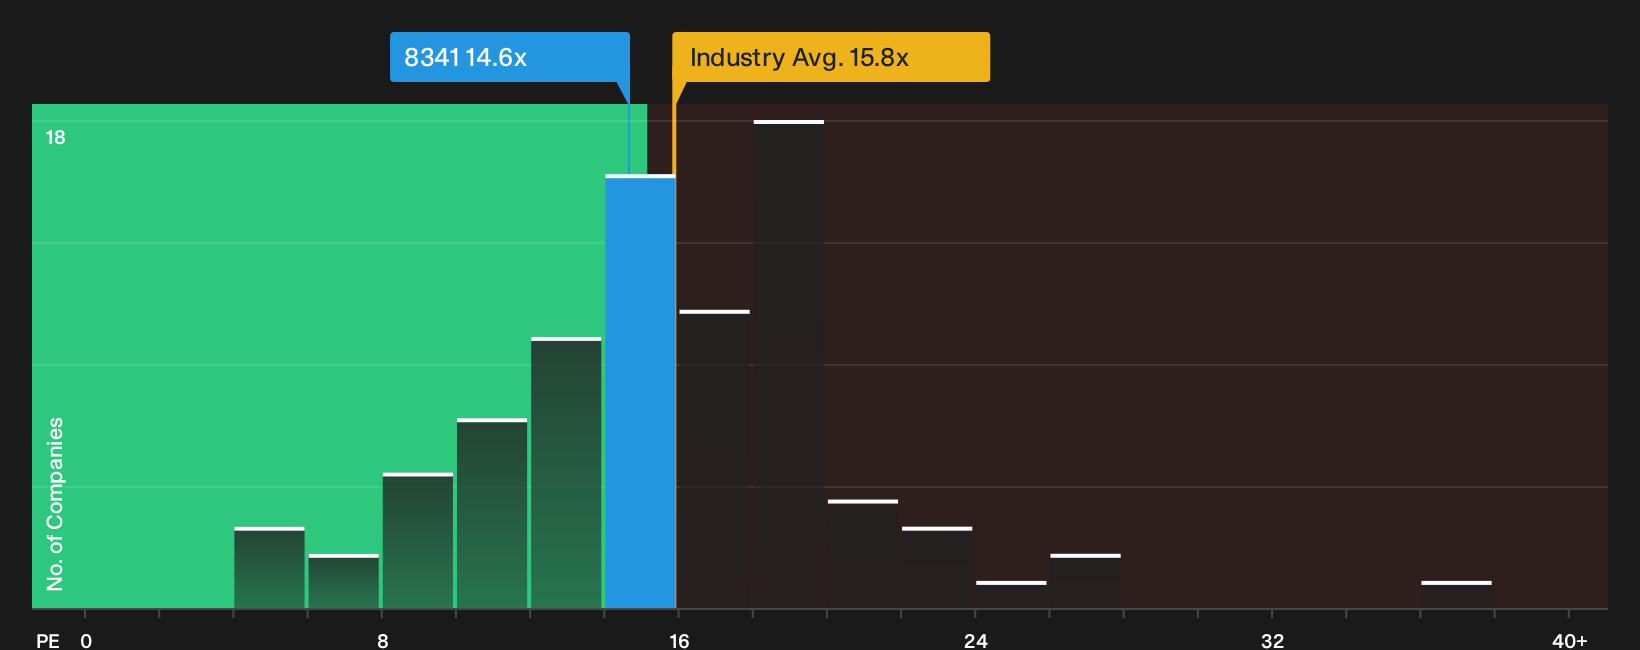
For a theme built around rising Japanese rates, 77 Bank offers a clean play on domestic lending, with earnings up 58.8% over the past year and a P/E of 14.6x that sits below the wider banks industry. Income investors also get a 2.49% dividend yield, although everything hinges on how one unresolved path for future margins develops.
That unresolved path for future margins is exactly what the 5 key rewards and 1 important warning sign can unpack for 77 Bank before the rate cycle reshapes its earnings profile.
Seeking Fresh Alternatives Before They Fly
New themes are gathering momentum and early movers usually get the cleanest entry points. Scan fresh ideas before they are fully caught by the crowd and act now.
- Spot cash generative leaders before sentiment catches up by running a focused pass through the 17 high quality undervalued stocks while that mispricing window is still open.
- Track where the next wave of data center and chip demand could flow by scanning the curated 89 AI infrastructure stocks while it is still under the radar for now.
- Target resilient balance sheets instead of chasing hype by filtering for the curated list of solid balance sheet and fundamentals (20 results) before more investors rotate toward stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com