
Firefly Aerospace (FLY) Lands Sweden Launch Deal, Is The Upside Already Priced In?
Firefly Aerospace (FLY) is back in focus after a new multi-launch agreement with SSC Space for two Alpha rocket missions from Sweden’s Esrange Space Center, targeting first liftoff no earlier than 2028.
Firefly Aerospace’s latest contract lands after a choppy run for the stock. The 1-day share price return of 7.10% and 7-day gain of 3.92% come after a 30-day share price return that declined 16.91% and a 1-year total shareholder return that fell 51.97%, suggesting short-term momentum has picked up while longer-term performance remains weak.
Scan beyond Firefly Aerospace and see which other space, defense, and high-capex contractors are showing similar contract momentum in our curated list of list of solid balance sheet and fundamentals (23 results).
The key issue now is valuation. After Firefly Aerospace’s sharp rebound following a still heavy 1-year decline, are investors looking at meaningful upside ahead, or has most of the easy rerating already been reflected in the price?
Most Popular Narrative: 44% Undervalued
Analysts following Firefly Aerospace see fair value at $38.60 compared with the last close of $21.72. As a result, the current narrative leans toward a sizable valuation gap that hinges on how long term contracts and margins play out.
A growing focus on national security space and missile defense, including the planned US$175b Golden Dome program, positions Firefly’s Alpha, Elytra and SciTec software to compete across launch, space interceptors and fire control, which can influence long term revenue visibility and backlog conversion.
See why 38 investors see Firefly Aerospace as 44% undervalued.
Result: Fair Value of $38.60 (UNDERVALUED)
Still, the Firefly Aerospace story hinges on shrinking heavy net losses and resolving recent Alpha reliability setbacks, which could unsettle customers and slow contract conversion.
Find out about the key risks to this Firefly Aerospace narrative.
Another View On Firefly Aerospace’s Price Tag
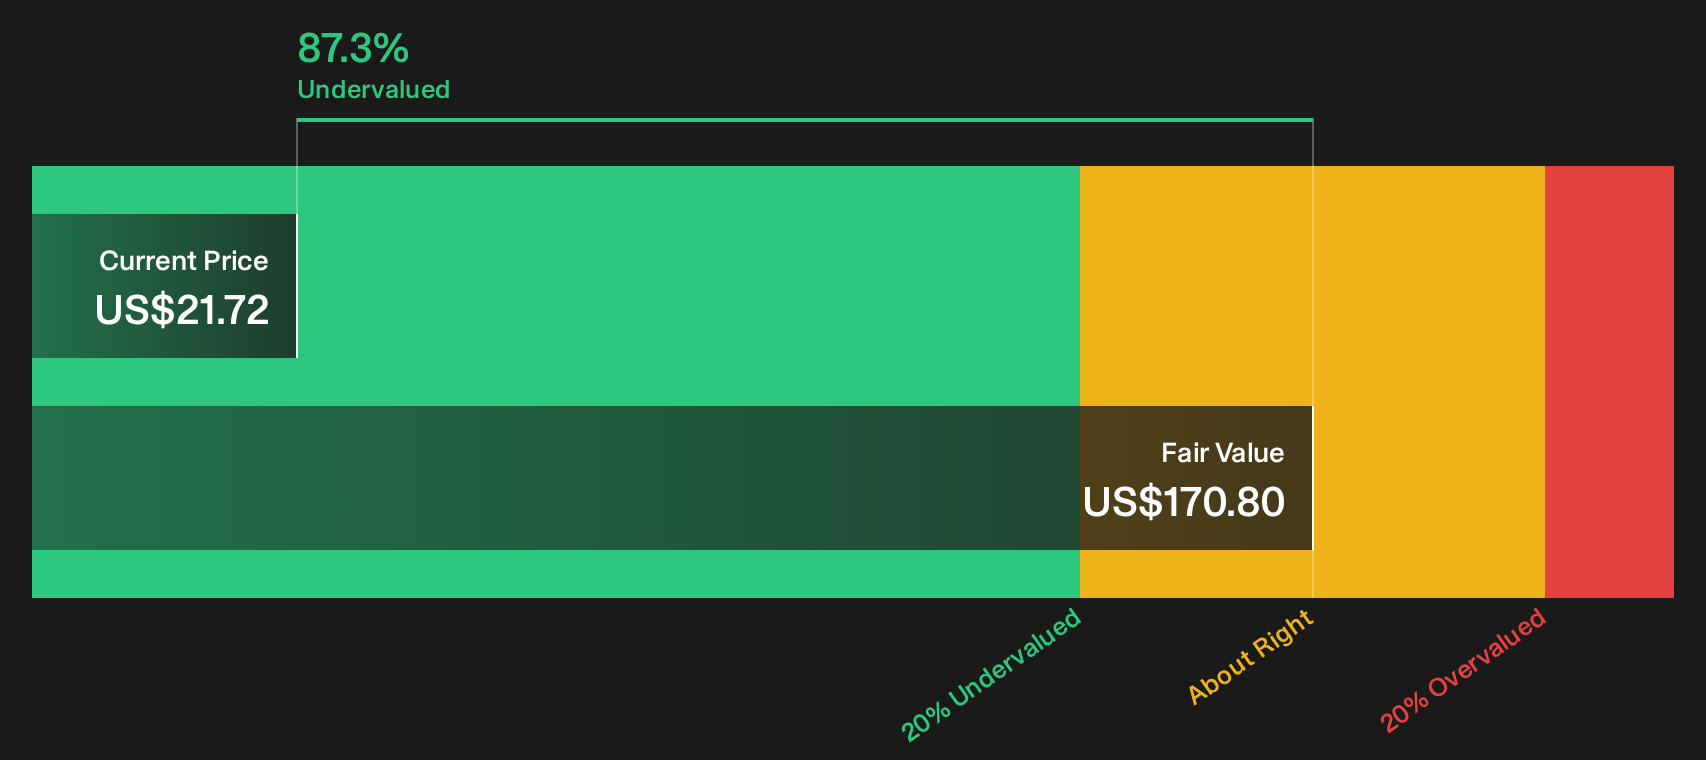
There is a sharp split in how Firefly Aerospace is priced. The SWS DCF model points to a future cash flow value of $170.80 per share, which is far above the recent $21.72 price and suggests a deep undervaluation within that framework.
That kind of gap can look tempting, yet it also raises a tougher question for you as an investor. Do you see Firefly eventually delivering the cash flows implied by such a large DCF upside, or do the ongoing losses and execution risks make this a case where the spreadsheet runs ahead of reality?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals around Firefly Aerospace’s valuation and risk profile mean sentiment is anything but settled, so move quickly, review the underlying data, and decide where you stand using the detailed breakdown of 3 key rewards and 2 important warning signs.
Looking for more Firefly Aerospace investment ideas?
If Firefly Aerospace has you rethinking your watchlist, use targeted screeners to surface other candidates so you are not relying on just one stock story.
- Target potential turnarounds by scanning 7 elite penny stocks with strong financials that couple small market values with stronger fundamentals than many investors expect.
- Focus on price versus quality by reviewing 29 high quality undervalued stocks where balance sheets and cash flows do more of the talking than headlines.
- Dial back portfolio stress by filtering for 30 resilient stocks with low risk scores that score well on resilience while still offering meaningful equity exposure.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com