
Is DPC Holdings (DPC) Undervalued After Refinancing Its Debt?
DPC Holdings (NYSE:DPC) has just overhauled its borrowing structure, securing a new US$325 million unsecured revolving credit facility and refinancing pre IPO debt. This move reshapes its liquidity profile.
Investors have reacted cautiously to these financing moves, with DPC Holdings’ 1 month share price return down 18.52% and the year to date share price return down 13.82%. This is despite a 2.23% gain over the last trading day, which hints at stabilising momentum.
Scan how lenders react to refinancing stories like DPC Holdings’ by comparing it with a curated 30 resilient stocks with low risk scores that have kept balance sheet risk in tighter control.
This refinancing either signals DPC Holdings quietly backing its long term operating plans with cleaner funding, or it simply marks sentiment resetting after the IPO. Which story does the current valuation support?
Most Popular Narrative: 33.5% Undervalued
DPC Holdings closed at $40.40 against a narrative fair value of $60.75, which sets up a valuation gap built on ambitious operating targets.
Vertical integration into superalloy production, including the planned greenfield facility in Alabama and continued capacity investments in the U.K., Germany, North America and Mexico, is intended to improve control over inputs and lead times. This can support gross margin resilience and help operating margins as utilization rises.
See why 3 investors see DPC Holdings as 33% undervalued.
Result: Fair Value of $60.75 (UNDERVALUED)
Still, the bullish DPC Holdings story can unravel if expected margin improvement or long term aerospace and IGT demand fail to materialise as analysts currently assume.
Find out about the key risks to this DPC Holdings narrative.
Another View on DPC Holdings’ Valuation
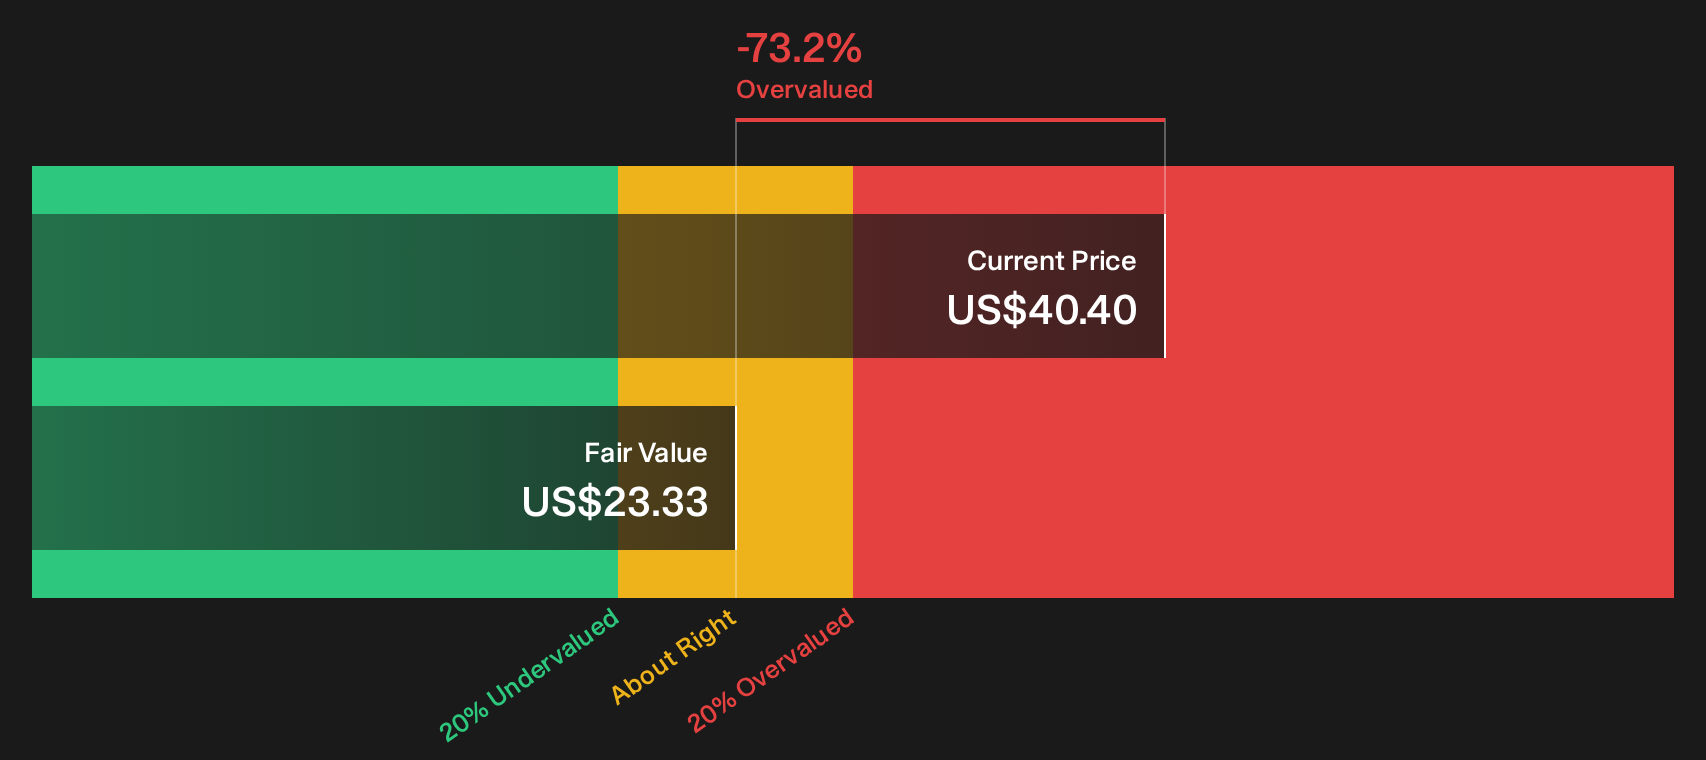
There is a catch. While the consensus narrative frames DPC Holdings as about 33.5% undervalued against a $60.75 fair value, the SWS DCF model points the other way and puts future cash flow value closer to $23.33 per share, which implies the stock screens as overvalued on that basis.
Both approaches lean on long term forecasts, but they stress different things: one on earnings multiples and the other on cash generation. Which lens do you trust more when the signals conflict this sharply?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If the split views on DPC Holdings leave you unsure, that is the point. Move quickly, review the numbers yourself, then weigh the 3 key rewards.
Looking for more DPC Holdings sized ideas?
Do not stop with DPC Holdings. Use the Simply Wall Street Screener to line up fresh opportunities before other investors start paying attention.
- Target resilient performers that prioritise capital strength with a list of solid balance sheet and fundamentals (23 results) built to handle tougher conditions.
- Spot potential mispricings early by checking the 29 high quality undervalued stocks that combine quality metrics with compressed valuations.
- Hunt for overlooked potential in a 16 high quality undiscovered gems that filters for strong fundamentals before the crowd catches on.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com