
Will President Resignation Change Pathward Financial's (CASH) Narrative
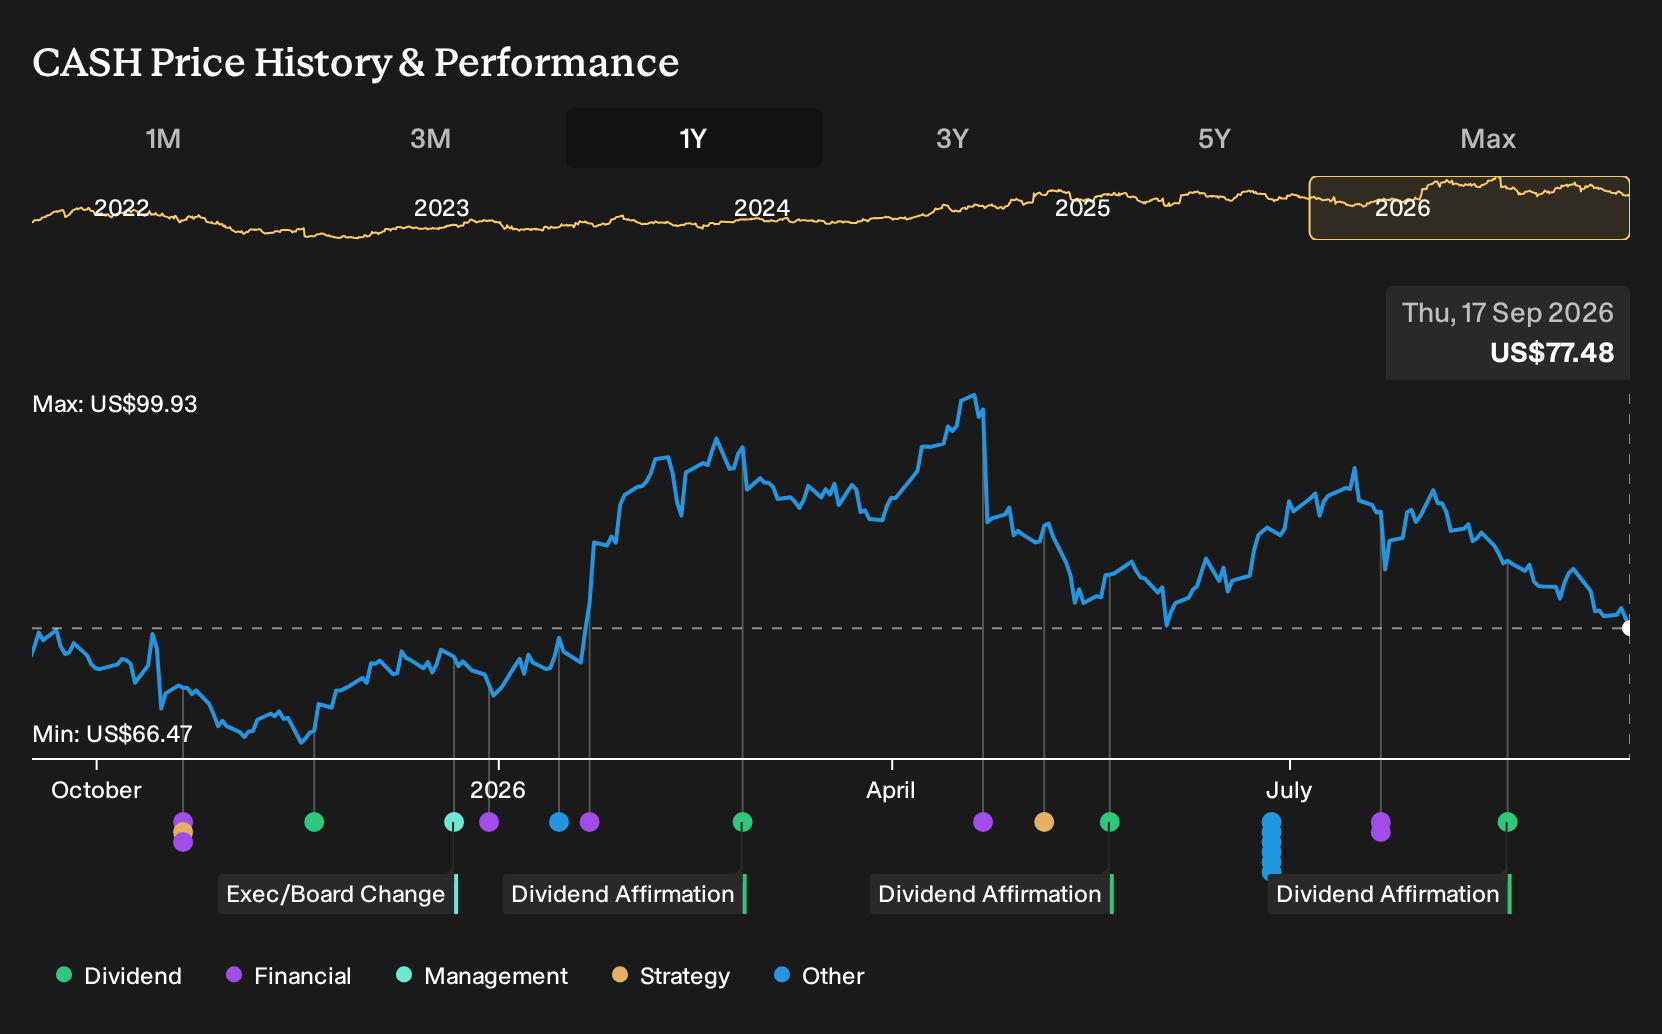
- Pathward Financial reported that President Anthony Sharett, who also led its Pathward, N.A. subsidiary and previously held senior legal and compliance roles, resigned effective October 23, 2026, to pursue other opportunities.
- His exit removes a long-tenured leader from the legal, compliance, and operating side of Pathward Financial at a time when the bank continues to balance regulatory demands, partner-driven growth, and complex accounting work.
- We will now look at how Pathward Financial's investment narrative could be affected by President Anthony Sharett's decision to step down.
Scan how other regulated financials are handling leadership turnover and compliance risk by reviewing the hand picked 30 resilient stocks with low risk scores, which may offer steadier governance profiles than Pathward Financial right now.
Pathward Financial Investment Narrative Recap
To own Pathward Financial, you need to believe its partner focused banking model can keep generating fee income while it works through accounting clean up, elevated compliance spend, and credit management in under served segments. The president's exit looks important for continuity, but on its own it does not reshape the near term thesis.
The near term swing factor still sits in completing the accounting restatement and related regulatory filings, which drive clarity on prior results and earnings power. The biggest risk remains prolonged high technology, legal, and compliance costs alongside exposure to higher bad loan levels, any of which could weigh on margins if they persist.
Recent commentary around Pathward Financial's accounting restatement is the clearest companion to this leadership change. The same legal and compliance expertise that supported that clean up now needs to be replicated or redistributed across the remaining team, so investors will likely watch for process updates and any shifts in timelines.
The restatement work ties directly into catalysts that investors care about, including clearer earnings quality, better visibility on noninterest income from partner programs, and more confident capital return decisions. Until that is resolved, leadership turnover simply adds another execution task on top of already high regulatory, technology, and credit monitoring demands.
What The Current Pathward Financial Forecasts Assume
Pathward Financial's narrative projects US$1.0b revenue and US$221.0m earnings by 2029. This rests on analysts using 10.9% yearly revenue growth and an earnings increase of about US$45m from US$175.6m today.
Discover why Pathward Financial's fair value suggests a 30% potential upside to its current price that may materialize sooner than you expect.
Exploring Other Perspectives
Three fair value views from the Simply Wall St Community cluster between US$101 and about US$196, so some retail investors see Pathward Financial as close to its base case while others price in far richer outcomes. When you set that against unresolved accounting restatement risk and execution demands around compliance, you can then compare these contrasting viewpoints yourself.
Explore 2 other Pathward Financial fair value estimates, including one that suggests potential upside of as much as 153% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Pathward Financial research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Pathward Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Pathward Financial's overall financial health at a glance.
Looking For More Investment Ideas Beyond Pathward Financial?
Once you are comfortable with the story around Pathward Financial, it can help to widen your watchlist and compare it with other businesses that have very different risk and return profiles.
- For income focused investing, scan companies with stronger yield support and payout histories through the 6 dividend fortresses.
- If capital preservation and balance sheet resilience matter most to you right now, filter for financially sturdy businesses using the list of solid balance sheet and fundamentals (23 results).
- When you want potential mispricings based on fundamentals, sort for opportunities trading below intrinsic estimates by running the 29 high quality undervalued stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com