
EnerSys (ENS) Could Be 29% Undervalued As Value Appeal Meets Recent Pullback
EnerSys (ENS) has drawn fresh attention after Zacks assigned the stock a Rank #2 rating and a Value grade of A, based on several valuation metrics versus its industry peers.
At around US$175.68 per share, EnerSys has pulled back with a 30 day share price return of down 12.4% and a 90 day share price return of down 22.9%. However, the year to date share price return of 16.6% sits alongside a 1 year total shareholder return of 58.7%, hinting that longer term momentum has cooled recently but remains strong on a multi year view.
Compare EnerSys with a curated set of industrial value opportunities by scanning the 29 high quality undervalued stocks that share similar valuation appeal and recent pullbacks.
EnerSys has given back a portion of its recent gains while still carrying a strong one-year track record and a value label. Are current fundamentals arguing for more upside ahead, or suggesting most of the easy money has already passed?
Most Popular Narrative: 29% Undervalued
On the most followed view, EnerSys trades below an implied fair value of $247.29, which leans heavily on data center and defense demand combined with margin expansion assumptions.
Ongoing recovery in U.S. communications and robust growth in Data Center deployments, both driven by upgrades to broadband and expansion of digital infrastructure, are expected to fuel accelerating demand for EnerSys' energy storage solutions and support multi-year revenue growth. EnerSys is embedding IoT and predictive analytics capabilities into its products, enabling cross-selling of higher-value services and energy management solutions, which is expected to expand the addressable market and support both top-line growth and margin improvement over time.
See why 30 investors see EnerSys as 29% undervalued.
Result: Fair Value of $247.29 (UNDERVALUED)
Still, the EnerSys story can weaken if tariff pressures persist and if acquisitions like Bren Tronics fail to translate into steady organic demand.
Find out about the key risks to this EnerSys narrative.
Another Take On EnerSys Valuation
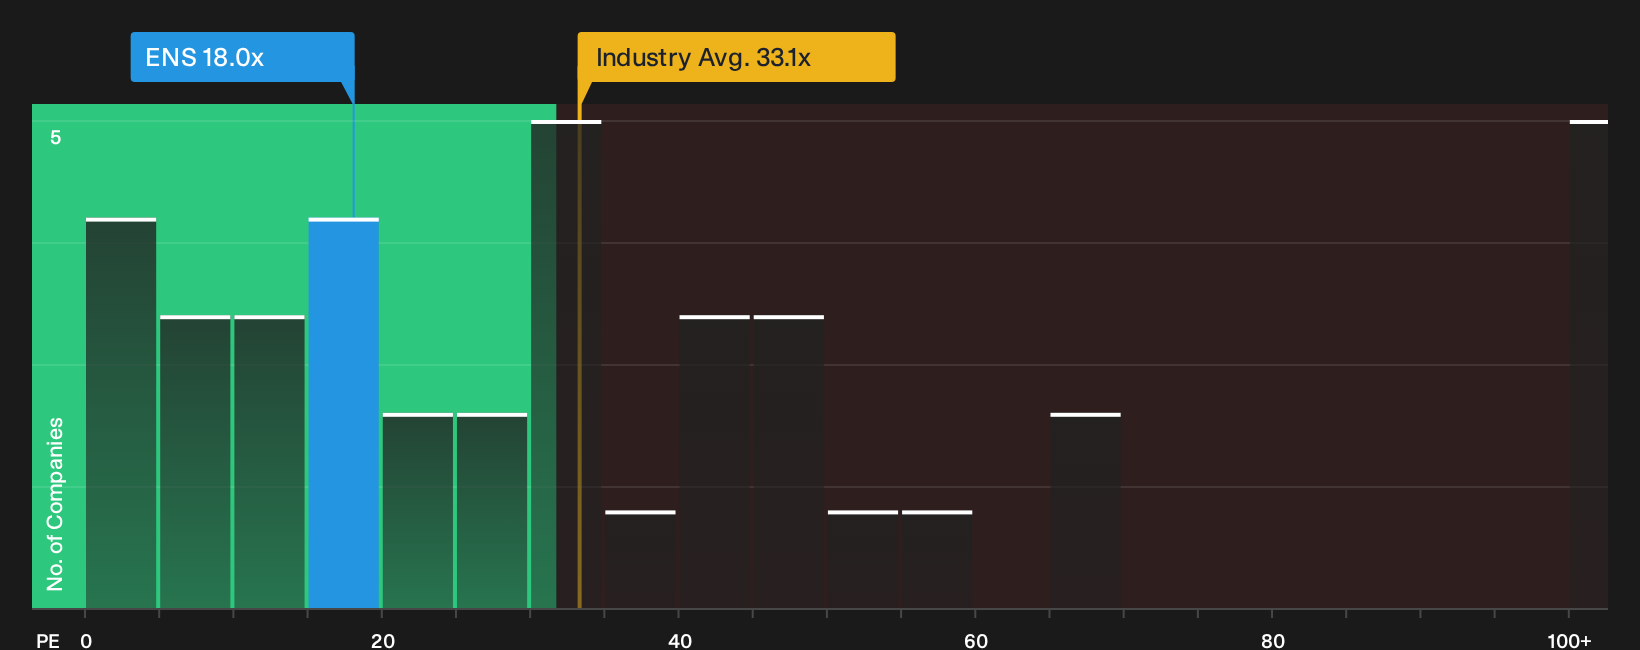
On price to earnings, EnerSys looks much cheaper than its sector. The shares trade at roughly 18x earnings, compared with about 33.2x for the wider US Electrical group and 47.4x for peers, while the fair ratio sits higher again at 24.1x.
That gap can point to room for a re rating if sentiment improves, or it can signal that the market is already baking in slower growth and execution risk. The key question for you is whether EnerSys has earned a discount or whether the market has pushed it too far.
See what the numbers say about this price — find out in our valuation breakdown.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out EnerSys for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment on EnerSys is split between value opportunity and execution risk, so move quickly to stress test the numbers and form your own stance using the 5 key rewards.
Looking for more EnerSys sized ideas?
Do not stop with EnerSys. Use the Simply Wall Street Screener to surface fresh opportunities before they move out of reach and leave you reacting late.
- Target higher income potential by reviewing companies in the 6 dividend fortresses that combine strong yields with staying power.
- Hunt for mispriced opportunities through the 16 high quality undiscovered gems that pair solid fundamentals with limited market attention.
- Reduce portfolio stress by focusing on the 30 resilient stocks with low risk scores that score well on resilience and balance sheet strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com