
Incyte (INCY) Looks Fully Valued As Ontario Backs MINJUVI Access
Incyte (INCY) is back on investor radar after Ontario agreed to fund MINJUVI for relapsed or refractory follicular lymphoma through its FAST Program, giving eligible patients earlier access to treatment.
The MINJUVI decision lands at a time when Incyte’s share price has already been gaining traction, with a 90-day share price return of 29.93% and a year-to-date share price return of 25.83%. This supports a strong 1-year total shareholder return of 48.40% and a 3-year total shareholder return of 117.00%, suggesting momentum has been building ahead of the latest news.
Scan beyond Incyte to identify other oncology and biotech players showing similar momentum with our hand-picked list of 16 high quality undiscovered gems
After a run like this, with Incyte now trading close to recent analyst targets and recent returns well ahead of the broader biotech space, does the risk reward still lean toward buyers, or has the easy part of the move passed?
Most Popular Narrative: Fairly Valued
Incyte’s most followed narrative pegs fair value at $127.74, almost exactly in line with the last close of $127.62, which leaves very little valuation gap and puts the emphasis firmly on execution and clinical delivery.
The upcoming launches and label expansions of therapies like Opzelura, povorcitinib, and Niktimvo in high value indications such as atopic dermatitis, vitiligo, hidradenitis suppurativa and GVHD, along with a late stage pipeline of targeted drugs, position Incyte to benefit from heightened demand for advanced immunology and oncology treatments as global populations age. This may support sustained revenue growth and future earnings. Recent advances in precision medicine, exemplified by the successful early clinical data for mutant CALR antibody 989 and Incyte's collaboration with QIAGEN for mutation specific diagnostics, are consistent with increasing industry use of targeted therapies. This trend may expand total addressable markets and affect the probability of commercial outcomes, which could influence future revenue and margin performance.
See why 52 investors see Incyte as 0% undervalued.
Result: Fair Value of $127.74 (ABOUT RIGHT)
Still, Incyte’s heavy reliance on Jakafi, along with the potential for pipeline setbacks or delayed data, could quickly challenge that fair value narrative.
Find out about the key risks to this Incyte narrative.
Another Angle On Incyte’s Valuation
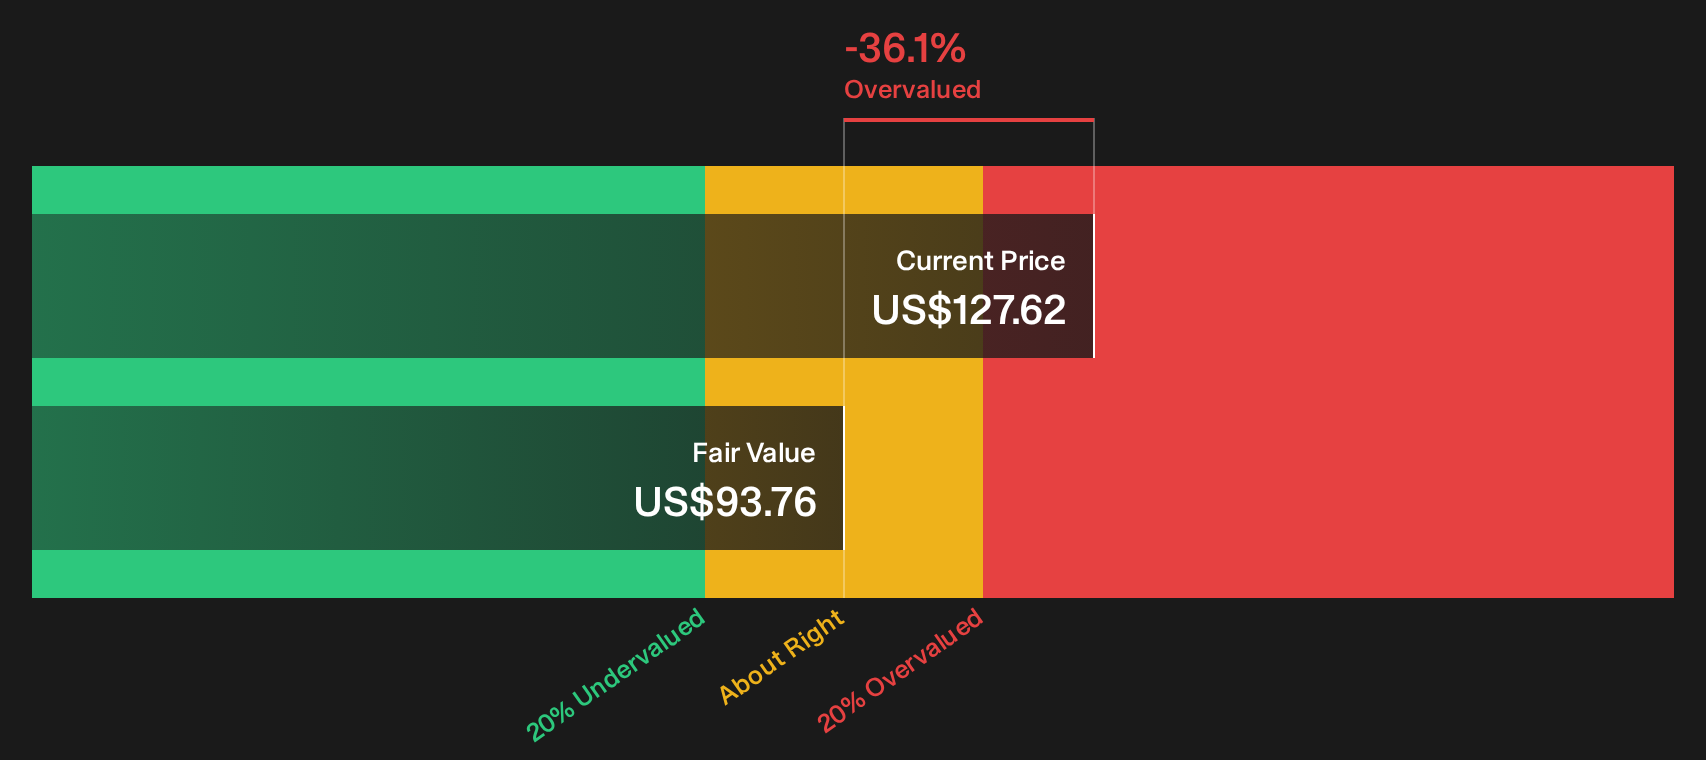
The story so far casts Incyte as roughly fairly priced around $127, with the market and analyst consensus largely aligned. A different tool tells a more cautious story. The SWS DCF model values Incyte’s future cash flows at $93.76 per share, which sits well below the current $127.62 quote.
This gap suggests investors today are paying a premium versus that cash flow view and leaning more on pipeline execution, momentum and sentiment rather than on a stricter cash flow outcome. The question is simple for anyone watching INCY: which lens matters more for the next leg of the story?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Incyte for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Given the mixed tone around Incyte, with enthusiasm about the pipeline set against valuation questions, it makes sense to move fast and check the underlying data for yourself. To balance the positive angles against the potential pressure points, start with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Incyte?
If you are serious about putting this research to work, do not stop at Incyte. Use focused stock lists to spot opportunities that fit your style.
- Target potential bargains by scanning companies that combine quality fundamentals with attractive pricing using our 29 high quality undervalued stocks.
- Prioritise resilience and capital preservation by checking out a curated 30 resilient stocks with low risk scores that screens for businesses with lower risk profiles.
- Zero in on financially robust operators by reviewing a list of solid balance sheet and fundamentals (23 results) that highlights companies with stronger balance sheets and fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com