
UK Penny Stocks To Watch In September 2026
The United Kingdom market has shown robust performance, climbing 1.8% in the last week and achieving a 17% increase over the past year, with earnings expected to grow by 11% annually. In such a thriving market, identifying stocks that combine affordability with growth potential is key, particularly when they exhibit strong financial health. Penny stocks—though an older term—remain relevant as they often represent smaller or newer companies that can offer unique investment opportunities when backed by solid fundamentals.
Here we highlight a subset of our preferred stocks from the screener.
James Halstead (AIM:JHD)
Simply Wall St Financial Health Rating: ★★★★★★
Overview: James Halstead plc is a company that manufactures and supplies flooring products for both commercial and domestic uses across the United Kingdom, Europe, Scandinavia, Australasia, Asia, and other international markets with a market cap of £526.34 million.
Operations: The company generates £259.07 million in revenue from its core activity of manufacturing and distributing flooring products.
Market Cap: £526.34M
James Halstead demonstrates financial stability with more cash than debt and operating cash flow significantly covering its debt. The company’s short-term assets exceed both short and long-term liabilities, indicating strong liquidity. While James Halstead's Return on Equity is high at 21.1%, earnings growth has been negative over the past year, contrasting with modest profit growth over five years. The dividend yield of 6.96% is not well covered by earnings, raising sustainability concerns. Despite a stable weekly volatility and no significant shareholder dilution recently, the management team's inexperience may pose challenges moving forward.
- Unlock comprehensive insights into our analysis of James Halstead stock in this financial health report.
- Explore James Halstead's analyst forecasts in our growth report.
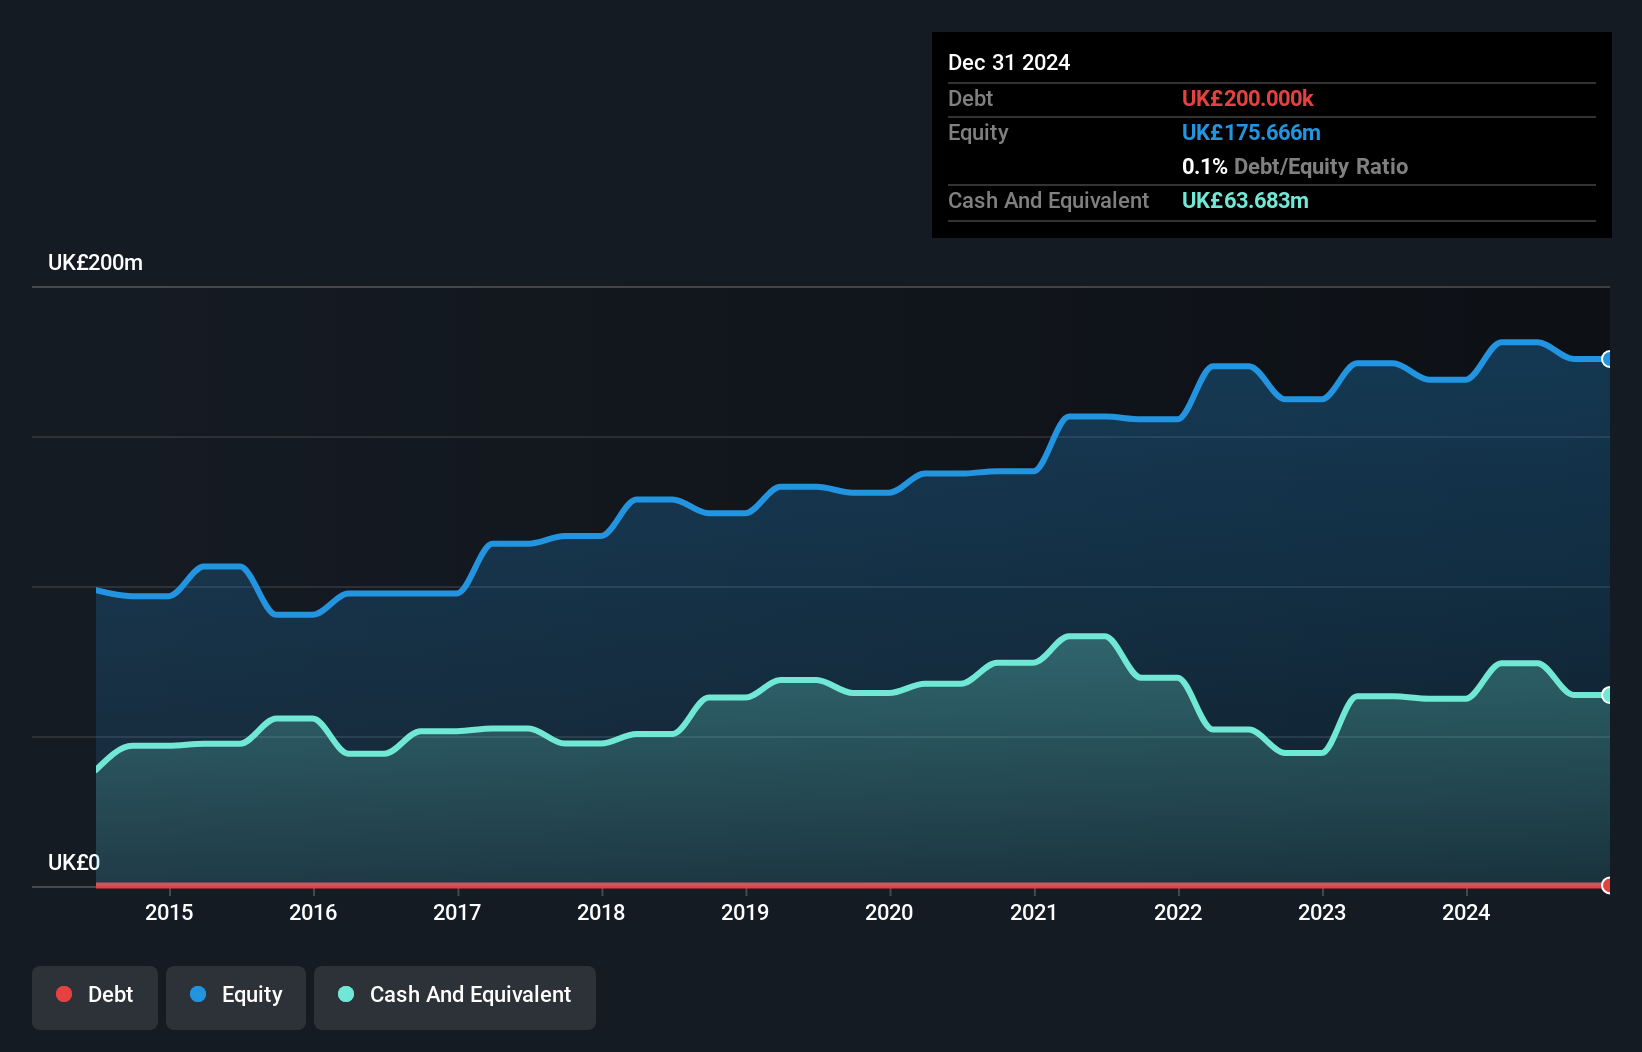
Card Factory (LSE:CARD)
Simply Wall St Financial Health Rating: ★★★★☆☆
Overview: Card Factory plc is a specialist retailer of cards, gifts, and celebration essentials operating in the United Kingdom, South Africa, Republic of Ireland, the United States, and internationally with a market cap of £236.58 million.
Operations: The company's revenue is primarily derived from Cardfactory Stores, which generated £514.6 million, followed by Wholesale Partnerships at £47.2 million and Digital sales amounting to £20.6 million.
Market Cap: £236.58M
Card Factory's financial profile shows a mixed picture for investors. The company trades at a good value compared to its estimated fair value and peers, with stable weekly volatility over the past year. Card Factory has grown profits significantly over the last five years, though recent earnings growth has been negative. Despite high-quality past earnings, its current profit margins have declined from 8.8% to 5.4%. While debt levels are satisfactory and well-covered by operating cash flow, short-term assets fall short of covering liabilities. Recent buyback transactions concluded in June 2026 may impact future financial flexibility and shareholder returns.
- Click here to discover the nuances of Card Factory with our detailed analytical financial health report.
- Review our growth performance report to gain insights into Card Factory's future.

PZ Cussons (LSE:PZC)
Simply Wall St Financial Health Rating: ★★★★☆☆
Overview: PZ Cussons plc is involved in the manufacturing, distribution, marketing, and sale of baby, beauty, and hygiene products across Europe, the Asia Pacific, the Americas, and Africa with a market cap of £409.53 million.
Operations: The company's revenue is derived from various regions: £168 million from Africa, £46.4 million from Central, £176.4 million from Asia Pacific, and £202.2 million from Europe & The Americas.
Market Cap: £409.53M
PZ Cussons presents a nuanced investment case among penny stocks. The company has recently turned profitable, reporting net income of £19.8 million for the year ended May 31, 2026, a significant improvement from a net loss previously. While its return on equity is low at 11.7%, debt levels are well-managed with operating cash flow covering 38.6% of debt and interest payments covered by EBIT at 6.6 times over. Despite short-term liabilities exceeding assets, long-term liabilities are comfortably covered by assets worth £231.3 million, and dividends have increased slightly to 3.70p per share for FY26, signaling financial stability amidst board changes.
- Navigate through the intricacies of PZ Cussons with our comprehensive balance sheet health report here.
- Learn about PZ Cussons' future growth trajectory here.

Summing It All Up
- Click here to access our complete index of 268 UK Penny Stocks.
- Want To Explore Some Alternatives? This technology could replace computers: discover the 25 stocks are working to make quantum computing a reality.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com