
CVB Financial (CVBF) Raises Its Dividend, Is The Stock Still Undervalued?
CVB Financial (CVBF) has kept its dividend story moving, with the board approving a US$0.20 per share cash payout for the third quarter of 2026 at its 16 September meeting.
Against this backdrop, CVB Financial shares trade at US$22.81, with the stock posting a 9.61% 90 day share price return and a 22.17% year to date share price gain. The 5 year total shareholder return of 43.31% points to longer term momentum that recent dividend news supports rather than creates.
Scan beyond CVB Financial and compare this dividend story against a curated 6 dividend fortresses that may reflect a similar income and consistency theme.
CVB Financial now combines a richer share price with a steady payout and double digit recent gains. Does that mix still leave enough upside in the current valuation to reward new buyers more than it exposes them to downside risk?
Most Popular Narrative: 9% Undervalued
CVB Financial is trading at $22.81 against a widely followed fair value estimate of about $25.17, which frames the dividend in the context of a stock that some models still see as underpriced on cash generation potential.
The company's disciplined expense control and operational efficiency through technology investment, branch optimization, and lease negotiations support industry-leading efficiency ratios and provide positive operating leverage even in periods of slow loan growth, benefiting net margins and long-term profitability.
See why 10 investors see CVB Financial as 9% undervalued.
Result: Fair value of $25.17 (UNDERVALUED)
Still, CVB Financial faces concentration in California and high commercial real estate exposure, which could pressure credit quality and challenge the current undervalued narrative.
Find out about the key risks to this CVB Financial narrative.
Another View On CVB Financial's Valuation
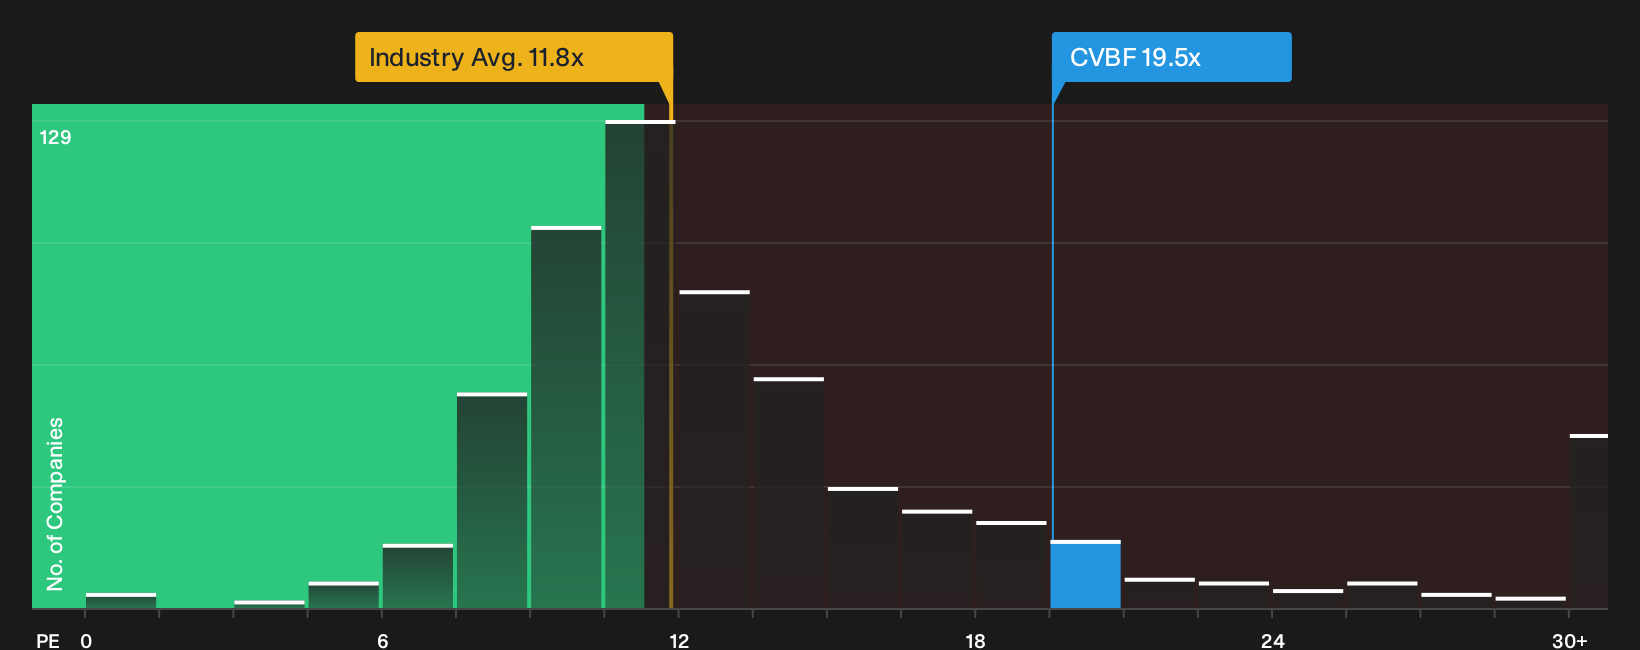
On cash flow, CVB Financial screens as roughly 14.5% below an estimated fair value, yet the P/E picture tells a different story. The shares trade on about 19.5x earnings, versus a fair ratio of 17.1x, the US Banks sector near 11.8x and peers around 11.7x. That richer multiple can signal investors are paying up for quality or simply overpaying, so which explanation fits your own thesis on CVBF?
To see how those earnings multiples line up against detailed valuation work, sense check this view against the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on CVB Financial's valuation and dividend story mean the data can point in more than one direction, so move quickly, test the assumptions that matter to you, and weigh both the upside case and the cautions highlighted by our breakdown of 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond CVB Financial?
If CVB Financial has sharpened your focus on income and valuation, use that momentum and scan for other opportunities before they move out of reach.
- Target resilient balance sheets by reviewing the list of solid balance sheet and fundamentals (23 results) and compare businesses that pair financial strength with steady fundamentals.
- Spot potential value gaps through the 29 high quality undervalued stocks and see which companies currently trade below their implied worth on key metrics.
- Build a broader income stream using the 6 dividend fortresses and line up alternatives that aim for strong yields with consistent payouts.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com