
3 Asian Growth Stocks With High Insider Ownership And 29% Revenue Growth
As Asian markets navigate a complex landscape shaped by geopolitical tensions and fluctuating oil prices, investors are increasingly focused on companies that demonstrate resilience and growth potential. In this environment, growth stocks with high insider ownership can offer unique insights into management's confidence in their business strategies, making them compelling considerations for those seeking robust investment opportunities.
Top 10 Growth Companies With High Insider Ownership In Asia
| Name | Insider Ownership | Earnings Growth |
| Suzhou Dongshan Precision Manufacturing (SZSE:002384) | 33.5% | 75.5% |
| SEERS (KOSDAQ:A458870) | 33.8% | 37.8% |
| Ningbo Sanxing Medical ElectricLtd (SHSE:601567) | 24.9% | 56.8% |
| Meiko Electronics (TSE:6787) | 19.2% | 33.8% |
| L&C BIOLTD (KOSDAQ:A290650) | 20.9% | 163% |
| Jiangxi Fushine Pharmaceutical (SZSE:300497) | 21.1% | 50.8% |
| Gold Circuit Electronics (TWSE:2368) | 29.8% | 43.6% |
| Fulin Precision (SZSE:300432) | 11.2% | 66.5% |
| Biocytogen Pharmaceuticals (Beijing) (SEHK:2315) | 14.1% | 39.2% |
| Beijing Luzhu Biotechnology (SEHK:2480) | 39.7% | 84.3% |
Here's a peek at a few of the choices from the screener.
Leader Harmonious Drive Systems (SHSE:688017)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Leader Harmonious Drive Systems Co., Ltd. operates in the precision drive systems industry and has a market cap of approximately CN¥53.28 billion.
Operations: Leader Harmonious Drive Systems Co., Ltd. generates revenue from its precision drive systems business, contributing significantly to its market presence.
Insider Ownership: 38.1%
Revenue Growth Forecast: 29.8% p.a.
Leader Harmonious Drive Systems has demonstrated robust growth, with half-year sales and revenue increasing to CNY 345.87 million and CNY 348.55 million, respectively. Earnings are expected to grow significantly at 28.5% annually, outpacing the Chinese market. Despite a volatile share price recently and a forecasted low return on equity of 8.9%, its high insider ownership aligns with strong revenue growth projections of 29.8% per year above market averages.
- Click here and access our complete growth analysis report to understand the dynamics of Leader Harmonious Drive Systems.
- According our valuation report, there's an indication that Leader Harmonious Drive Systems' share price might be on the expensive side.

Wuxi Chipown Micro-electronics (SHSE:688508)
Simply Wall St Growth Rating: ★★★★☆☆
Overview: Wuxi Chipown Micro-electronics Limited focuses on the research, development, and sale of semiconductor products in China and has a market cap of approximately CN¥11.80 billion.
Operations: The company generates revenue primarily from its Integrated Circuit segment, amounting to CN¥1.17 billion.
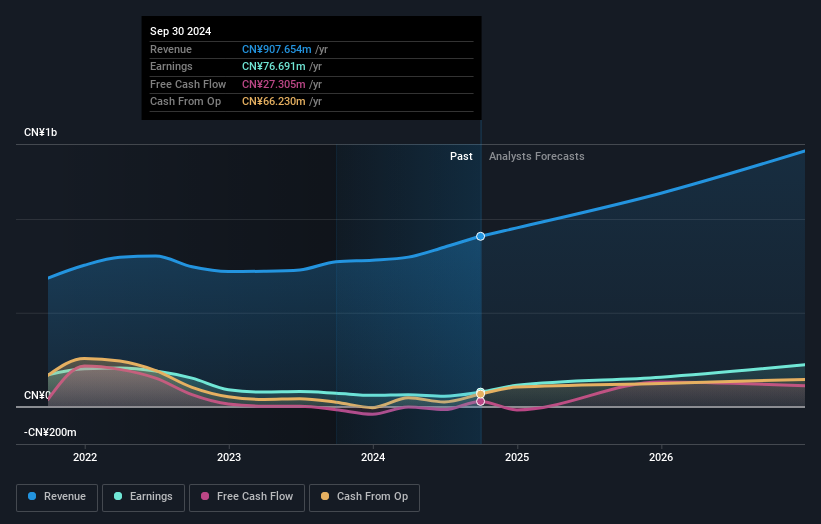
Insider Ownership: 31.5%
Revenue Growth Forecast: 20.3% p.a.
Wuxi Chipown Micro-electronics reported a rise in half-year sales and revenue to CNY 663.75 million and CNY 665.11 million, respectively, with net income jumping to CNY 157.57 million. Earnings are projected to grow significantly at 22.4% annually, although below the market rate of 27.2%. The price-to-earnings ratio of 46.6x is attractive compared to industry peers despite share price volatility and a low forecasted return on equity of 11.2%.
- Click here to discover the nuances of Wuxi Chipown Micro-electronics with our detailed analytical future growth report.
- Our expertly prepared valuation report Wuxi Chipown Micro-electronics implies its share price may be too high.
Ingenic Semiconductor (SZSE:300223)
Simply Wall St Growth Rating: ★★★★★☆
Overview: Ingenic Semiconductor Co., Ltd. designs, develops, and sells system-on-a-chip (SoC) products for various electronic devices globally, with a market capitalization of approximately CN¥67.91 billion.
Operations: Ingenic Semiconductor's revenue primarily stems from the design, development, and sale of system-on-a-chip (SoC) products for diverse electronic devices worldwide.
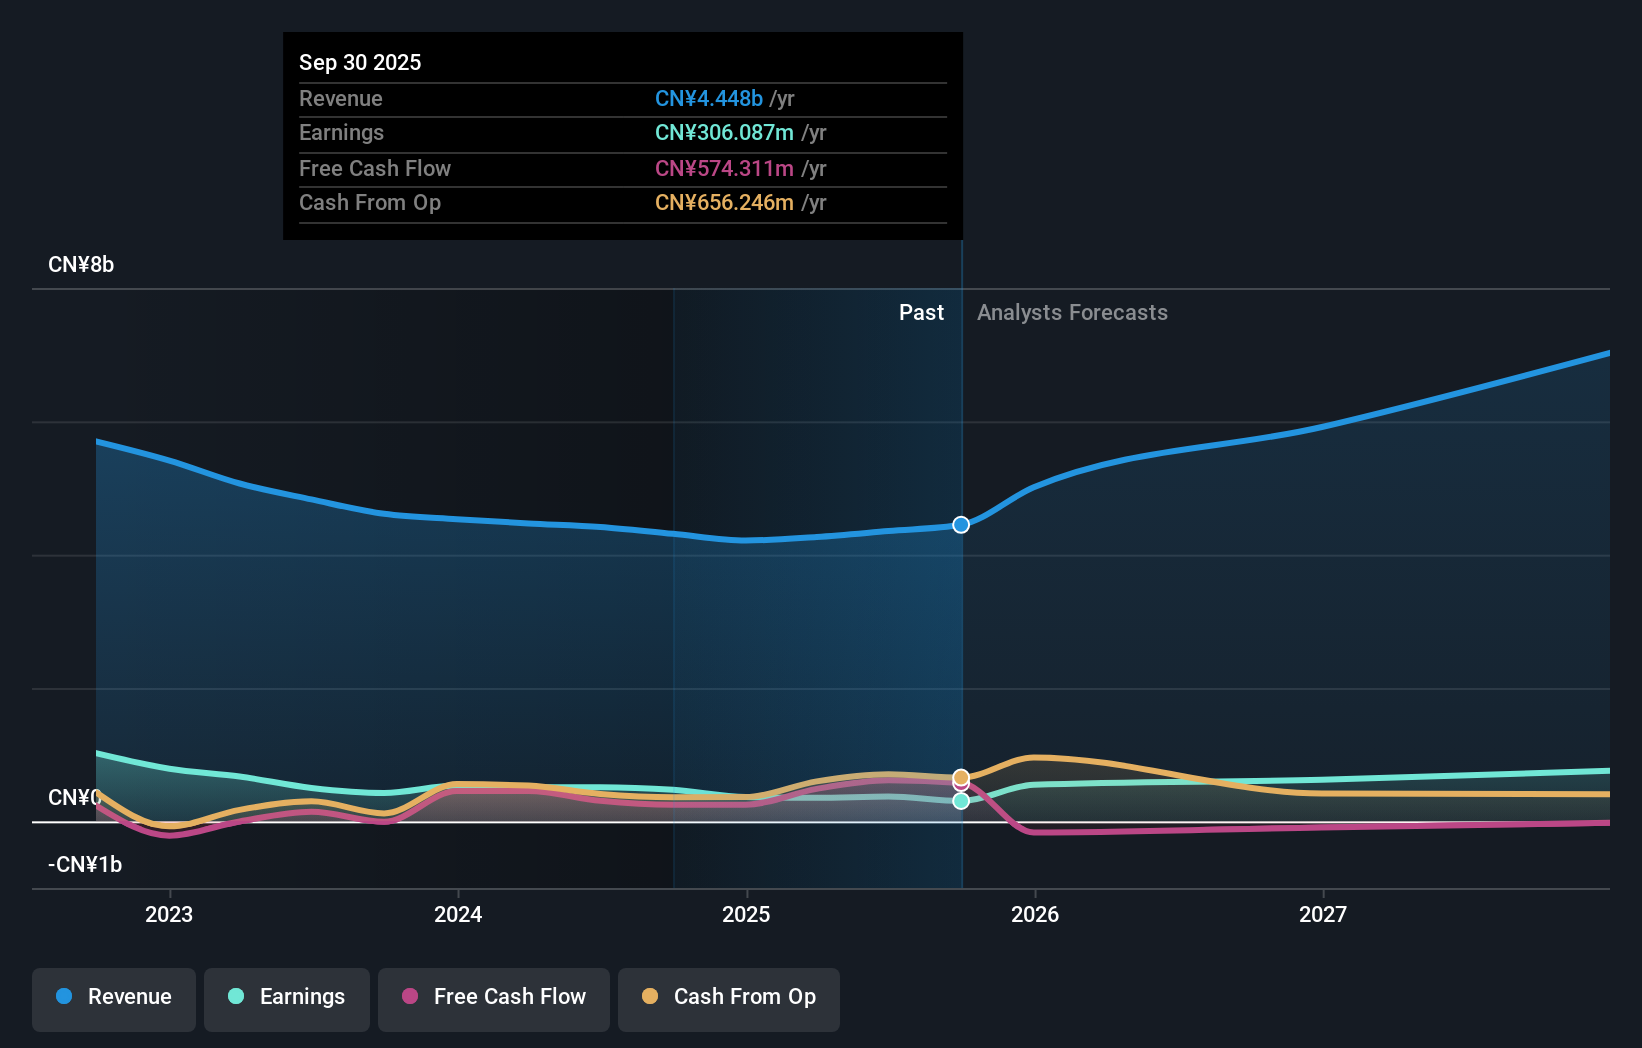
Insider Ownership: 16.1%
Revenue Growth Forecast: 29.6% p.a.
Ingenic Semiconductor's revenue for the first half of 2026 surged to CNY 3.96 billion, with net income reaching CNY 1.20 billion, reflecting substantial growth from the previous year. The company's earnings are expected to grow significantly at an annual rate of 31.7%, outpacing the market average. Despite a volatile share price, Ingenic offers good relative value with a price-to-earnings ratio of 50.7x, below the industry average, and has initiated a share repurchase program worth CNY 200 million.
- Unlock comprehensive insights into our analysis of Ingenic Semiconductor stock in this growth report.
- Insights from our recent valuation report point to the potential undervaluation of Ingenic Semiconductor shares in the market.
Summing It All Up
- Click this link to deep-dive into the 496 companies within our Fast Growing Asian Companies With High Insider Ownership screener.
- Ready For A Different Approach? Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.The analysis only considers stock directly held by insiders. It does not include indirectly owned stock through other vehicles such as corporate and/or trust entities. All forecast revenue and earnings growth rates quoted are in terms of annualised (per annum) growth rates over 1-3 years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com