
Group 1 Automotive (GPI) Stock Looks Reasonable On $1.25B Notes Deal
Group 1 Automotive shares have dropped sharply over the past year, which puts a fresh spotlight on a simple question for investors. Is the current US$254.95 price tag still in line with what the retailer actually earns?
- The stock has fallen 44.3% over the past year, which raises the question of whether the recent share price reset now better matches the company’s earnings power.
- Freshly priced senior notes of US$1.25b to help fund the Hennessy acquisition may reshape future interest costs and cash generation, which can change how you weigh Group 1 Automotive’s earnings against its market value.
- Your read on Group 1 Automotive is one view; the desks covering it have another. See what analysts think Group 1 Automotive's shares could be worth.
The issue now is whether Group 1 Automotive’s current share price is properly supported by its earnings profile when judged against the Fair Ratio benchmark.
If you want to cross check Group 1 Automotive against a wider field of value ideas, a focused stock screen built around 29 high quality undervalued stocks can be a useful next step.
Is Group 1 Automotive Still Cheap on Earnings?
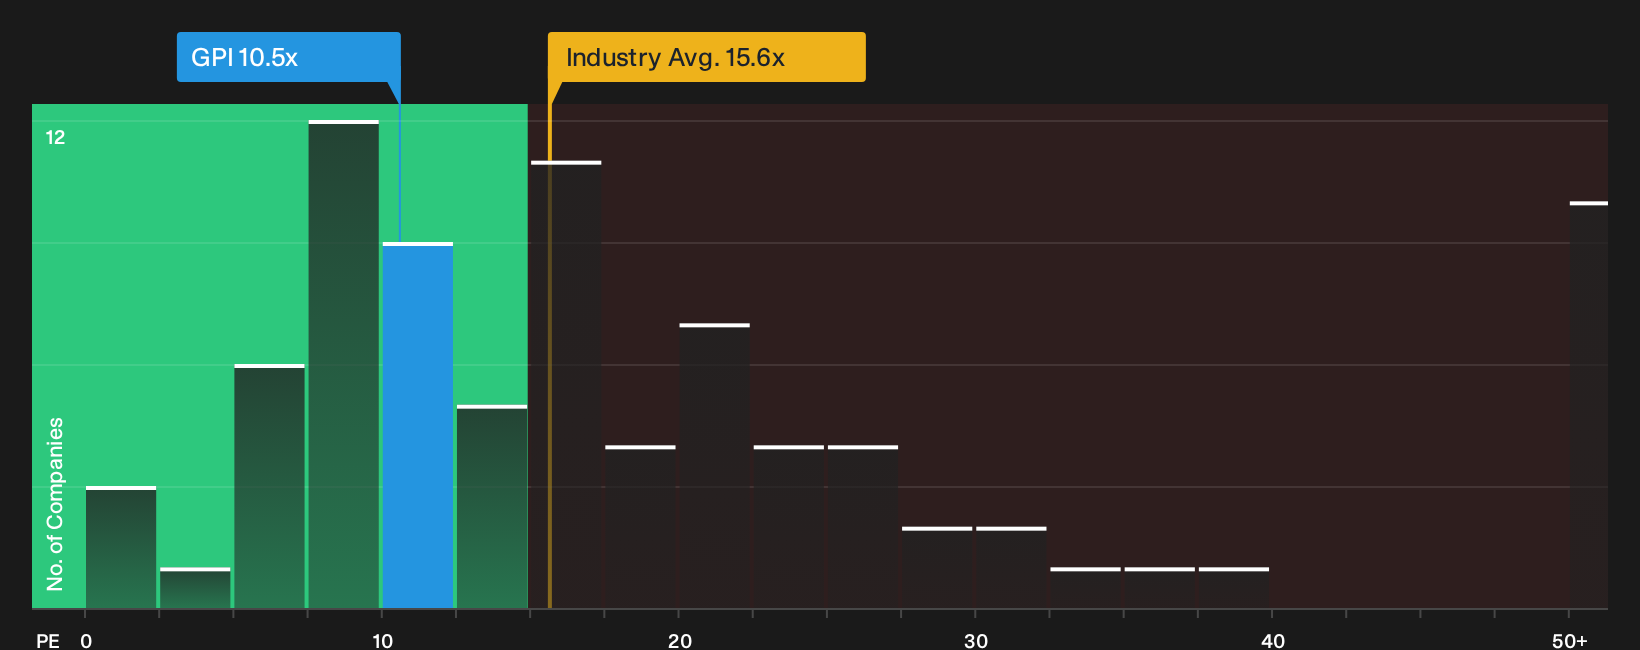
The P/E ratio works well for Group 1 Automotive because earnings are a central driver of how investors judge car retailers. At around 10.5x earnings, the stock trades at a marked discount to the Specialty Retail industry average of about 15.6x and a wider peer group closer to 18.3x. That kind of gap suggests the market is asking you to price in extra risk or more muted expectations for the business than for its sector overall.
Because the Fair Ratio framework blends factors like profitability, scale and sector traits into a tailored benchmark, it points to a higher P/E than where Group 1 Automotive changes hands today, which screens as undervalued on this lens. Despite the recent US$1.25b senior notes issuance to help finance the Hennessy acquisition, the earnings multiple still reflects a discount to both the industry and peer averages, so you would need to weigh whether those risks and financing costs fully explain the gap or leave room for mispricing. Explore the numbers behind Group 1 Automotive's P/E valuation.
The Group 1 Automotive Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the valuation puzzle around Group 1 Automotive leaves off by spelling out what would need to happen to future growth, margins and earnings for the shares to look meaningfully higher or lower than today’s price. Each scenario ties a fair value estimate to a particular mix of possible catalysts and risks for Group 1 Automotive’s business, so you can later judge which storyline is closest to reality. Narratives sit on Simply Wall St’s Community page as a way to keep those competing explanations in one place.
One of the top community narratives on Group 1 Automotive: 31% undervalued
"Growth in aftersales and used vehicle sales, supported by investments in service, technology, and customer outreach, drives recurring revenue and margin resilience..."
Discover why this Narrative puts Group 1 Automotive at 31% undervalued.
Before you act on Group 1 Automotive’s valuation, there is one more piece to check
Price ratios and community storylines only tell part of the Group 1 Automotive picture. Internal health checks have flagged specific areas of concern that deserve your attention before you commit. Take a closer look at 3 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com