
Is Oklo (OKLO) Trading At A Premium After Its $1B Offering?
Oklo has delivered very large 5 year share returns, yet the current price near US$39.65 now sits against a fresh equity offering and raises a sharper question about what investors are actually paying for on its balance sheet. With that kind of run in the rear-view and a new wave of stock issuance on the table, the issue is whether Oklo's book value can still anchor the story.
- Oklo's share price has climbed about 303% over the past 5 years, which puts a lot of accumulated optimism on the line when you compare the current valuation to what the company's net assets support.
- The new at the market stock program of up to US$1b, on top of a similar sized offering earlier this year, can reshape the share count and may alter how you think about the relationship between Oklo's equity base and its market price.
- There is a second opinion on Oklo worth weighing. See what analysts think Oklo's shares could be worth.
The stock's next move may depend on whether Oklo's current market value lines up with what its book value can justify today.
If you want to pressure test this same book value question across a wider set of nuclear related infrastructure ideas, start by scanning the 19 nuclear energy infrastructure stocks.
Is Oklo Getting Expensive on Book Value?
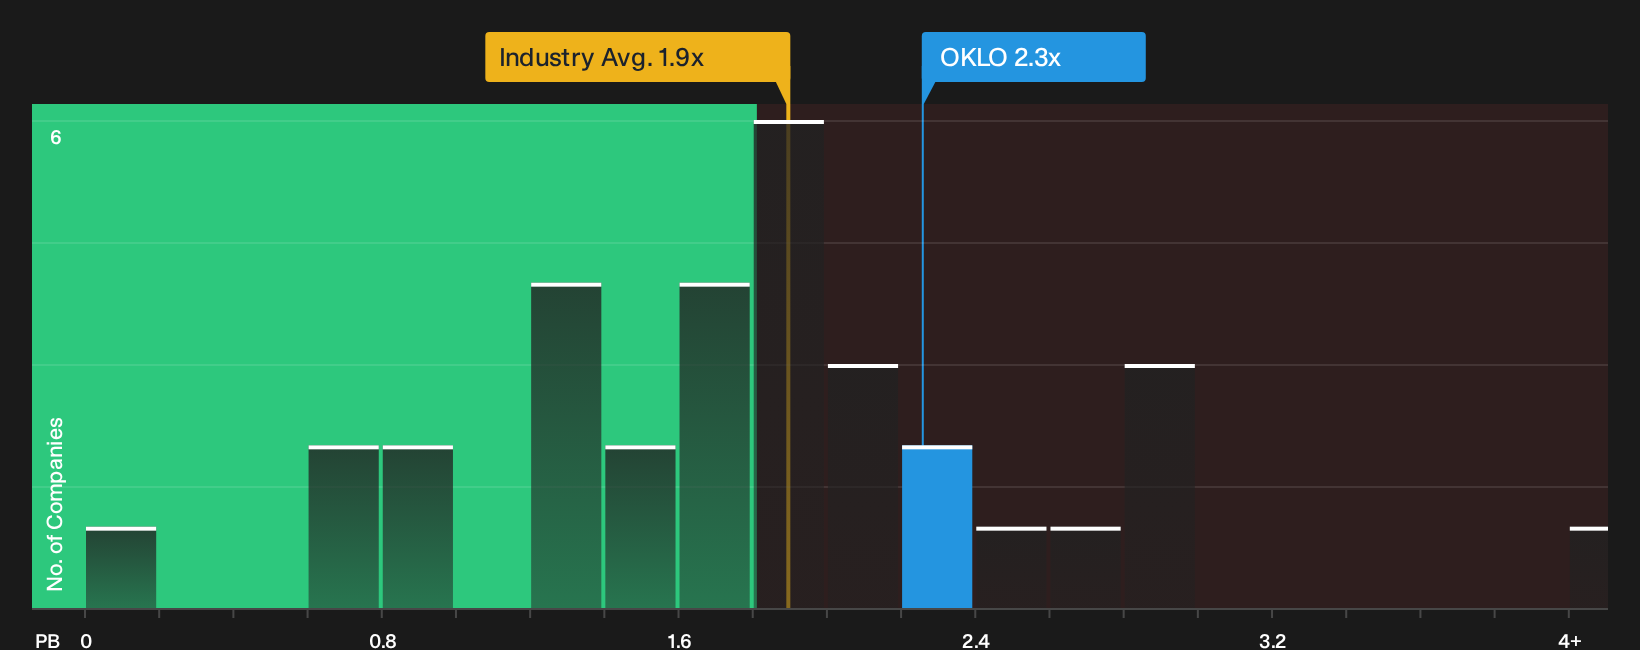
P/B matters most for Oklo because the story is still about how much you are paying for the balance sheet rather than for mature earnings power. On this measure, the stock trades on roughly 2.3x book value, compared with about 1.9x for the broader Electric Utilities industry and around 1.8x for close peers.
That premium indicates that investors are paying more for each dollar of Oklo's equity than for the typical utility, even as the fresh US$1b at-the-market program raises questions about future dilution. Because the multiple already sits above sector and peer averages, the shares appear overvalued on this P/B lens, so you would need to be comfortable that Oklo's assets and future project pipeline justify that richer price tag. Explore the numbers behind Oklo's P/B valuation.
The Oklo Narrative: What Would Justify Today's Price?
Oklo's valuation puzzle sets up Simply Wall St Narratives as the next step, since these scenarios spell out which paths for future growth, profitability and earnings would need to play out for the stock to be worth materially more or less than today’s price. Each one links its number to a specific view on how Oklo's expansion, unit economics and risk profile might evolve, so you can return to that thesis when new information arrives on the Community page.
The Simply Wall St community splits sharply on Oklo, with one camp seeing a high potential runway and the other focused on execution and funding risk.
Bull case: 51% undervalued
"Oklo has already signed major agreements, e.g. with Switch for 12 GW through to 2044, and has reached partnerships with large players, including NVDA and META..."
Discover why this Narrative puts Oklo at 51% undervalued.
Bear case: 51% overvalued
"Oklo is building three interconnected business units at the same time, and if execution bandwidth proves insufficient, projects may slip or be reprioritized..."
Explore why this Narrative puts Oklo at 51% overvalued.
Before you make a call on Oklo, there is one more piece to check
There is a separate lens investors often use here, which is how professional analysts currently map out Oklo's revenue, margins and cash flows a few years from now, and how that picture lines up with today’s price. Explore where analysts expect Oklo to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com