
LGI Homes (LGIH) Stock May Be Undervalued As Guidance Rises Again
LGI Homes has seen its share price fall 67.0% over the past 5 years, which raises a straightforward question for anyone tracking the builder today. Is the current US$49.13 price properly reflecting what the business is earning?
- A 67.0% decline over 5 years puts past shareholders under pressure and makes the link between LGI Homes' earnings power and its current valuation especially important.
- Management has recently raised its full-year expectations and pointed to firmer homebuilding gross margins and higher average selling prices, which can shift how much investors are willing to pay for each dollar of profit.
- Your read on LGI Homes is one view; the desks covering it have another. See what analysts think LGI Homes's shares could be worth.
The issue now is whether LGI Homes' recent share price, after a 17.8% gain year to date but a 14.9% decline over the past year, is adequately backed by its earnings.
If you are weighing whether LGI Homes’ current earnings justify the share price, you may want a broader yardstick by scanning 29 high quality undervalued stocks as another starting point for research.
Is LGI Homes a Bargain on Earnings?
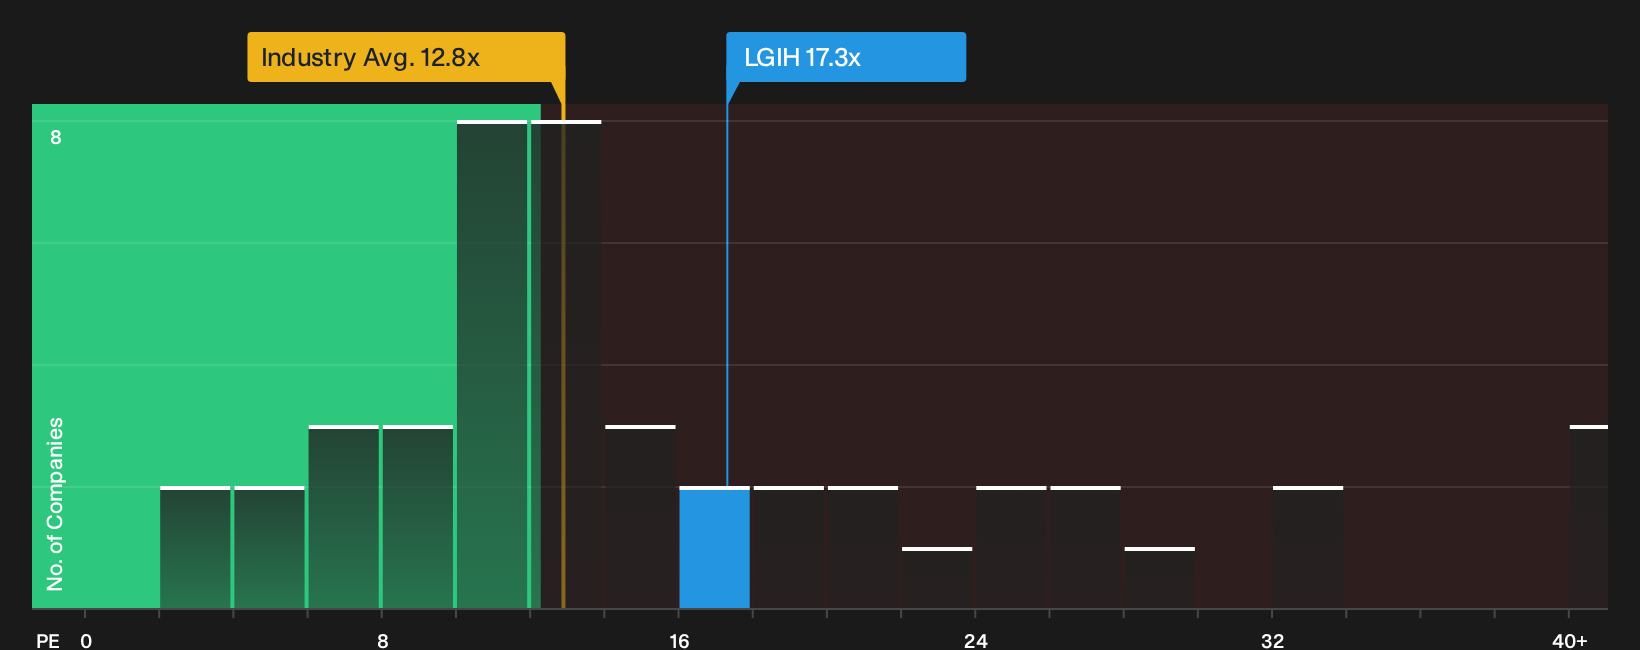
The P/E ratio is a useful way to gauge what investors are currently willing to pay for each dollar of LGI Homes’ earnings. At roughly 17.3x, the stock trades below the broader Consumer Durables sector average of about 12.8x and also sits well under the peer group on roughly 34.1x, which indicates the shares are not priced like the higher multiple builders in the space.
On a more tailored view that blends LGI Homes’ growth profile, profitability, size and risk into a single benchmark, the current P/E comes in below what that framework would suggest as a fair level, so the stock screens as undervalued on this measure. Because management has raised full year guidance and highlighted firmer homebuilding margins, the lower multiple versus that customised yardstick points to investor caution that has not fully faded yet. Explore the numbers behind LGI Homes's P/E valuation.
The LGI Homes Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St give you a way to connect LGI Homes' current P/E puzzle to clear future scenarios by spelling out which paths for growth, margins and earnings would leave the stock looking meaningfully richer or cheaper than today on the Community page. Each narrative relies on its own set of fair value assumptions instead of a single headline multiple, so you can line those inputs up against LGI Homes' actual results as they are reported.
The community is split, with one side seeing LGI Homes as held back by sentiment and the other arguing expectations have already run too hot.
Bull case: 47% undervalued
"LGI's focus on streamlining operations and lowering costs, including more efficient advertising, tighter inventory management, and increased utilization of self-developed lots, positions the company to sustain or even expand net margins..."
Discover why this Narrative puts LGI Homes at 47% undervalued.
Bear case: 20% overvalued
"Persistently high mortgage rates and ongoing affordability challenges are likely to permanently shrink the pool of eligible first-time homebuyers, with management openly acknowledging that their core customer is under severe strain..."
Explore why this Narrative puts LGI Homes at 20% overvalued.
One more LGI Homes angle worth checking
Everything so far has focused on what LGI Homes looks like today, yet professional analysts have mapped out where they expect the business to be several years from now. This gives you another benchmark to weigh against the current valuation. Explore where analysts expect LGI Homes to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com