
A Perspective on the Long-term Value of Kangchen Pharmaceutical (01681): Nephrology Leaders Continue to Lead, Diversified Innovation Builds a Strong Growth Platform
Since 2026, the Hong Kong stock pharmaceutical sector has continued to fluctuate and adjust the pattern, and assets with deterministic profit and dividend capacity have been increasingly favored by the market. As a leading company in the field of nephrology in China, Kangchen Pharmaceutical (01681) continues to send a positive signal of long-term development to the market with a “combo punch” of high dividends and share repurchases against the backdrop of double-digit growth in its own performance and significant undervaluation in valuation.
According to the interim financial report, Kangchen Pharmaceutical achieved revenue of 1,785 billion yuan (RMB, same below) in the first half of the year, up 13.8% year on year; net profit to mother of 595 million yuan, up 19.5% year on year; net operating cash flow reached 781 million yuan, up 58.6% year on year, with solid profit quality.
The Zhitong Finance App observed that the company's profit growth rate outperformed the revenue growth rate during the period, which is particularly rare in the context of an industry under overall pressure. During the period, the company's gross profit reached 1,452 billion yuan, a year-on-year increase of 20.1%; gross margin jumped to 81.4% from 77.1% in the same period last year. The improvement in gross margin comes from the optimization of supply chain management, the improvement in production and operation efficiency, and the decline in procurement prices for core raw materials. At the same time as revenue is growing, the company's ability to control costs is simultaneously increasing, and scale effects are continuously being unleashed.
Comparing Hong Kong stocks and major listed companies in the A-share Chinese medicine industry horizontally, Kangchen Pharmaceutical's growth is particularly remarkable. Against the backdrop of the overall pressure on the Chinese medicine sector of Hong Kong stocks and the decline in revenue and profits of many leading companies, Kangchen Pharmaceutical became a rare “double growth” target in the industry with a revenue growth rate of 13.8% and profit growth of 19.5%. What is more noteworthy is that Kangchen Pharmaceutical's gross sales margin and net margin levels are significantly higher than the industry average, further highlighting the industry-leading edge in profitability.
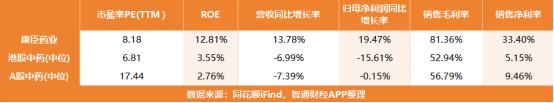
Based on good fundamentals and abundant cash flow, Conson Pharmaceutical continued to pay a high dividend of HK$0.38 per share in the medium term, fully demonstrating its confidence in future development.
What is more noteworthy is that the company issued a voluntary announcement on May 27, stating that no more than HK$200 million of shares will be repurchased by December 31, 2026. After the announcement of the interim results, the company has repurchased a total of 1.255 million shares as of September 17, further demonstrating the management's high recognition of the company's intrinsic value and sufficient motivation for future growth.
By business segment, nephrology products achieved sales of 1,335 billion yuan in the first half of the year, an increase of 18.1% over the previous year, and continued to maintain a leading position in the market. The core variety, uretoxin granules, is the first modern proprietary Chinese medicine for nephropathy in China through evidence-based medical research. It has been at the top of the market for many years in a row. The clinical efficacy is accurate, and it continues to lead the market.
Looking at the market space, the number of CKD stage 3-4 patients in China exceeds 20 million, and uremic toxin granules still have a huge market penetration space. At the performance conference, the company explained that since the collection and implementation in 2023, the amount of uremic clear granules has continued to be released.
In addition to the basic market of nephrology, various business segments are also contributing to the increase. The revenue of women's and children's medicines in the first half of the year was 187 million yuan, an increase of 9.1% over the previous year. The core product Yuanlikang® Iron Dextran Oral Solution was the only oral iron supplement to enter the national basic drug catalogue and medical insurance catalogue, and its market share increased steadily. Hepatobiliary products showed an explosive growth trend, with revenue surging 233.7% year-on-year in the first half of the year. In terms of medical imaging contrast agents, glutamine gadolate injections were approved for marketing in August. Octafluoropropane liposome microspheres and gadocerate disodium injections are expected to be launched in the next six months.
If the results in the first half of the year reflect the company's current operating strength, then a series of strategic layouts point to a longer term future. During the year, Kangchen Pharmaceutical promoted simultaneously in the three dimensions of industrial chain extension, overseas expansion, and innovative research and development, building a competitive moat.
In terms of industrial chain layout, the company strategically invested 191 million yuan in Shanghai Huamao Pharmaceutical in June, holding 30% of its shares. Shanghai Huamao has accumulated deep technology in the R&D and production of synthetic biology, precision fermentation, and dialysis APIs. It is highly compatible with the company's core businesses such as nephrology, obstetrics and gynecology, etc., which will help the company reduce supply chain costs and ensure the stability of the supply of core raw materials. This idea of controlling key points in the industrial chain from the source is clearly strategically forward-looking at a time when supply chain fluctuations in the pharmaceutical industry are intensifying.
In overseas markets, the company is steadily advancing its product development strategy, laying the foundation for subsequent global expansion. Among them, uremia granules have launched modern botanical drug registration in Indonesia, Vietnam, and Thailand. They have now successfully entered the Indonesian market and entered the local academic stage. They have also completed the first round of traditional Chinese medicine submissions in Canada. Yulin Pharmaceutical's products also continue to focus on key markets in Southeast Asia and implement the “one country, one policy” promotion.
On the innovative R&D side, the company has taken a firm step, and the R&D model has evolved towards “innovation at the source”. In the first half of the year, Kangchen Pharmaceutical invested about 98.23 million yuan in R&D, a significant increase over the previous year. In terms of research and pipeline, Qijian Granules, a Class 1.1 innovative traditional Chinese medicine drug for the treatment of diabetic nephropathy, officially obtained clinical trial approval from the State Drug Administration in August; another Baihua Zilian granule for the treatment of lupus nephritis is scheduled to be submitted for IND in the second quarter of 2027.
At the capital market level, Kangchen Pharmaceutical has been transferred to the Hong Kong Stock Exchange List since March 9, and many brokerage firms have given positive ratings. After the results, according to the CMB International Research Report, Kangchen Pharmaceutical's interim results have verified the steady growth of the basic nephrology market and the ability to execute the transformation to an innovative drug platform. The valuation is still at a low level, giving it an “increase in weight” rating, with a target price of HK$22.6. Guoyuan International released a research report stating that the company's products are powerful, urea cleaning technology and market barriers are high, and it is extremely difficult to replicate. The company's performance is expected to continue to grow rapidly, giving it a “buy” rating, with a target price of HK$19.16.
Taken together, Kangchen Pharmaceutical has outlined a clear development blueprint: the core nephrology business provides a stable performance base and abundant cash flow. Diversified business segments contribute incremental flexibility, and the strategic layout of industrial chain extension, overseas expansion, and innovative R&D go hand in hand, making the company's long-term value trends in line with the current tone of Hong Kong stock pharmaceutical investment. At a time when market sentiment is picking up and sector trend reversals are established, the company's stock price is expected to usher in a “Davis double hit”, showing considerable upward elasticity to the market.