
Wintrust Financial (WTFC) Stock Could Be 36% Undervalued Today
Wintrust Financial has delivered a strong multi year share price run, which puts a spotlight on whether the current market value lines up with the returns it earns on its capital. With the stock still reflecting that past performance, investors are asking how much of those capital returns are already embedded in today's price.
- Over the past 5 years the share price has gained 107.1%, which makes it important to test whether the returns Wintrust Financial generates on its capital base support that kind of outcome.
- The business leans on a traditional banking model that can hinge on how efficiently it turns deposits into interest earning assets, so any shift in funding costs or loan mix may influence the sustainability of its returns on capital.
- What if you looked at Wintrust Financial through its earnings instead? See why Wintrust Financial's 11.8x P/E tells a different valuation story.
The issue now is whether the returns Wintrust Financial earns on the capital it deploys are strong enough to justify where the stock trades today.
If you are testing whether Wintrust Financial's returns on capital still justify the share price, it can help to cross check against a focused list such as 29 high quality undervalued stocks.
Is Wintrust Financial a Bargain on Excess Returns?
The Excess Returns model looks at how efficiently Wintrust Financial turns shareholder equity into earnings above its own funding cost. In this case, that spread is quite clear. Book value is $105.26 per share and the stable earnings estimate is $14.42 per share, which implies the bank is expected to keep generating solid profits on its equity base rather than just treading water.
The model uses a cost of equity of $9.53 per share and an excess return of $4.89 per share, supported by an average return on equity of 12.09% and a stable book value estimate of $119.21 per share. Those inputs, combined with the free cash flow projections, lead the Excess Returns framework to an intrinsic value that sits substantially above the current share price of $147.94. Find out what Wintrust Financial could be worth using our Excess Returns estimate.
The Wintrust Financial Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the Excess Returns framework leaves off for Wintrust Financial by spelling out which paths for earnings, growth and profitability would need to play out for the stock to look meaningfully cheaper or more expensive than today. Each scenario links its number to a specific view on how Wintrust Financial's growth, margins and risk profile could evolve, giving you something concrete to revisit as new information comes through the Community page.
One of the top community narratives on Wintrust Financial: 18% undervalued
"Organic loan and deposit growth across commercial, premium finance, mortgage and specialty lending segments is building a larger base of earning assets…"
Discover why this Narrative puts Wintrust Financial at 18% undervalued.
One more signal to check before you decide on Wintrust Financial
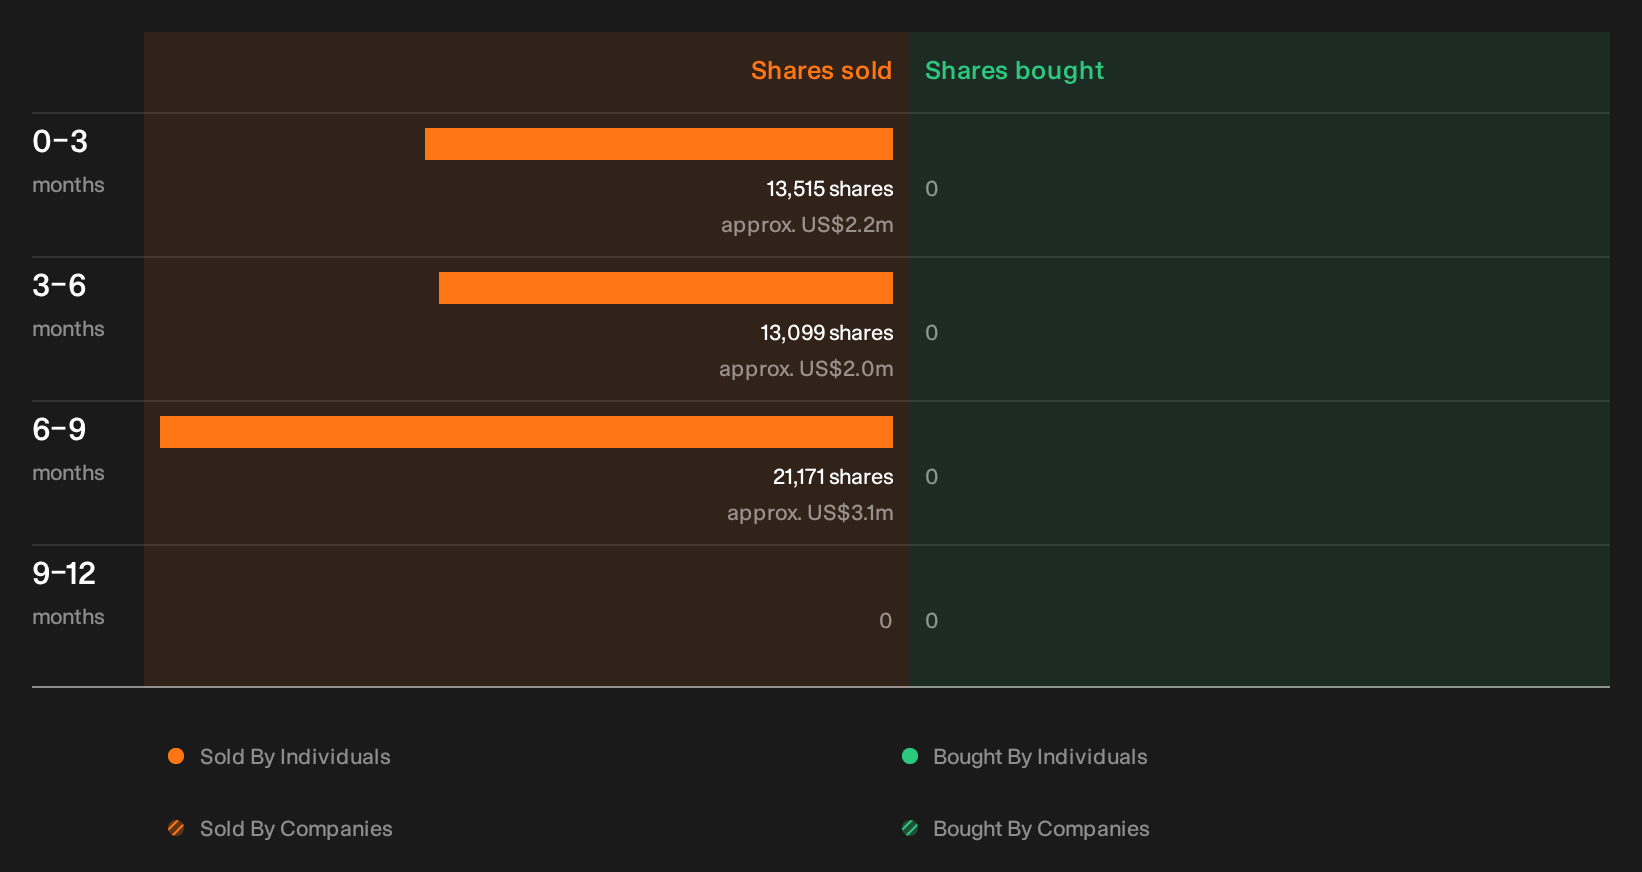
Valuation is only part of the picture for Wintrust Financial, and recent stock sale activity by people inside the business has also been flagged by our checks, with the specific sellers, sizes and possible read throughs left for you to review. See the recent insider selling flagged for Wintrust Financial.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com