
Bossard Holding (SWX:BOSN) Looks Expensive As CFO Change Meets A 21x P E
Bossard Holding (SWX:BOSN) has scheduled a future finance reshuffle, with long-serving CFO Stephan Zehnder set to hand the reins to incoming executive Andreas Jaeger in early 2027.
The incoming CFO announcement has arrived at a time when Bossard Holding’s share price has been strong, with a 1-day share price return of 3.02%, adding to a 90-day gain of 20.10% and a year-to-date share price return of 53.21% at a current level of CHF239.0.
Scan how Bossard Holding compares with other industrial players showing strong momentum and resilient finances using our hand-picked list of solid balance sheet and fundamentals (194 results).
Bulls see Bossard Holding’s recent share price surge as confirmation that the CFO transition is already priced as a positive. Bears look at the valuation signals and see overreach. Which side do the numbers lean toward next?
Price-to-Earnings of 21x for Bossard Holding: Is it justified?
Bossard Holding trades on a P/E of 21x, which is paired with a last close of CHF239 and reflects a richer tag than several reference points.
The P/E ratio compares the current share price with earnings per share. For an industrial fastening and assembly specialist like Bossard Holding, it is a quick way to see how much investors are paying for each unit of profit, especially when earnings quality and return metrics carry weight.
On one side, the business reports a high Return on Equity of 21.8% and high quality earnings, with profit margins at 8% versus 6.7% last year and earnings growth of 28.4% over the past year, faster than the Trade Distributors industry at 8.1%. Those figures suggest the market is willing to pay up for profitability, even though earnings are forecast to grow 6.26% per year, slower than the wider Swiss market at 12.1% and not at a level considered significantly high.
The comparison lines are clear. Bossard Holding is considered expensive against its own estimated fair P/E of 19.4x and against the European Trade Distributors industry average of 17.3x, yet it trades at a lower P/E than the peer average of 31.7x. The current multiple therefore signals a premium that the market could shift closer to the fair ratio over time, while still sitting below some peers that carry even higher expectations.
Explore the SWS fair ratio for Bossard Holding.
Result: Price-to-Earnings of 21x (OVERVALUED)
Still, the Bossard Holding story could be knocked off course if earnings momentum slows while the 21x P/E stays rich, or if the CFO transition unsettles investor confidence.
Find out about the key risks to this Bossard Holding narrative.
Another view on Bossard Holding’s value
The first check on Bossard Holding used its 21x P/E against fair and industry ratios. A second lens comes from our DCF model, which estimates future cash flows at CHF169.16 per share. That is below the current CHF239 level, so on this approach the stock looks overvalued. Which signal would you put more weight on?
Look into how the SWS DCF model arrives at its fair value.
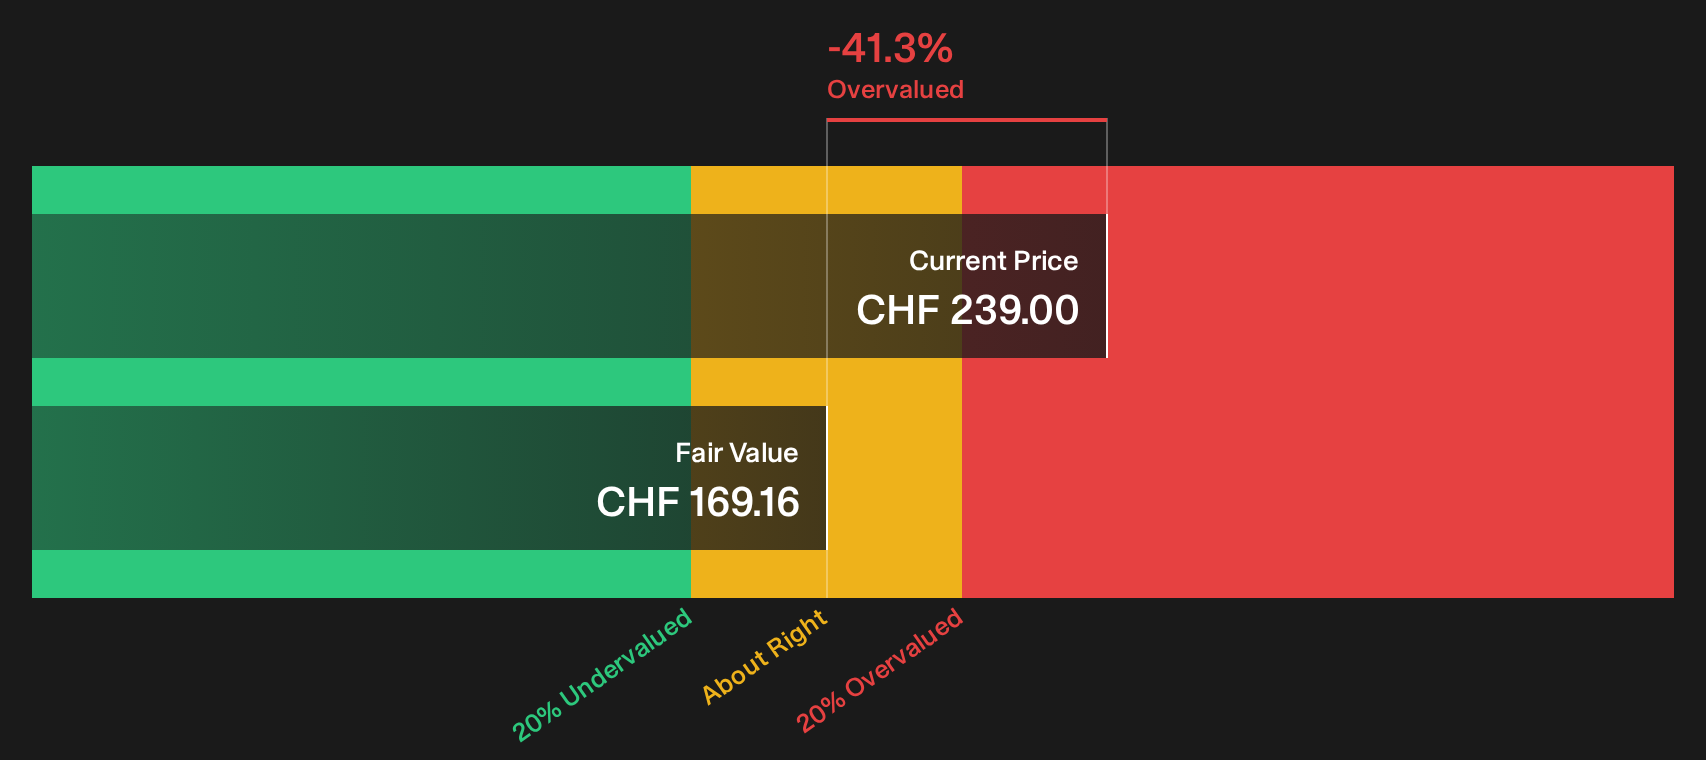
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Bossard Holding for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 177 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Bossard Holding’s valuation story can be useful. Act while the data is fresh and compare the 2 key rewards and 1 important warning sign with your own view.
Looking for more Bossard Holding sized investment ideas?
If you want a broader watchlist beyond Bossard Holding, now is the time to line up fresh ideas so you are ready before the next move.
- Hunt for quality at a discount by scanning our hand picked 177 high quality undervalued stocks. These combine robust fundamentals with pricing that still looks reasonable.
- Build a portfolio that works for you even when markets are choppy by focusing on income focused opportunities inside the 160 dividend fortresses.
- Reduce portfolio stress by concentrating on financially resilient businesses using the curated 104 resilient stocks with low risk scores. This emphasises balance sheet strength and stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com