
Asahi Kasei (TSE:3407) Could Be 58% Undervalued Following Bioprocess Product Launch
Asahi Kasei (TSE:3407) is back on biotech investors’ radar after its Asahi Kasei Bioprocess unit announced the VANTIJ SU-VFC Benchtop, a compact and automated virus filtration platform for cell and gene therapy workflows.
For context, Asahi Kasei’s 1-day share price return of 1.35% and 7-day share price return of 3.06% sit against a 30-day share price decline of 4.21% and a 90-day share price drop of 9.93%, while the year-to-date share price return of 13.70% and 1-year total shareholder return of 39.62% point to momentum that has been building over a longer stretch.
Scan for other healthcare and bioprocessing players showing similar momentum and product catalysts with the curated 74 high quality undiscovered gems that may be flying under most investors' radar.
Asahi Kasei appears to be a solid industrial and healthcare hybrid, with biotech exposure that now has a fresh product story behind it. The key question is whether that story is already reflected in the current share price.
Price-to-Earnings of 11.3x: Is it justified?
On current numbers, Asahi Kasei trades on a P/E of 11.3x, which sits alongside a ¥1,614.5 last close and points to investors paying less for each yen of earnings than many peers.
The P/E ratio simply compares the share price with earnings per share, so it is a quick shorthand for how much the market is willing to pay for current profitability. For a group like Asahi Kasei that spans materials, homes and healthcare, earnings quality and consistency often matter more than headline revenue expansion when considering what this multiple might be pricing in.
Company specific data suggests those earnings are backed by relatively strong fundamentals. Asahi Kasei is described as having high quality earnings, net profit margins of 6.1% versus 4% last year, and earnings growth of 59.9% over the past year, compared with 8.6% per year over five years. That kind of step up, alongside earnings that are still forecast to grow 5.5% per year, can justify the market assigning a richer tag than it would give a business with flat profits. Yet the current 11.3x level remains some way below an estimated fair P/E of 17x, which is presented as a level the ratio might reach if sentiment and fundamentals remain aligned.
Compared with the JP Chemicals industry average P/E of 12.6x and a peer average multiple of 29.7x, Asahi Kasei trades on a markedly cheaper earnings tag. The gap to both its own fair P/E estimate and those reference points is wide, suggesting the current price may be underestimating the earnings profile investors are getting exposure to.
Explore the SWS fair ratio for Asahi Kasei.
Result: Price-to-Earnings of 11.3x (UNDERVALUED)
Still, the Asahi Kasei story can falter if biotech product uptake disappoints, or if its broad materials and housing operations face cyclical pressure.
Find out about the key risks to this Asahi Kasei narrative.
Another View on Asahi Kasei’s Value
A different lens comes from the SWS DCF model, which puts Asahi Kasei’s future cash flow value at ¥3,867.05 per share versus a market price of ¥1,614.5. That points to the stock trading well below this estimate. Which signal should investors focus on when the gap is this wide?
Look into how the SWS DCF model arrives at its fair value.
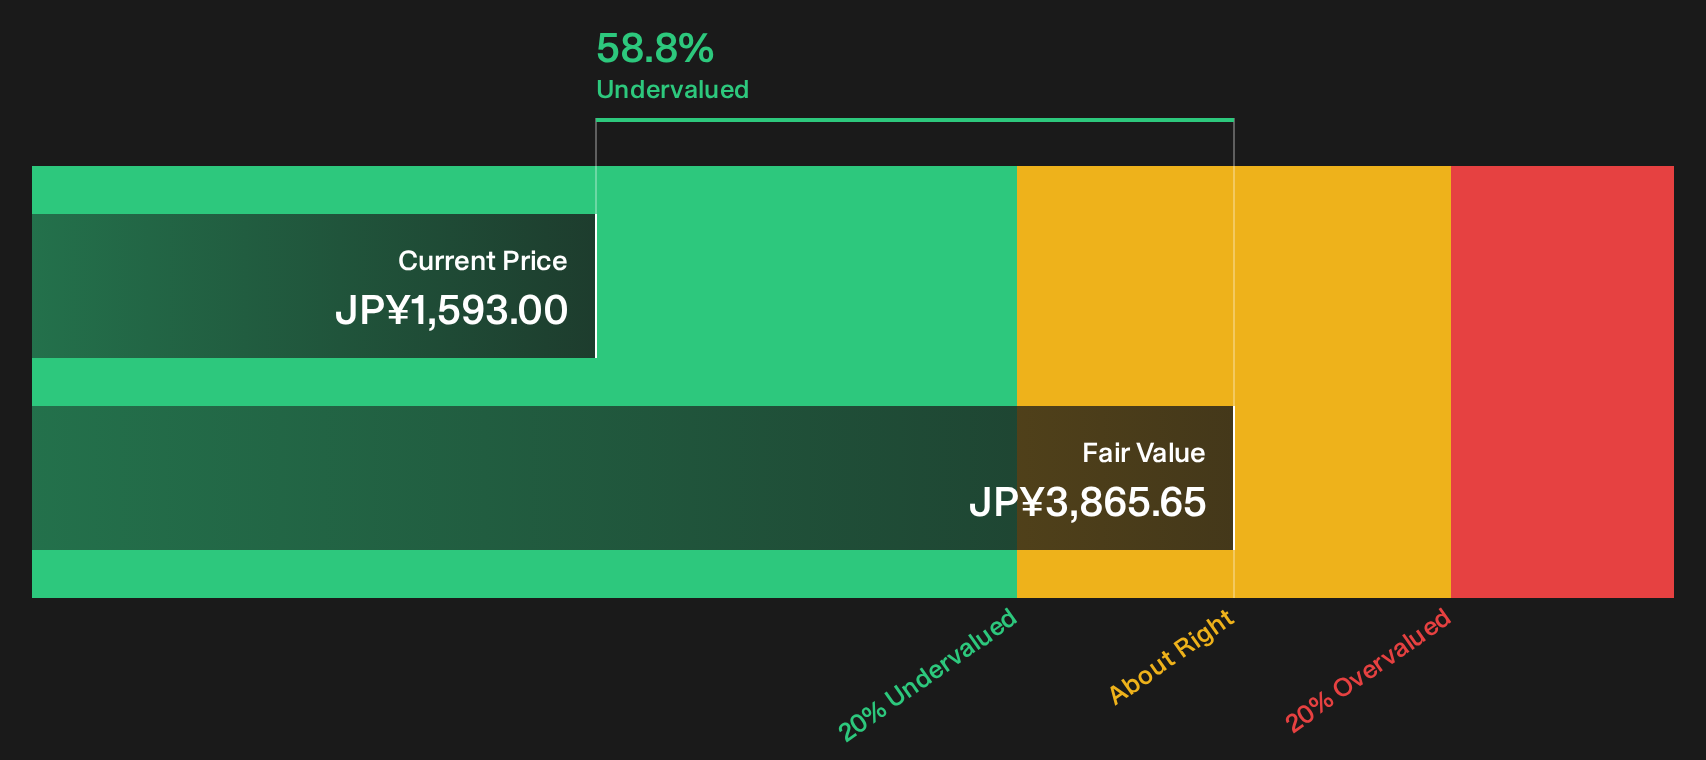
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Asahi Kasei for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 17 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Impressed by the tone of optimism around Asahi Kasei, or still on the fence about what the numbers really imply? Move quickly, pull up the underlying figures, and pressure test the story against the 5 key rewards.
Looking for more Asahi Kasei style ideas?
If Asahi Kasei has sharpened your interest, broaden your watchlist now with a few focused stock ideas before the next wave of opportunities moves first.
- Target resilient cash generators by scanning a list of solid balance sheet and fundamentals (20 results) that can shoulder pressure without relying on fragile financing.
- Hunt for mispriced potential and track a 17 high quality undervalued stocks that could offer more business quality than the current tags suggest.
- Prioritize sleep-at-night holdings by reviewing a 12 resilient stocks with low risk scores where balance sheets, earnings and volatility all work in your favor.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com