
Red Cat Holdings (RCAT) And Its Valuation Case After The 2026 Revenue Target
Red Cat Holdings (RCAT) is back in focus after management outlined a 2026 revenue goal of US$150 million to US$180 million, anchored on AI-enabled Black Widow drones, Hellcat systems for Ukraine, and Blue Ops vessels.
Red Cat Holdings has been trading under pressure, with the share price down 32.0% over the past month and 38.0% over 90 days, even after the recent revenue target update and August earnings miss. However, the 3-year total shareholder return of more than 6x shows earlier investors still sit on very large gains.
Scan for other AI defense and drone players with similar catalysts by checking the hand picked 32 AI small caps that could benefit from the same shift toward secure, domestic systems.
Red Cat Holdings now trades at US$7.10, while analyst targets cluster between US$15 and US$20. Is fair value closer to the current quote or those expectations once you line price up against the estimates?
Most Popular Narrative: 65% Undervalued
Red Cat Holdings is framed as materially undervalued when the most followed narrative fair value of $20 is set against the last close near $7. This comparison puts the entire debate on whether the market is discounting its long term contract and manufacturing story too heavily.
Defense demand for drones and uncrewed surface vessels is a long term secular theme, and management repeatedly points to the U.S. Army talking about millions of drones and new shipbuilding priorities. If this demand is converted into larger contracts, it could support higher revenue than today and put upward pressure on the share price through stronger earnings.
See why 42 investors see Red Cat Holdings as 65% undervalued.
Result: Fair Value of $20 (UNDERVALUED)
Still, Red Cat Holdings faces real pressure if sector wide multiple compression persists and if planned NATO and Asia Pacific orders do not convert into repeat contracts.
Find out about the key risks to this Red Cat Holdings narrative.
Another View: Red Cat Holdings Looks Expensive On Sales
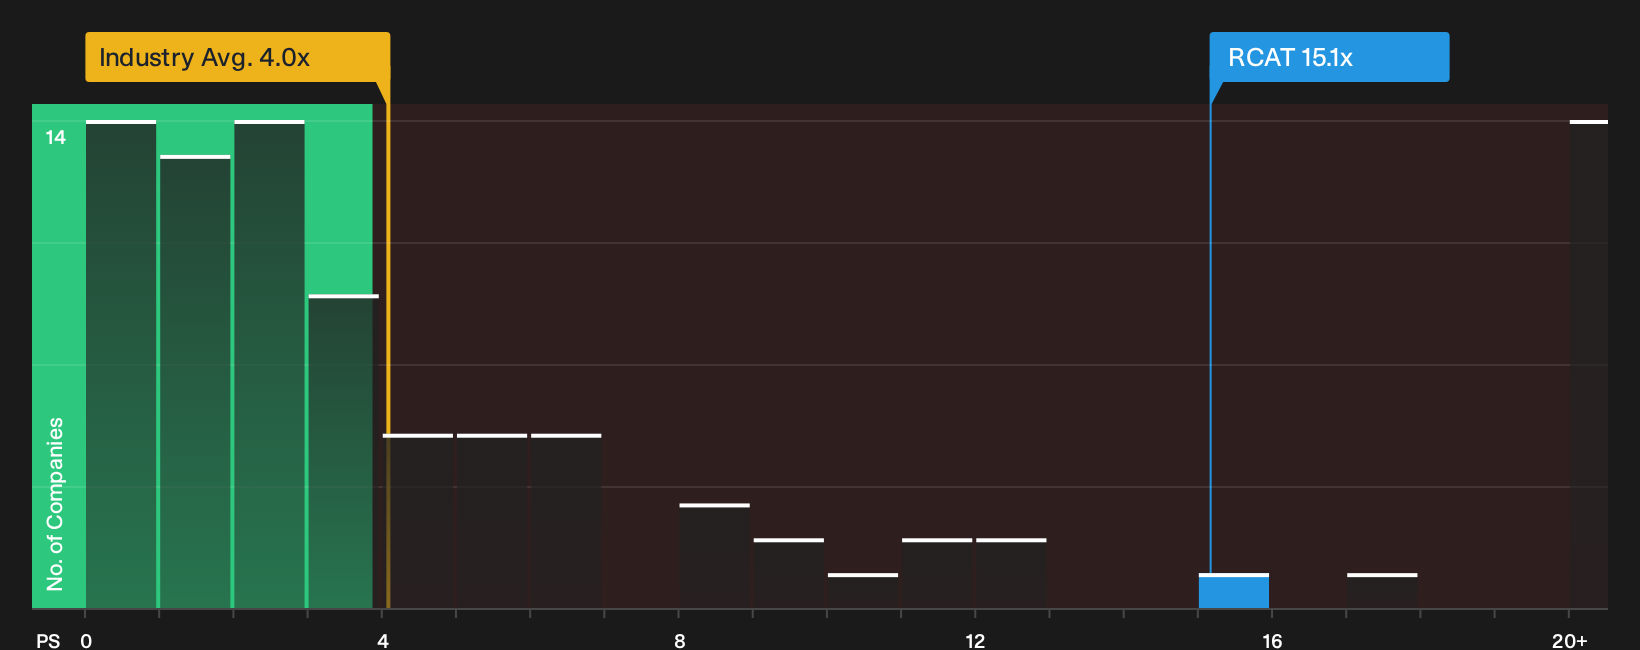
On the flipside of that US$20 fair value story, Red Cat Holdings trades on a P/S of 15.1x while US Aerospace & Defense peers sit near 4.1x and the fair ratio is 4.9x. That is a wide gap, so is the real risk that expectations are already running too far ahead of the financials?
For readers who prefer to lean on simple market multiples rather than long range narratives, it can help to see how that P/S gap compresses or stretches over time as sentiment shifts, which is exactly what the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Red Cat Holdings can easily pull you in opposite directions, so consider acting promptly, review the full picture for yourself, and weigh both the 1 key reward and 4 important warning signs.
Looking for more Red Cat Holdings style investment ideas?
If Red Cat Holdings has your attention, do not stop there. Broaden your watchlist with other focused ideas that match how you like to invest.
- Target steadier opportunities by scanning a curated 11 resilient stocks with low risk scores chosen for resilience when market swings test your conviction.
- Hunt for mispriced quality and see which companies line up in the 16 high quality undiscovered gems before they hit the wider market radar.
- Stack income potential on top of capital growth and review a focused set of 6 dividend fortresses that prioritize reliable cash returns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com