
DXP Enterprises (DXPE) Delivers Strong Growth, Is The Stock Fully Priced?
DXP Enterprises (DXPE) has drawn fresh attention after a period of strong execution, with annual revenue growth of 16.8%, earnings per share expansion of 22.5%, and a 4 percentage point uplift in free cash flow margins.
Despite a softer 30-day share price return of 7.12% in the red, DXP Enterprises is still carrying strong momentum. The company has a 90-day share price gain of 5.67% and a year-to-date share price return of 70.39%, sitting on top of a very large 5-year total shareholder return of more than 5x.
Scan for other industrial distributors showing similar execution and capital discipline by reviewing the hand-picked 16 high quality undiscovered gems that share DXP Enterprises’ focus on growth and improving cash generation.
DXP Enterprises looks like a well run industrial distributor with rising earnings power and healthier cash generation, yet the stock has already surged this year. Is that quality now fully reflected in the current share price?
Most Popular Narrative: 8% Undervalued
DXP Enterprises is trading at $183.54 against a narrative fair value of $200, which frames the current debate around how much earnings power is already in the price.
The company's robust acquisition pipeline and recent moves to expand geographically and diversify into new markets (such as water, air compressors, and data centers) position it to accelerate top-line growth and increase earnings power, leveraging long-term industry consolidation trends.
Strength in after-market and specialty services, including recurring service and parts agreements, is increasing the share of recurring revenue and supporting higher net margins over the long term.
See why 10 investors see DXP Enterprises as 8% undervalued.
Result: Fair Value of $200 (UNDERVALUED)
Still, the bullish DXP Enterprises narrative leans on smooth acquisition integration and stable energy related demand, both of which could unravel and pressure margins and earnings expectations.
Find out about the key risks to this DXP Enterprises narrative.
Another View On DXP Enterprises’ Valuation
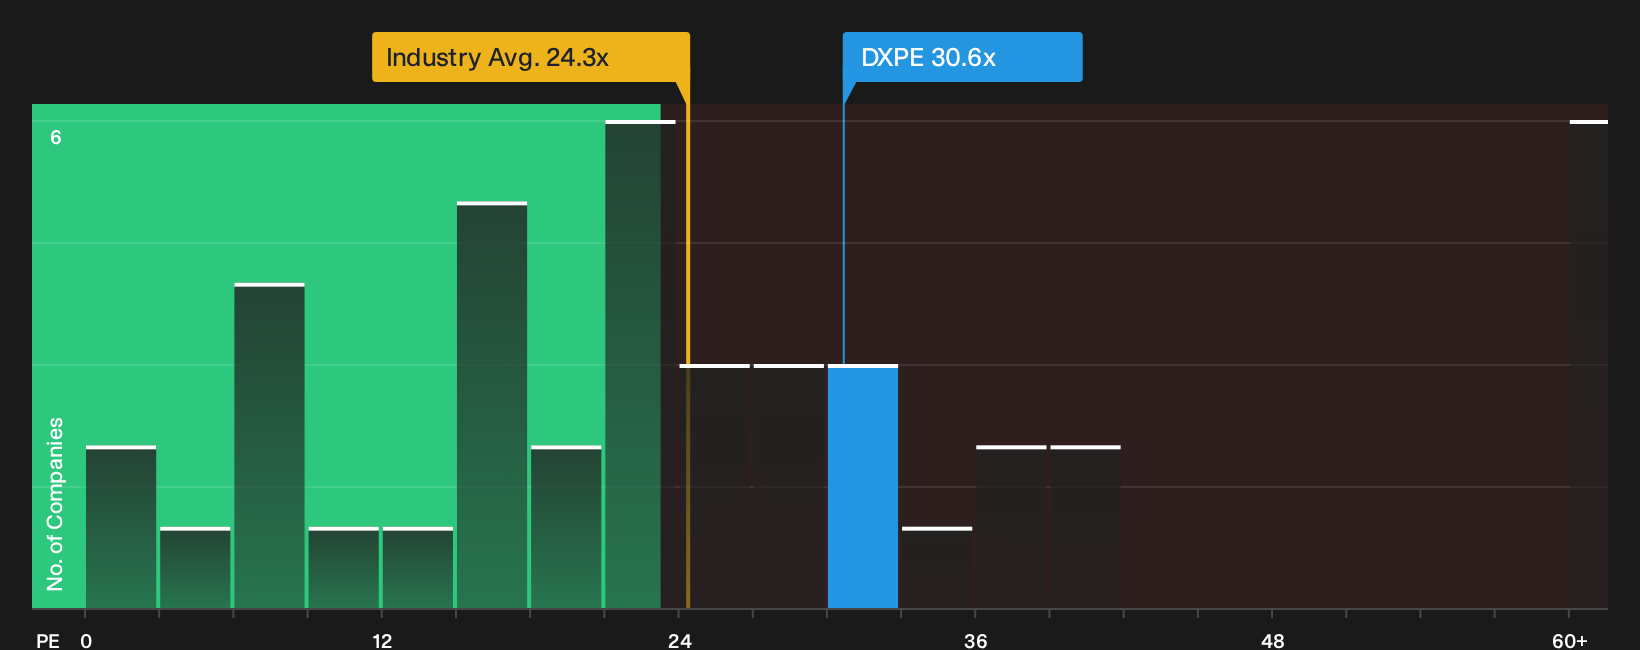
The earlier narrative leans on a fair value of $200, yet the market is also pricing DXP Enterprises on a rich P/E of 30.6x. That is higher than the US Trade Distributors industry at 24.3x and above a fair ratio estimate of 28x, which suggests less margin for error if growth or margins slip.
For investors weighing what that gap really means for upside versus downside risk, the valuation breakdown can help frame how much confidence is baked into today’s multiple: See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on DXP Enterprises is mixed, with solid execution on one side and valuation questions on the other. To see how that balance of opportunity and concern stacks up, review the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond DXP Enterprises?
If you stop with DXP Enterprises, you risk missing other opportunities that match your style, risk tolerance, and income goals across the market.
- Target potential mispricing by scanning a curated set of quality companies that screen as undervalued using the 33 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (22 results) that can help you focus on financially robust businesses when building your portfolio.
- Hunt for overlooked potential by checking a curated 16 high quality undiscovered gems that may not yet be widely followed.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com