
Does Raised 2026 Outlook Change The Bull Case For Arista Networks Stock (ANET)?
- Arista Networks recently lifted its 2026 revenue outlook for the third time, backed by strong AI data center demand and improved supply chain visibility, including long-term memory commitments into 2027.
- The decision to nearly triple multiyear supplier purchase commitments signals management’s confidence in sustained AI infrastructure orders from hyperscaler clients such as Microsoft and Meta.
- Next, the focus shifts to how Arista Networks' upgraded revenue outlook could reshape its broader investment narrative around AI infrastructure demand.
Look beyond Arista Networks to discover additional AI infrastructure opportunities with strong momentum using our curated list of 60 AI infrastructure stocks in one convenient place.
Arista Networks Investment Narrative Recap
To own Arista Networks, you need to be comfortable tying your capital to the AI data center buildout and the shift toward high bandwidth Ethernet networks. The thesis leans on continued demand from hyperscalers, expanding use of Arista’s software stack, and disciplined execution as AI deployments get larger and more complex.
In the very near term, the key swing factor is how cleanly Arista converts its large AI orders into shipped product and recognized revenue as supply constraints ease. The biggest risk is still concentration in a few hyperscaler customers, where any pause or reprioritization of AI spending could hit orders quickly.
The most relevant recent development for that thesis is Arista Networks lifting its 2026 revenue outlook again, along with nearly tripling multiyear supplier commitments into 2027. Locking in memory and networking components supports the AI buildout story because it reduces the chance that constrained parts limit the firm’s ability to deliver on booked demand.
Those larger commitments also raise the stakes on execution. If AI cluster build plans from key clients such as Microsoft or Meta slow or shift, Arista could be holding supply that is harder to redeploy, which would weigh on margins. For you, the catalyst to watch is each earnings update on AI infrastructure deployments versus those long term supply agreements.
Arista Networks' analyst narrative points to forecast revenue of US$21.3b and earnings of US$8.2b by 2029, based on a projected 26.4% yearly revenue growth rate and an earnings increase of about US$4.2b from US$4.0b today.
Uncover how Arista Networks' fair value indicates a 22% potential upside to its current price, which could narrow quickly.
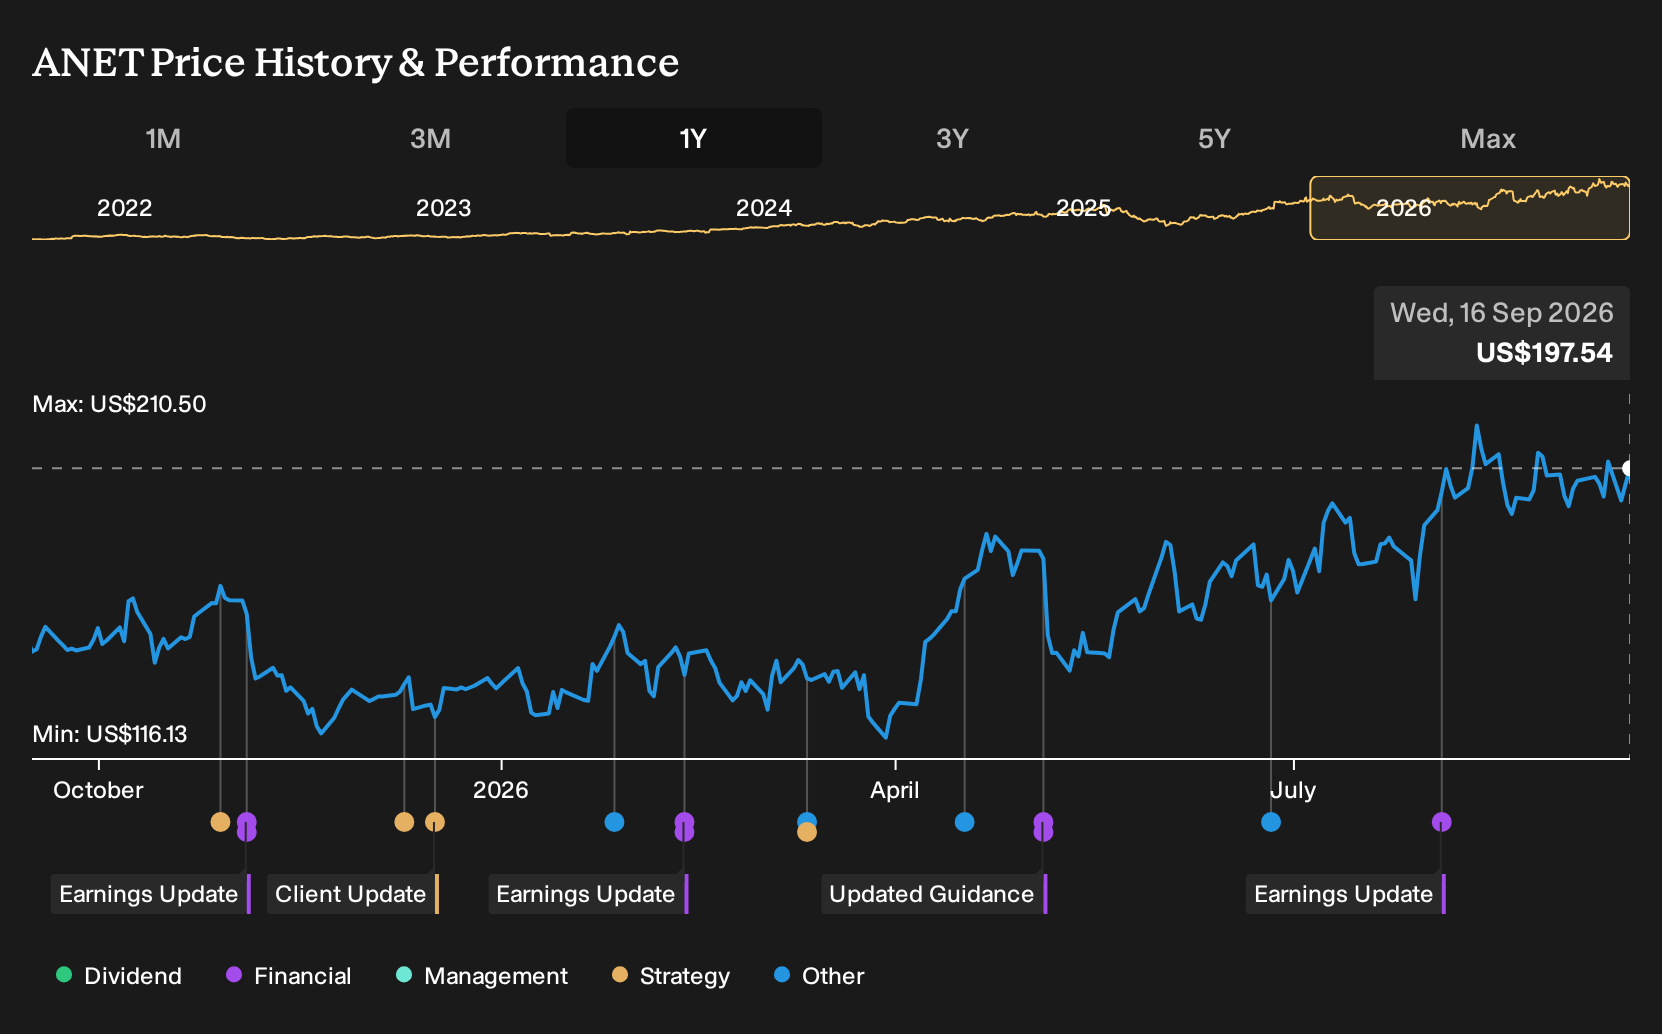
Exploring Other Perspectives
One alternate view focuses squarely on margin pressure rather than AI demand. The most cautious Arista Networks analysts had been modeling revenue of about US$18.3b and earnings of US$6.8b by 2029, with margins easing to 37.2%. That is a far more restrained narrative. You can compare these expectations yourself as fresh AI news rolls in.
Explore 7 other Arista Networks fair value estimates, including one that suggests it could be worth just $190.02.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Arista Networks research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Arista Networks. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Arista Networks' overall financial health at a glance.
Looking For More Investment Ideas Beyond Arista Networks?
If you want to broaden your watchlist beyond Arista Networks, the Simply Wall St Screener can help you sort through the market using clear, fundamentals based filters so you can focus on opportunities that match your risk and income goals.
- For investors who care most about financial resilience, start with a list of solid balance sheet and fundamentals (22 results) that can help you focus on businesses with stronger cushions against shocks.
- If you want income on top of potential capital returns, consider a 6 dividend fortresses that screens for higher yielding payouts backed by underlying fundamentals.
- When you are hunting for opportunities that the market may not be paying full attention to, look through a 16 high quality undiscovered gems that still show strong financial underpinnings.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com