
ACV Auctions (ACVA) Stock May Be Fully Priced Despite $1.9B Takeover Deal
ACV Auctions has just agreed to a US$1.9b all cash takeover by Copart at US$10.50 per share, and that deal price now frames a simple question for investors who care about its sales. With the stock recently closing at US$10.42, the key issue is whether that takeover level makes sense given what the business is generating in revenue today.
- Over the past 5 years the share price has fallen 43.2%, which puts extra weight on whether the current exit price fairly reflects the progress in ACV Auctions' sales base.
- The planned combination of Copart's physical auction network with ACV Auctions' digital wholesale platform may support different long term sales expectations, since the buyer is effectively putting a cash value on ACV Auctions' role in that combined remarketing system.
- There is a second opinion on ACV Auctions worth weighing. See what analysts think ACV Auctions's shares could be worth.
The issue now is whether ACV Auctions' current takeover price is adequately supported by its sales when you compare it with the Fair Ratio benchmark.
If you want other ideas built around sales and price, a focused stock screen is a useful second step after ACV Auctions. Consider running your eye over 33 high quality undervalued stocks
Does ACV Auctions Look Pricey on Sales?
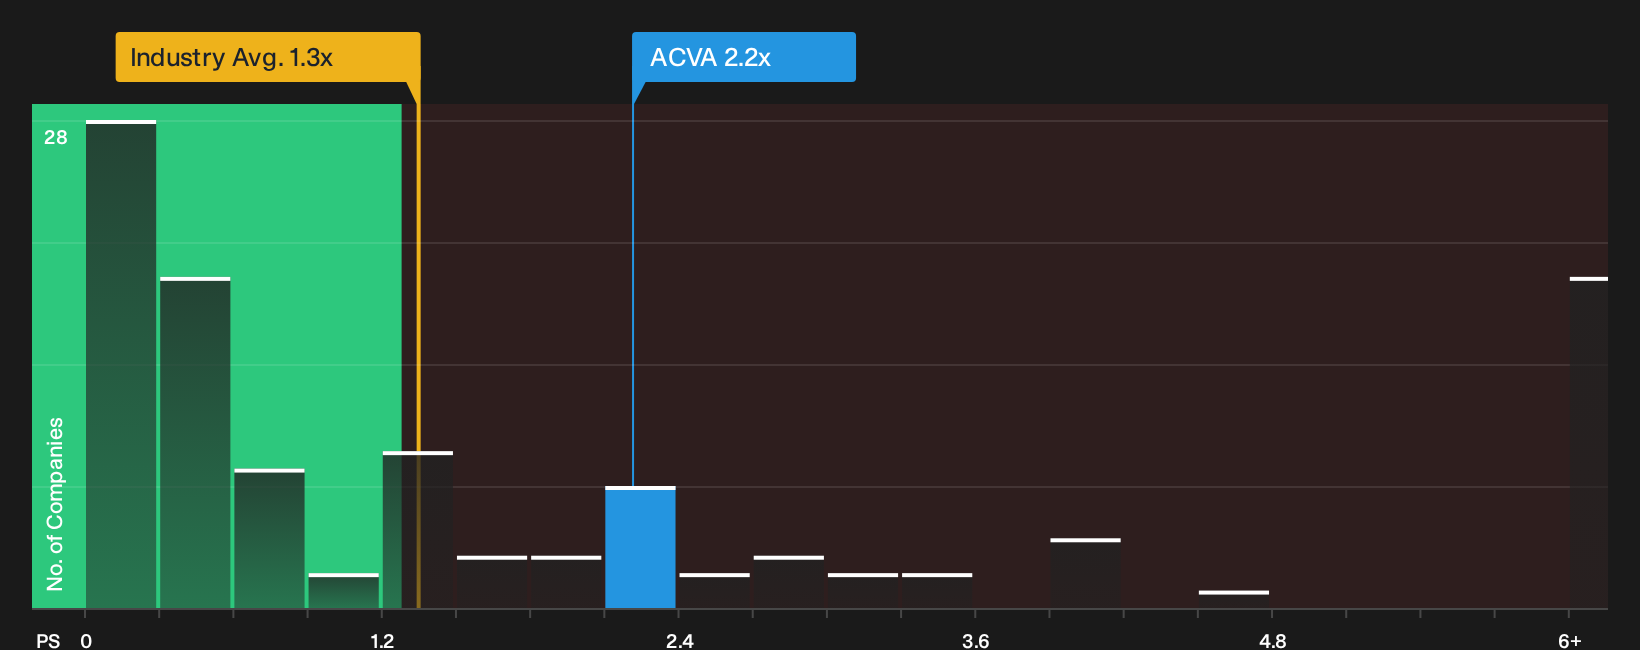
P/S is a useful lens for ACV Auctions because investors are ultimately paying for the scale and quality of its transaction revenue rather than current earnings. On this measure, the stock trades on a P/S of 2.2x, compared with a Commercial Services industry average of about 1.3x and a peer group closer to 1.6x. That is a clear premium to both the wider sector and more directly comparable businesses.
The Fair Ratio, which tailors a reference multiple to ACV Auctions based on its margins, size, risk profile and sector, sits below the current P/S level. That gap points to the shares screening as overvalued on sales using this framework, even after the Copart cash bid has largely anchored the price near the offer. Because the takeover proposal already reflects this richer multiple, any investor weighing the stock now is essentially deciding whether that bid premium above the Fair Ratio is acceptable or whether it prices in more optimism than the underlying sales base supports. Explore the numbers behind ACV Auctions's P/S valuation.
The ACV Auctions Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for ACV Auctions pick up where the P/S debate leaves off and explain what kind of future for growth, margins and earnings would need to play out for the stock to look meaningfully cheaper or more expensive than today’s takeover anchor. Each narrative sets out ACV Auctions' implied fair value as a thesis about the business that can be tracked over time rather than a one off snapshot on a chart.
Community sentiment on ACV Auctions splits between investors who still see meaningful upside in the model and those who think the Copart offer already reflects most of that potential.
Bull case: 34% undervalued
"Leveraging its industry-leading data, inspection infrastructure, and AI capabilities, ACV is positioned to extend beyond auto auctions into adjacent high-margin verticals such as insurance, fleet management, vehicle reconditioning, and pricing as a platform…"
Discover why this Narrative puts ACV Auctions at 34% undervalued.
Bear case: roughly fairly valued
"The company is projecting flat to slightly down dealer wholesale volumes for 2025, citing higher dealer trade retention rates and lower conversion rates on its platform, which could signal that used car supply is tightening and result in lower transaction volume growth…"
Explore why this Narrative puts ACV Auctions at roughly fairly valued.
One big piece ACV Auctions investors still have not checked
Everything here has focused on what ACV Auctions looks like today, but the next layer is how professional analysts currently map out its revenue and earnings profile a few years from now and how that compares with the takeover price. Explore where analysts expect ACV Auctions to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com