
Dominion Energy (D), What Is Behind The Fresh Attention?
Customer-focused Virginia proposal puts Dominion Energy in the spotlight
Dominion Energy (D) and NextEra Energy set fresh terms in Virginia, offering larger bill credits for households and expanded support programs, while outlining new investment commitments in solar, storage, and nuclear projects.
For investors watching Dominion Energy, the proposal raises practical questions about earnings mix, long-term capital needs, and how regulators might weigh customer relief against future grid and generation spending.
Dominion Energy's share price has eased in the short term, with the stock down 7.7% over the past month. This comes even as the year to date share price return of 7.2% and a 1 year total shareholder return of 11.1% sit alongside a very large 3 year total shareholder return of 52.5%, which points to earlier momentum now cooling as investors reassess growth prospects and regulatory risk around deals like the Virginia proposal.
Scan beyond Dominion Energy to find other regulated utilities with similar policy catalysts in our curated 38 power grid technology and infrastructure stocks, which is poised for grid and infrastructure upgrades.
Dominion Energy has pulled back even as returns over 1 and 3 years remain positive. That mix of recent weakness and longer run gains puts a simple question in front of you: pay up now or wait for a cleaner entry as the valuation picture comes into focus next.
Most Popular Narrative: 10.5% Undervalued
The most followed valuation narrative pegs Dominion Energy’s fair value at $71 per share, compared with the last close at $63.51. This frames the Virginia proposal and merger news against a backdrop of modest undervaluation and a relatively low 7.1% discount rate assumption.
Large-scale investments in regulated renewables, especially the Coastal Virginia Offshore Wind (CVOW) project, position Dominion to benefit from the accelerating energy transition, earning stable regulated returns and expanding rate base, with a positive impact on long-term earnings.
See why 48 investors see Dominion Energy as 11% undervalued.
Result: Fair Value of $71 (UNDERVALUED)
Still, the Dominion Energy story can change quickly if CVOW costs climb without full recovery approval, or if future rate decisions come in less generous than expected.
Find out about the key risks to this Dominion Energy narrative.
Another View on Dominion Energy’s valuation
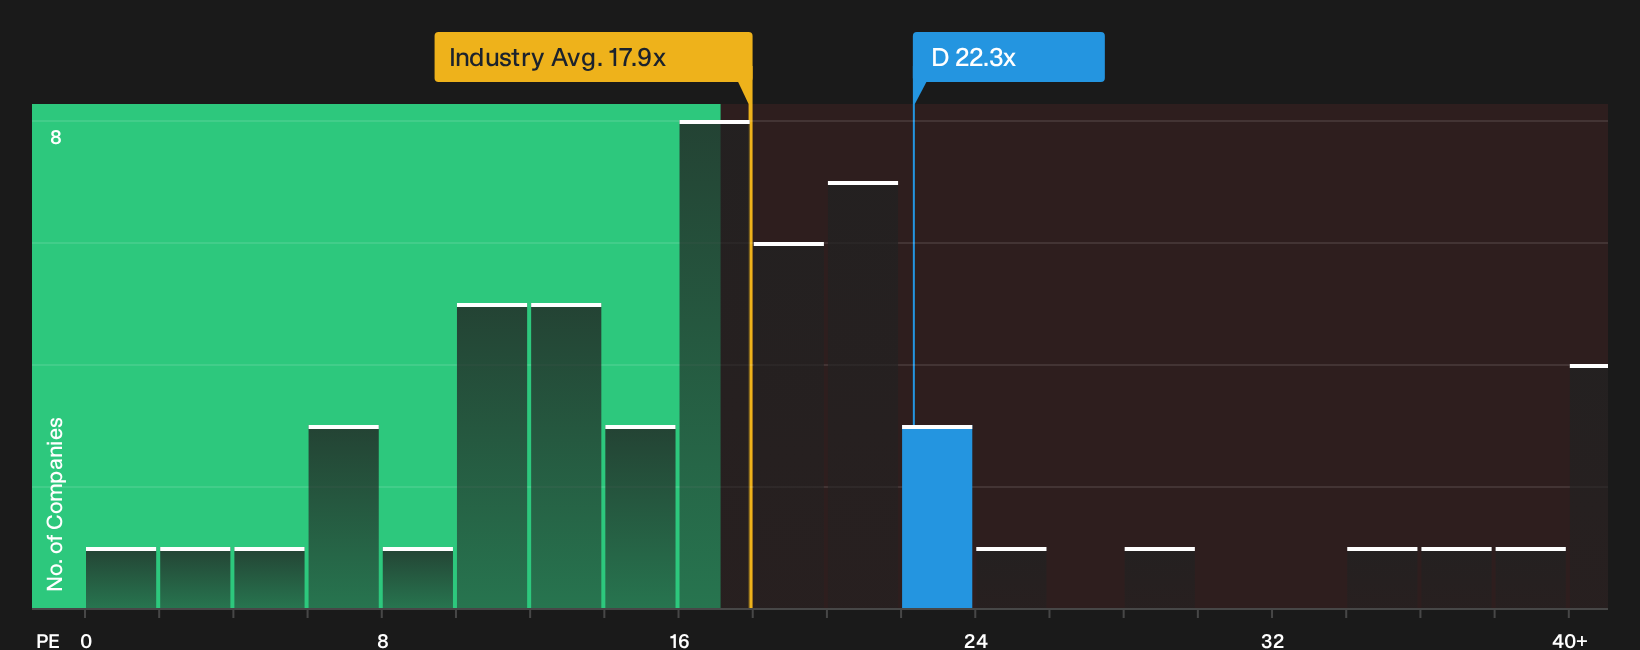
There is a catch. On simple P/E math, Dominion Energy trades at 22.3x, which is richer than both the global Integrated Utilities group at 17.9x and its peer average at 19.6x, even though the fair ratio sits higher at 24x. That mix hints at upside, but it also raises the question of how much valuation risk you are really willing to carry at today’s price.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Dominion Energy story today. If you want to move fast and build your own stance, start with the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Dominion Energy?
If Dominion Energy has your attention, do not stop there. Cast a wider net with focused screeners that surface different types of potential opportunities across the market.
- Target resilient compounding potential by reviewing businesses on the 33 high quality undervalued stocks that combine quality fundamentals with prices that sit below their estimated worth.
- Prioritise income and stability by scanning the 6 dividend fortresses which highlights companies offering higher yields with an emphasis on durability of payouts.
- Protect your downside first by starting with the 11 resilient stocks with low risk scores where balance sheet strength and lower overall risk profiles do the heavy lifting.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com