
CLP Holdings (SEHK:2) Backs Grid And Renewable Growth, Does It Look Fairly Valued?
CLP Holdings (SEHK:2) last closed at HK$77.50, giving the utility group an equity value of about HK$195.8b. Recent returns show mixed momentum over the past week and month.
The recent 1-day share price return of 0.85% barely offsets the 7-day share price dip of 1.96%. A 90-day gain of 5.95% and year-to-date share price return of 10.87% sit alongside a 1-year total shareholder return of 23.02%, which points to gradually improving sentiment around CLP Holdings.
Compare CLP Holdings with hand-picked utilities and infrastructure peers by scanning the 38 power grid technology and infrastructure stocks that could be setting up for the next leg of momentum.
That mix of steady longer term gains and softer recent trading raises a simple question. Are investors paying up for CLP Holdings because of the underlying earnings profile, or is this mostly a swing in sentiment that the valuation now needs to justify?
Most Popular Narrative: 2.5% Undervalued
CLP Holdings is trading at HK$77.50 against a widely followed fair value estimate of HK$79.49, which frames the current share price as slightly below that narrative view and puts the focus squarely on how its grid and renewable plans are expected to play out over time.
Growing capital investment in grid modernization and zero-carbon infrastructure in Hong Kong, driven by upcoming cross-border transmission needs, electrification of transport, and the government's 2035 and 2050 climate targets, is set to underpin steady regulated asset growth and predictable earnings, supporting long-term increases in revenue and cash flow.
See why 6 investors see CLP Holdings as 3% undervalued.
Result: Fair Value of HK$79.49 (UNDERVALUED)
Still, parts of the CLP Holdings story carry clear risk, especially ongoing tariff pressure in Australia and policy uncertainty around new renewable projects in Mainland China.
Find out about the key risks to this CLP Holdings narrative.
Another View On CLP Holdings' Valuation
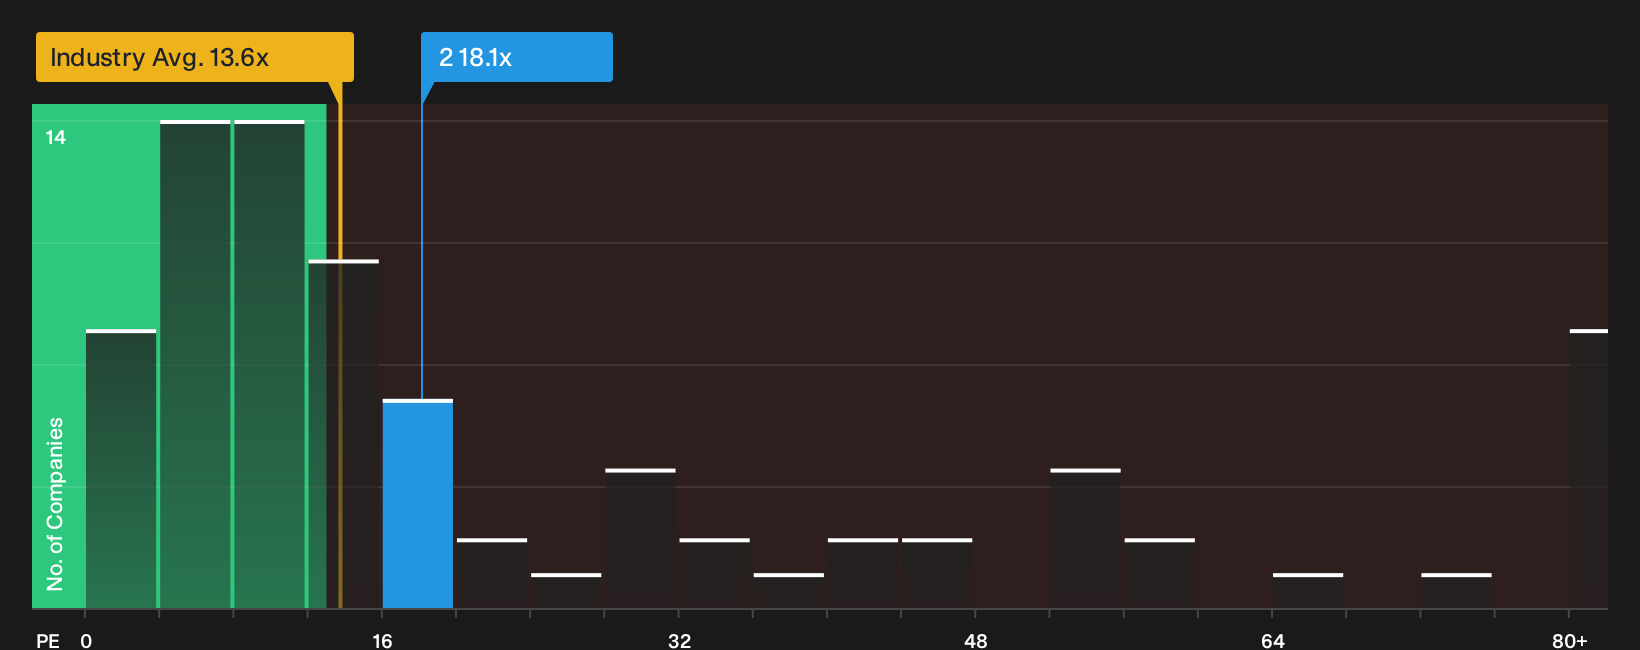
On a simple earnings yardstick, CLP Holdings looks less comfortable. The stock trades on a P/E of 18.1x, while peers average 11.1x and the fair ratio is 9.8x. That gap points to valuation risk rather than a clear bargain. Which story do you trust more, the slight undervaluation or the earnings premium?
See what the numbers say about this price in the fuller breakdown, starting with the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Unsure whether the CLP Holdings setup feels reassuring or stretched? Act quickly, review the underlying data, and decide if the story fits your risk tolerance by checking the 2 important warning signs.
Looking for more investment ideas beyond CLP Holdings?
If CLP Holdings has sharpened your thinking, broaden your watchlist with other potential opportunities surfaced by the Simply Wall St Screener.
- Target dependable income streams by scanning companies screened as 162 dividend fortresses that aim to pair yield with resilience.
- Spot quality at a potential discount by reviewing the 192 high quality undervalued stocks that combine solid fundamentals with pricing that may look appealing.
- Reduce portfolio stress by assessing 103 resilient stocks with low risk scores that score well on stability and financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com