
Companies Like Shuoao International Holdings (HKG:2336) Are In A Position To Invest In Growth
We can readily understand why investors are attracted to unprofitable companies. For example, biotech and mining exploration companies often lose money for years before finding success with a new treatment or mineral discovery. Having said that, unprofitable companies are risky because they could potentially burn through all their cash and become distressed.
Given this risk, we thought we'd take a look at whether Shuoao International Holdings (HKG:2336) shareholders should be worried about its cash burn. In this article, we define cash burn as its annual (negative) free cash flow, which is the amount of money a company spends each year to fund its growth. Let's start with an examination of the business' cash, relative to its cash burn.
When Might Shuoao International Holdings Run Out Of Money?
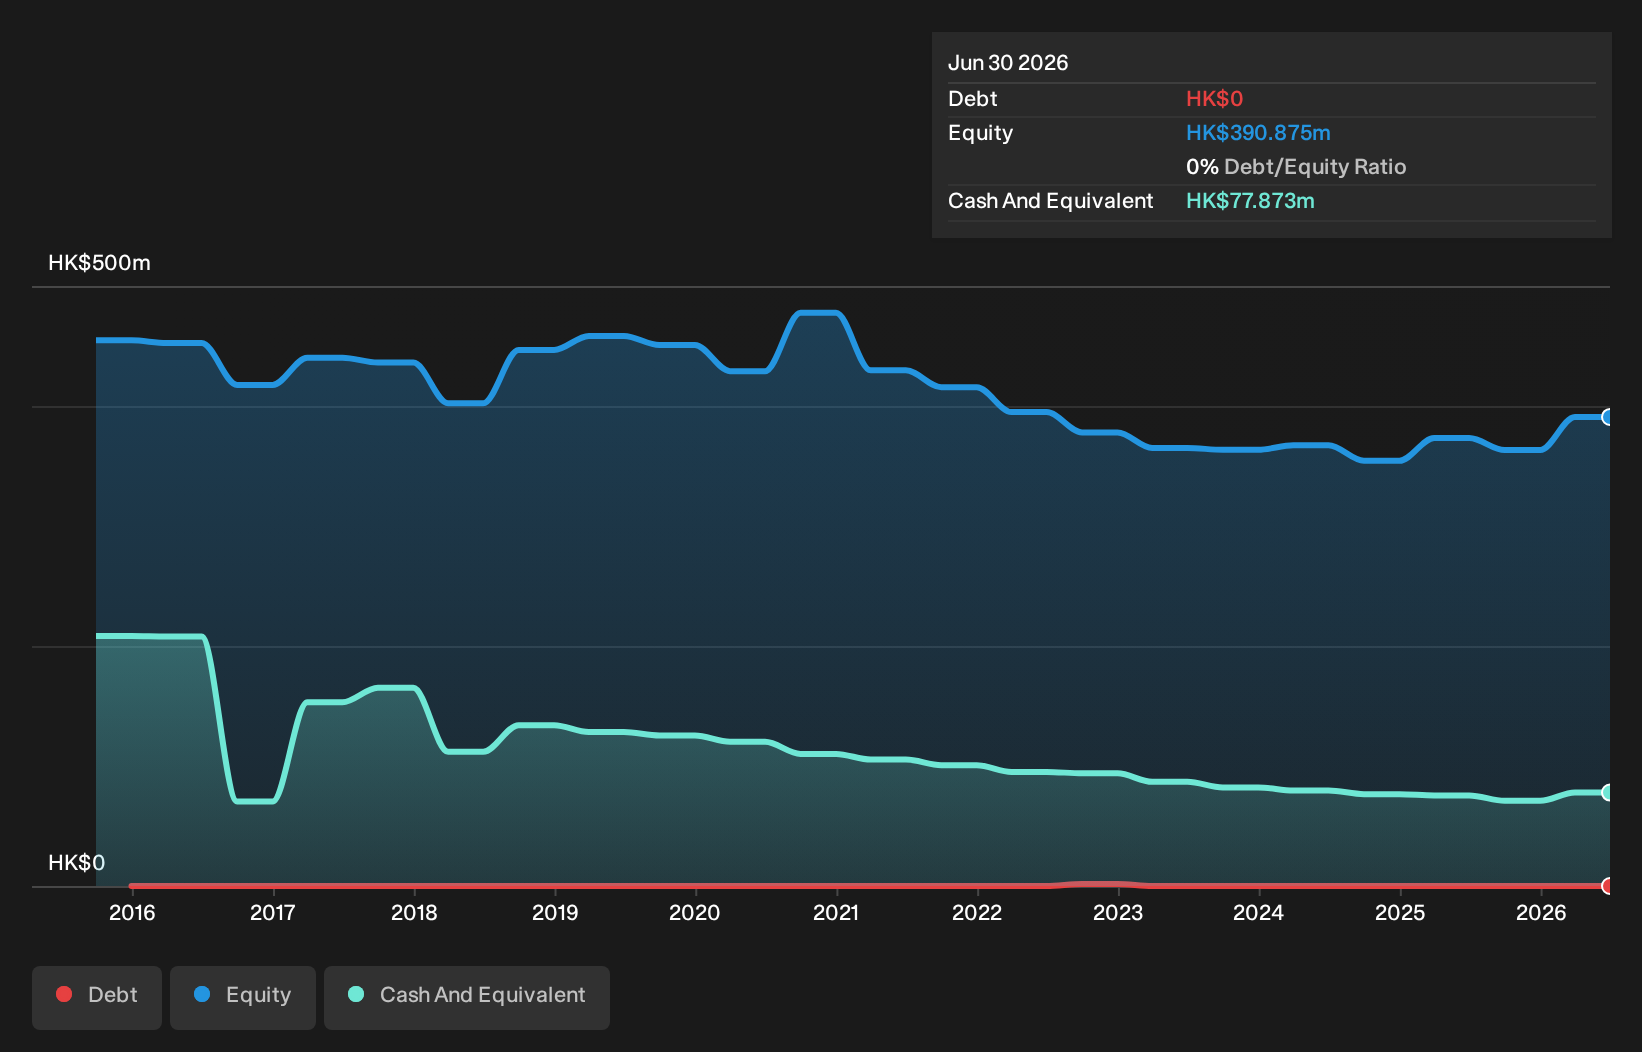
A company's cash runway is calculated by dividing its cash hoard by its cash burn. When Shuoao International Holdings last reported its June 2026 balance sheet in August 2026, it had zero debt and cash worth HK$78m. Importantly, its cash burn was HK$8.3m over the trailing twelve months. So it had a cash runway of about 9.4 years from June 2026. Even though this is but one measure of the company's cash burn, the thought of such a long cash runway warms our bellies in a comforting way. The image below shows how its cash balance has been changing over the last few years.
See our latest analysis for Shuoao International Holdings
How Well Is Shuoao International Holdings Growing?
Some investors might find it troubling that Shuoao International Holdings is actually increasing its cash burn, which is up 16% in the last year. And we must say we find it concerning that operating revenue dropped 29% over the same period. Taken together, we think these growth metrics are a little worrying. In reality, this article only makes a short study of the company's growth data. You can take a look at how Shuoao International Holdings has developed its business over time by checking this visualization of its revenue and earnings history.
How Hard Would It Be For Shuoao International Holdings To Raise More Cash For Growth?
Even though it seems like Shuoao International Holdings is developing its business nicely, we still like to consider how easily it could raise more money to accelerate growth. Generally speaking, a listed business can raise new cash through issuing shares or taking on debt. Many companies end up issuing new shares to fund future growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
Since it has a market capitalisation of HK$354m, Shuoao International Holdings' HK$8.3m in cash burn equates to about 2.3% of its market value. So it could almost certainly just borrow a little to fund another year's growth, or else easily raise the cash by issuing a few shares.
So, Should We Worry About Shuoao International Holdings' Cash Burn?
It may already be apparent to you that we're relatively comfortable with the way Shuoao International Holdings is burning through its cash. In particular, we think its cash runway stands out as evidence that the company is well on top of its spending. Although its falling revenue does give us reason for pause, the other metrics we discussed in this article form a positive picture overall. Based on the factors mentioned in this article, we think its cash burn situation warrants some attention from shareholders, but we don't think they should be worried. Readers need to have a sound understanding of business risks before investing in a stock, and we've spotted 2 warning signs for Shuoao International Holdings that potential shareholders should take into account before putting money into a stock.
If you would prefer to check out another company with better fundamentals, then do not miss this free list of interesting companies, that have HIGH return on equity and low debt or this list of stocks which are all forecast to grow.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.