
3 Financial Stocks Screening Well After The Latest Fed Rate Hike
The Federal Reserve just pushed rates higher again, and that single move has quietly reshuffled the deck for every big U.S. financial stock you watch on your screen. A higher-for-longer policy can help some balance sheets while it squeezes others, which means investors who react slowly risk missing the next phase of winners. This article examines three U.S. large-cap financial stocks exposed to the latest Fed shift and explains why each one may warrant closer attention.
The three stocks highlighted below are just a sample, and the full screen surfaced 40 more large-cap banks and insurers with equally compelling stories that are not covered here. Head straight into the U.S. Large-Cap Financials (Banks & Insurance) screener to identify, compare, and analyze the highest-conviction ideas that fit your own risk and income goals.
Stewart Information Services (STC)
Overview: Stewart Information Services provides title insurance and related real estate transaction services for buyers, lenders, and property professionals in the U.S. and abroad.
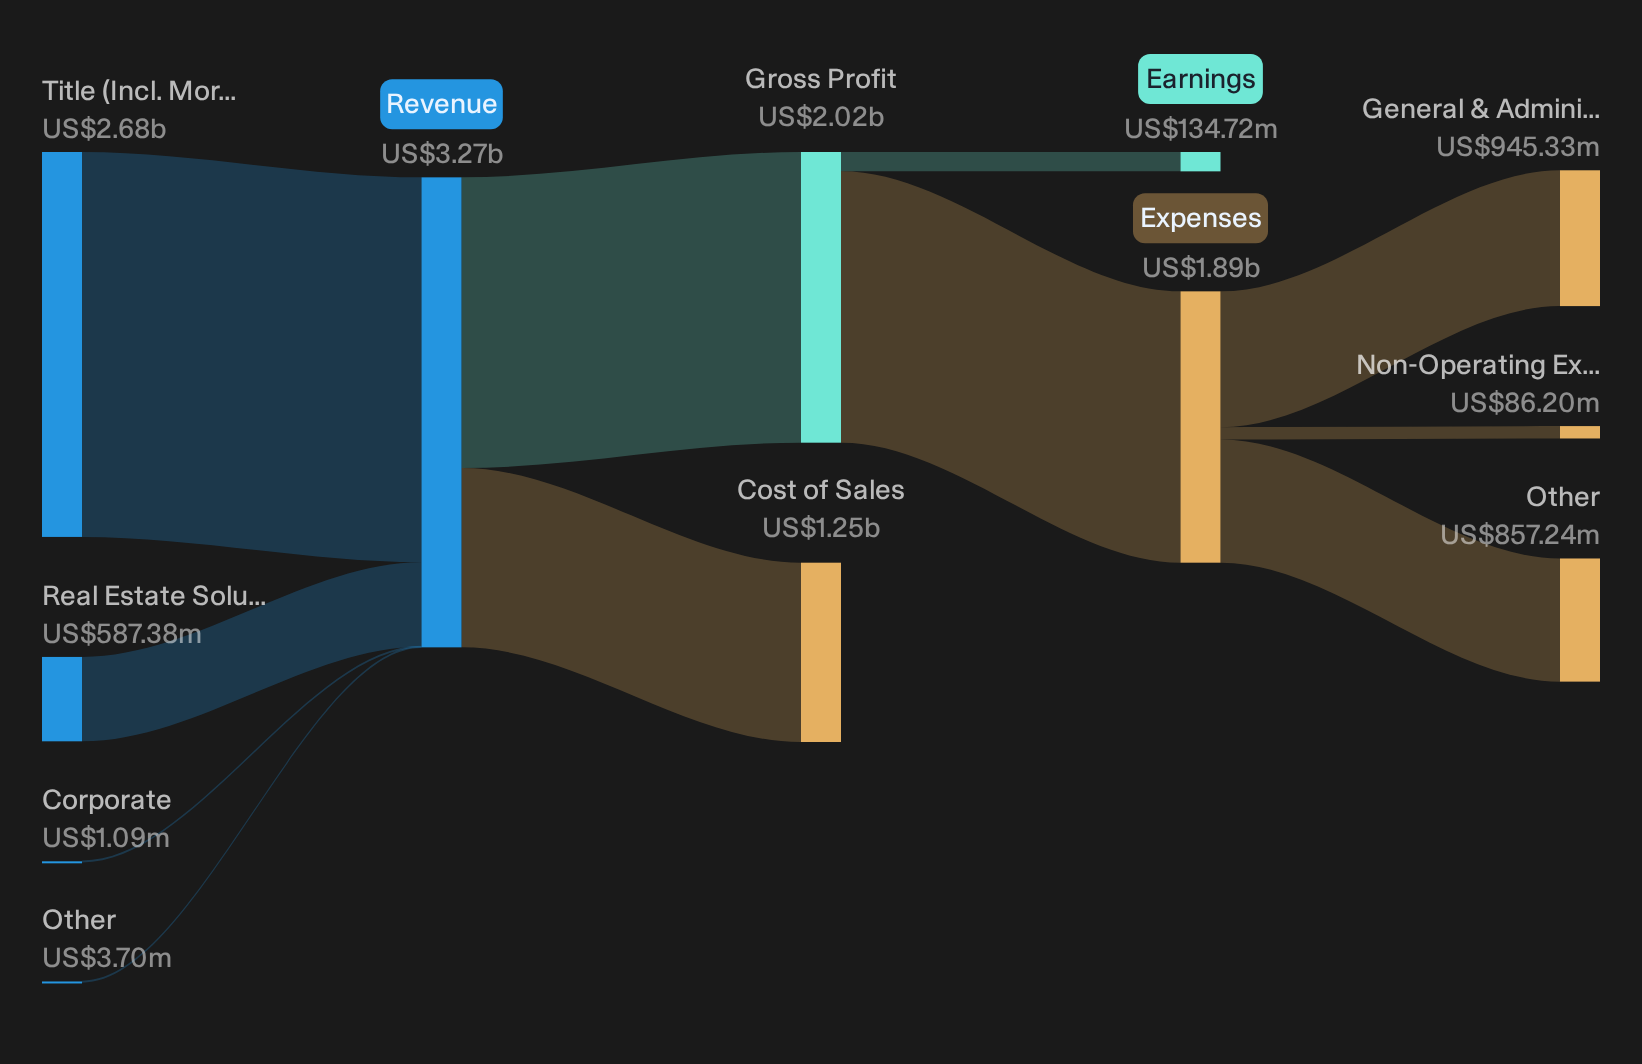
Operations: Stewart generates about US$2.7b from Title, US$587 million from Real Estate Solutions, and US$1.1 million from Corporate, mostly in the United States.
Market Cap: US$2.0b
Within a financials screen built around balance sheet strength and dividends, Stewart Information Services adds a real estate transaction angle that still links back to the higher-rate conversation through its investment float and title insurance operations.
"The Virtual Underwriter platform now offers improved search tools to help users locate manuals, bulletins, and reference materials more quickly."
What happens if one unseen cost pressure moves differently from what the market currently assumes for Stewart Information Services?
If that invisible cost line really is decoupling from expectations, read the full narrative for Stewart Information Services to see what could be masking Stewart Information Services’ next phase.
Marsh & McLennan Companies (MRSH)
Overview: Marsh & McLennan Companies is a global insurance broker and consulting group that helps clients manage risk, insurance costs, and workforce challenges.
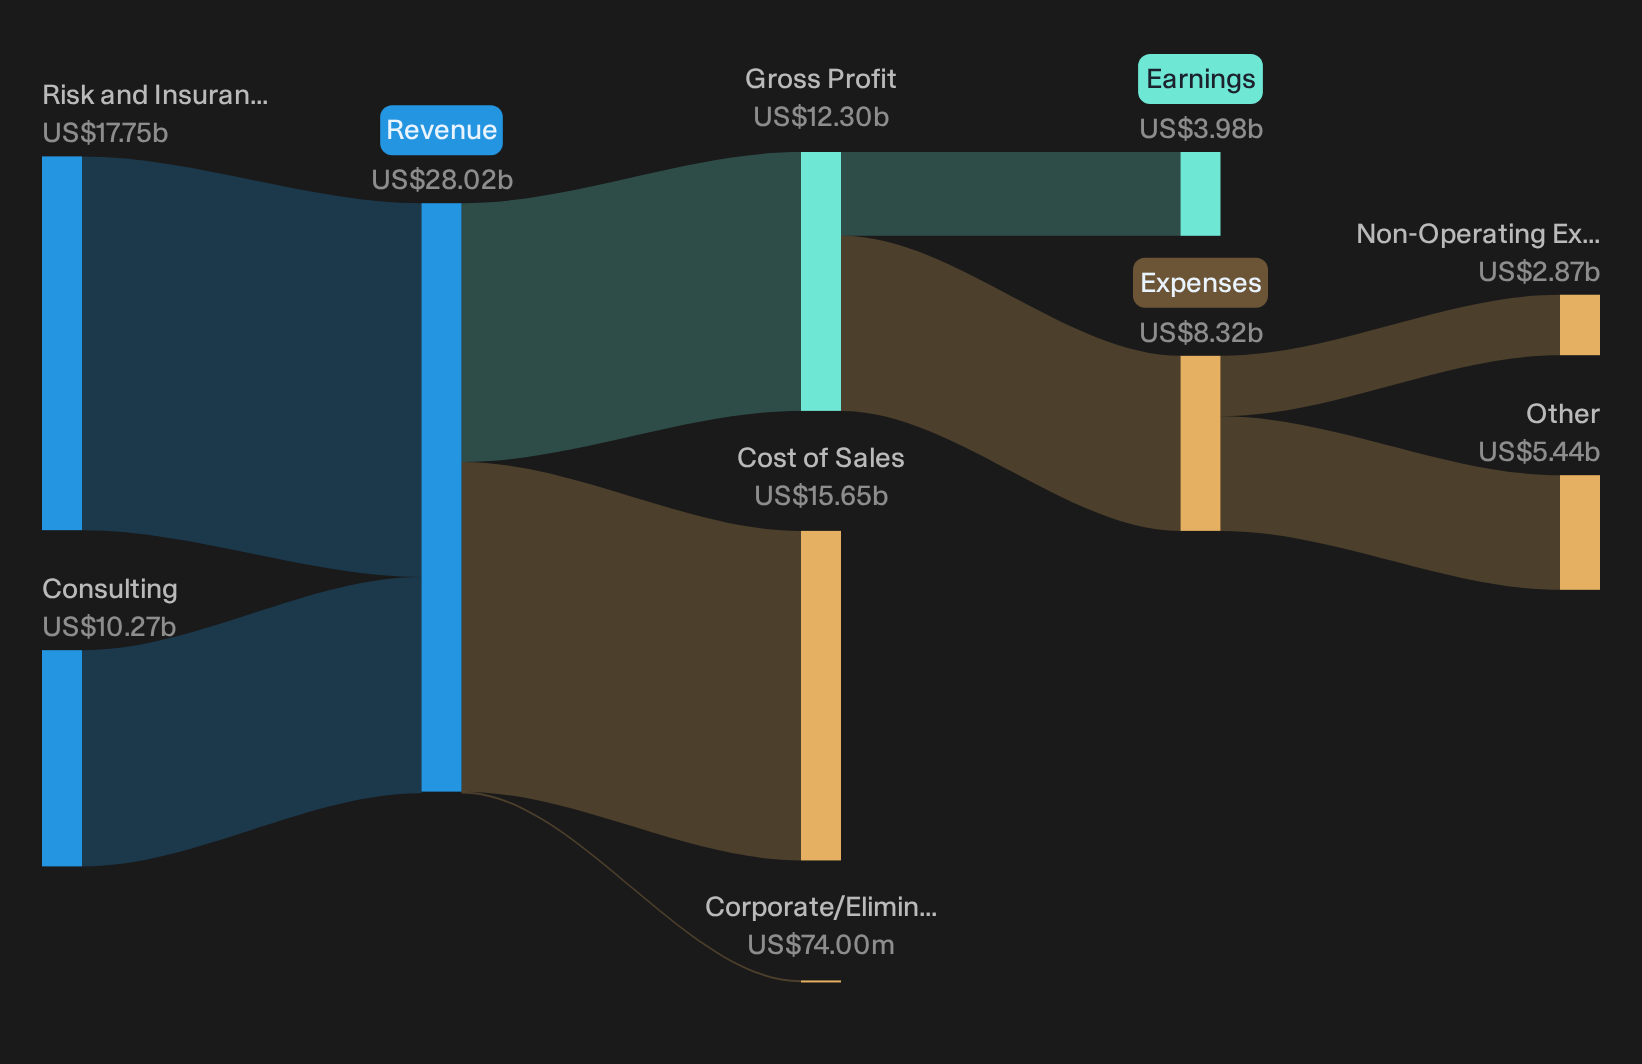
Operations: Marsh & McLennan Companies generates about US$17.8b from Risk and Insurance Services, offset by Corporate, and US$10.3b from Consulting.
Market Cap: US$86.1b
Marsh & McLennan Companies sits right where this screener points you, a large adviser and broker whose fees and investment income are closely tied to how global insurers price risk and earn returns in a higher-rate world.
"Rising global risk complexity, including increased litigation, extreme weather, catastrophic events, cyber threats, and evolving AI risks, is expected to drive higher demand for Marsh & McLennan's specialized risk advisory and brokerage services, supporting long-term fee revenue and new client growth."
What happens to Marsh & McLennan’s margins if one key assumption about how clients absorb and price those rising risks quietly starts to break?
If that pricing assumption really is starting to bend, read the full narrative for Marsh & McLennan Companies to see how Marsh & McLennan could turn rising complexity into accelerating earnings power.
Willis Towers Watson (WTW)
Overview: Willis Towers Watson is a global advisory and insurance broking group that helps clients manage risk, benefits, and retirement plans.
Operations: Willis Towers Watson generates about US$5.4b from Health, Wealth & Career, US$4.5b from Risk & Broking, with revenue spread across the U.S., U.K., and other markets.
Market Cap: US$30.1b
Willis Towers Watson ties neatly into this financials screen as a large insurance-focused adviser. Its fee income and investment-related work sit close to how higher-for-longer rates ripple through risk markets.
"Increasing adoption and deployment of AI-powered analytics, digital platforms, and automation tools is set to further enhance productivity and enable scalable solutions, improving operating leverage and underpinning ongoing operating margin expansion."
The real swing factor now is how one less visible shift in client demand and pricing power ultimately feeds through to those margins.
That margin swing is the crux, and the full narrative for Willis Towers Watson lays out how Willis Towers Watson could turn that shift into accelerating, underappreciated earnings power.

Seeking Fresh Alternatives Before They Fly
Fresh ideas move first, and the sharpest breakouts often get caught early while the crowd hesitates. Scan curated lists now, while it matters, and get in early.
- Target steadier paydays by reviewing income plays highlighted in the 6 dividend fortresses before yields drop and the search for reliable cash flow gets crowded.
- Ride real momentum by scanning the 76 profitable AI stocks that aren't just burning cash before fast-moving AI leaders stop flying under the radar and valuations fully reflect their earnings profiles.
- Secure exposure to critical metals by checking the 28 best rare earth metal stocks while these producers remain under the radar for now and before demand stories dominate headlines.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com