
3 UK Auto Manufacturing Stocks Facing A Nissan Driven Investment Test
Nissan’s £170m push into a new hybrid SUV in Sunderland puts UK auto manufacturing back under the spotlight, with regulation now acting like a gatekeeper for fresh investment rather than a tailwind. For investors, that mix of capital spend, political pressure and “use it or lose it” plant capacity can quickly reshape expectations for UK Auto Manufacturing and Supply Chain stocks. This article walks through 3 companies most exposed to this story and why their fortunes could shift first.
The three stocks below are a useful starting sample, but the full screen on Simply Wall St surfaced 7 more UK auto manufacturing and supply chain companies with equally compelling narratives that are not covered here. To identify where your own conviction might be highest, head straight into the UK Auto Manufacturing and Supply Chain screener.
Aurrigo International (AIM:AURR)
Overview: Aurrigo International supplies electrical components for UK and European car makers, while also developing autonomous vehicles and software for airports.
Operations: The group generates about £5.4 million from Automotive Components and £2.6 million from Autonomous solutions, mostly across the UK and Europe.
Market Cap: £104 million
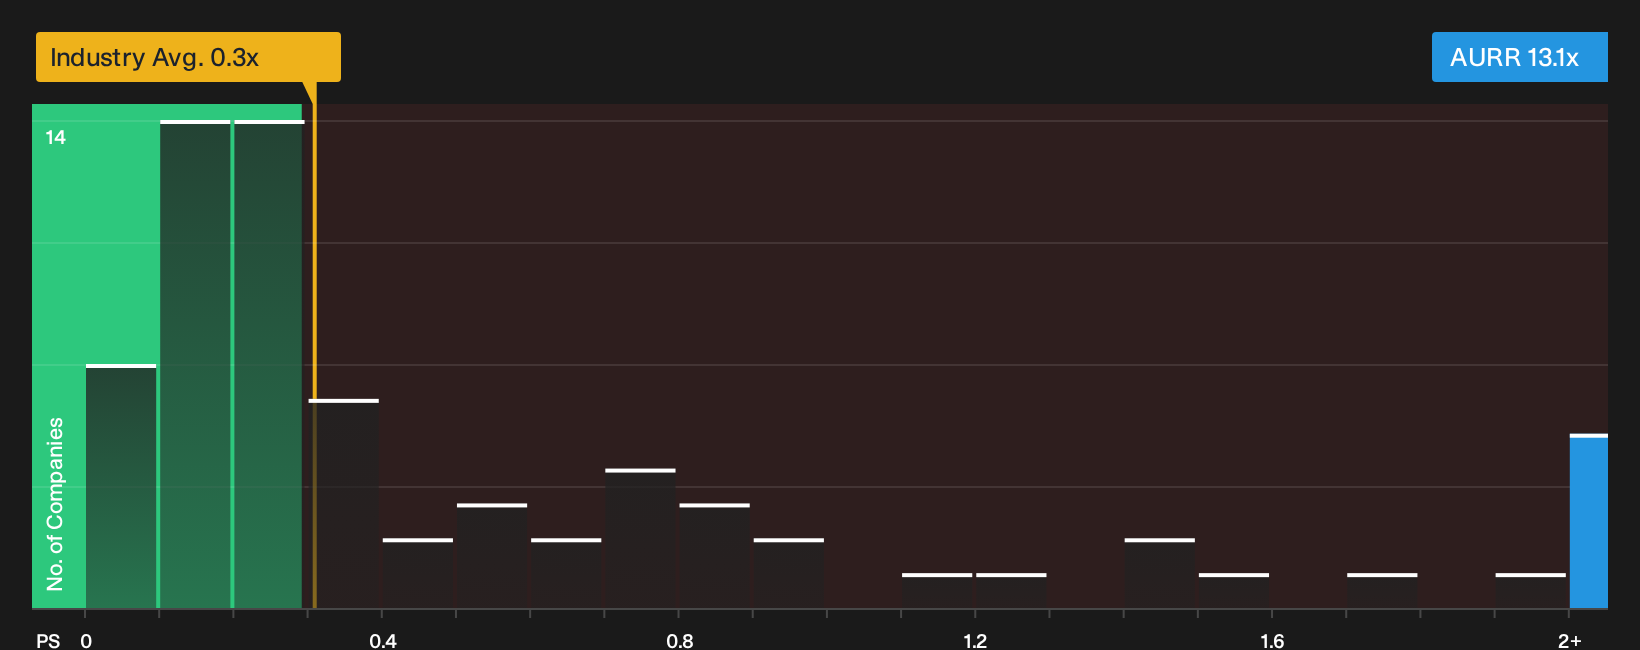
Aurrigo International ties directly into the UK Auto Manufacturing and Supply Chain theme through its Coventry-based automotive components business supplying hybrid and ICE platforms. Nissan’s conditional hybrid investment highlights how component volumes can hinge on regulatory outcomes. This is significant for a supplier that is still loss making and highly rated on P/S, particularly if an unforeseen factor affects demand visibility for its core UK customers.
If that demand visibility question is on your mind, go straight to the 1 key reward and 2 important warning signs (2 are major!) to see what might be masking or amplifying Aurrigo International’s opportunity.
CT Automotive Group (AIM:CTA)
Overview: CT Automotive Group designs and manufactures interior components and kinematic assemblies for global car makers, with operations closely linked to hybrid and ICE production volumes.
Operations: CT Automotive Group generates about $101 million from Production and $13 million from Tooling, selling into Europe, North America, the UK and Asia Pacific.
Market Cap: £24 million
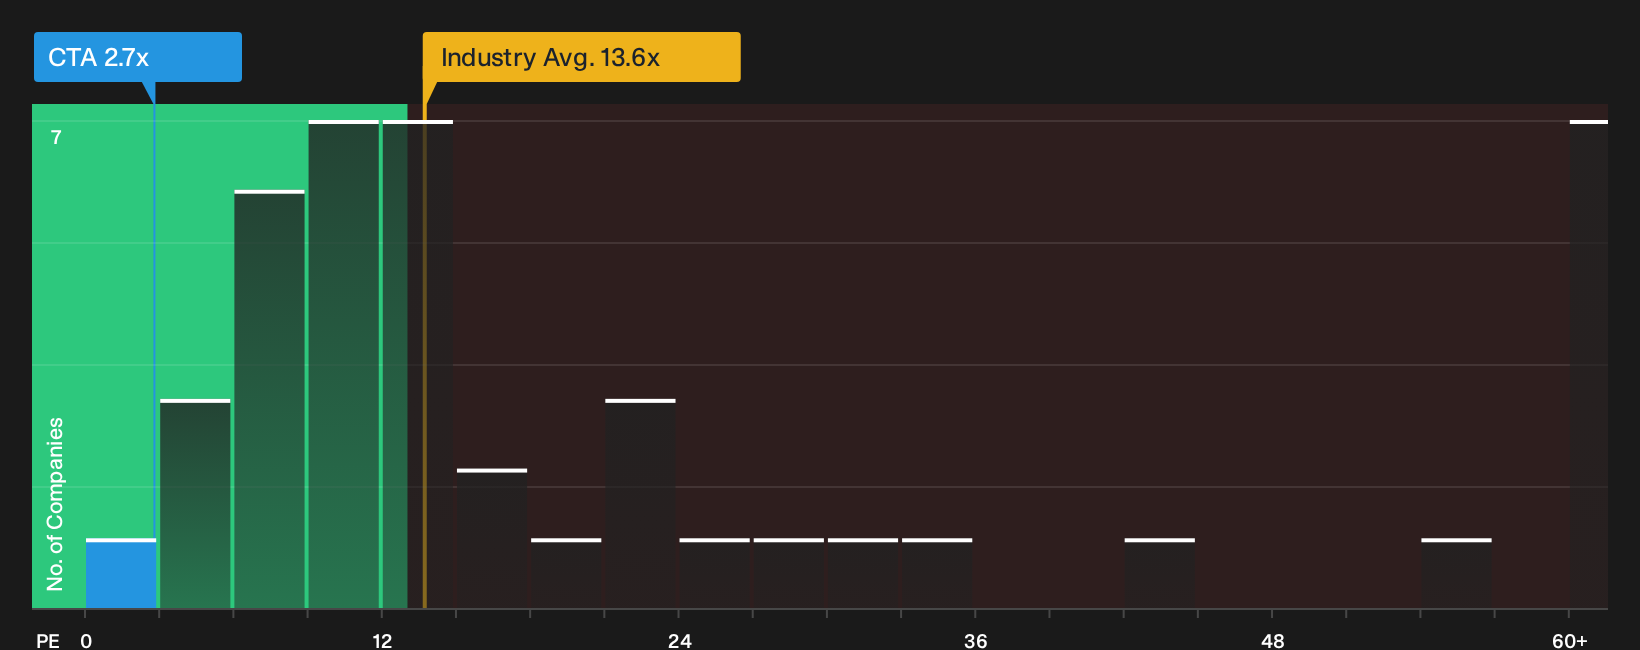
CT Automotive Group plugs directly into the UK Auto Manufacturing and Supply Chain theme through interior parts and tooling that go into hybrid and ICE models, including programs with Nissan. The stock combines high earnings quality metrics with a very low P/E. This makes the current valuation story heavily dependent on how one unseen pressure shapes future program economics and demand visibility.
That valuation tension makes it worth going straight to the 3 key rewards and 1 important warning sign to see what might be accelerating or stalling the next phase for CT Automotive Group.
Autins Group (AIM:AUTG)
Overview: Autins Group supplies UK made noise and vibration insulation materials for vehicle manufacturers, directly feeding into traditional hybrid and ICE production.
Operations: The business generates about £16.9 million from Automotive NVH and £0.7 million from Other segments, with £8.8 million from UK customers.
Market Cap: £7.1 million
Autins Group provides focused exposure to UK based automotive manufacturing through NVH materials that go into every finished car. Recent profitability and a forecast 19.22% revenue increase keep attention on whether one unresolved pressure ultimately tightens or relaxes the squeeze on its margins and order book.
That unresolved pressure is exactly what the analyst forecasts for Autins Group is built to unpack, so you can see where Autins Group’s story might be accelerating next.

Seeking Alternatives Before Momentum Flies
Fresh ideas tend to move first. By the time every investor notices a breakout, the most attractive entry points can be gone. Scan these under the radar themes now to explore potential opportunities earlier in the move.
- Target resilient payers that may help keep income streams aloft while prices move around by screening for 1 dividend fortresses, which have been carefully filtered for staying power.
- Look for under the radar growth stories before momentum builds further by reviewing 7 high quality undiscovered gems, curated for quality, balance sheet strength and potential operating flexibility while it matters.
- Track where earnings momentum could already be forming by scanning 76 profitable AI stocks that aren't just burning cash so you can focus on AI companies with cash flow supporting the story rather than hype alone.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com