
3 Cash Management Stocks Worth Watching As Rate Hike Odds Climb
Fed officials are hinting at tighter policy, inflation sits at 3.4%, and traders are assigning about a 92% chance to another rate hike. Money parked in corporate accounts suddenly matters a lot more. If you care where cash sleeps when borrowing costs rise, this is your moment. This article walks through three treasury and cash management stocks tied to that theme and explains why their setups may warrant a closer look today.
The sample of treasury and cash management specialists in this article is just a starting point, as the full screen surfaced 47 more U.S. banks and fintechs with equally compelling corporate cash narratives. If you want to move beyond a short list and start identifying your own highest conviction setups, head straight into the US Corporate Cash Management & Treasury Service Providers screener.
Bancorp (TBBK)
Bancorp plugs directly into the corporate cash theme through business accounts, payments, and sweep style services, while also leaning on fintech partnerships and specialty lending to round out a US focused model.
The Bancorp, Inc. is a US financial holding company offering business banking, payments, and cash management, with fintech activities contributing about US$263 million of revenue, real estate bridge lending around US$103 million, and a market value of roughly US$2.0 billion.
"The Fintech Solutions Group's addition of new partnerships and expansion of existing programs, particularly in credit sponsorship, is anticipated to drive significant increases in future earnings."
What happens to Bancorp’s earnings power if a single pressure on how those fintech driven cash flows translate into long term margins shifts?
If that pressure point is on your radar, read the full narrative for Bancorp to see whether Bancorp’s fintech engine is accelerating or quietly stalling.

Hope Bancorp (HOPE)
Hope Bancorp plugs directly into the corporate cash management theme through business deposits, payments, and treasury services. Its broader commercial and consumer banking franchise provides the lending and fee engine that makes those cash accounts meaningful in a rising rate cycle.
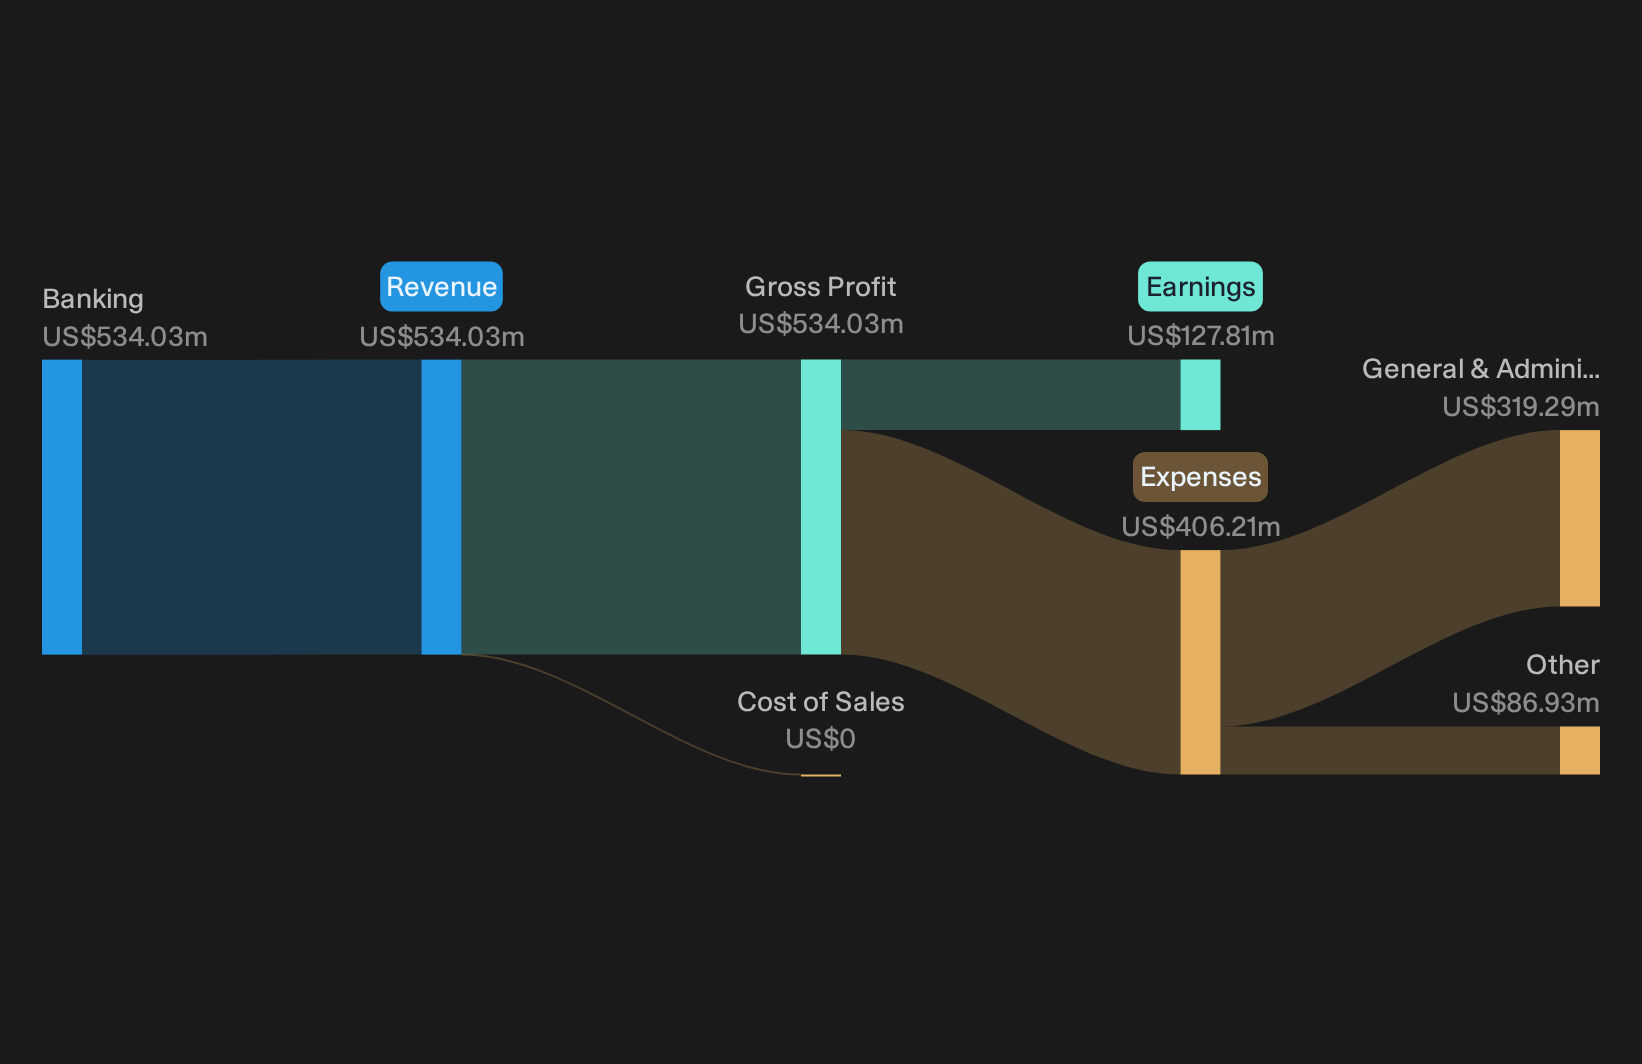
Hope Bancorp, Inc. is a Los Angeles based retail and commercial bank whose Bank of Hope unit earns about US$534 million from banking activities in the United States and carries a market value near US$1.8b.
"Significant ongoing investment in digital platform enhancements and fintech partnerships is poised to improve operational efficiency and customer retention, which could translate into a sustainably lower cost-to-income ratio and improved net margins over time."
What really moves the needle for Hope Bancorp now is how one less visible shift in its funding mix shapes those margin gains when rates climb.
That quiet shift in funding mix is the real story, and the full narrative for Hope Bancorp shows where Hope Bancorp’s earnings engine could be accelerating or quietly decoupling from peers.
Glacier Bancorp (GBCI)
Glacier Bancorp is effectively a treasury partner for small and mid-sized businesses and local authorities, running operating accounts, loans, and liquidity services across its Glacier Bank network. These activities generate about US$1.1b from banking services in the United States and support a market value near US$6.0b.
For investors focused on how higher rates feed through to corporate cash management income, Glacier Bancorp offers a relatively straightforward regional banking story. Small business operating accounts and public sector deposits sit alongside traditional lending, with digital upgrades quietly changing how those clients handle day to day cash.
"Investments in digital platforms, such as the new commercial loan system and enhanced treasury solutions, are improving operational efficiency, lowering cost-to-income ratios, and attracting younger, tech-savvy customers. These factors support higher net margins and scope for margin expansion over time."
The main issue now is how any shift in the balance between deposit pricing and loan repricing will influence where those margins ultimately settle.
That balance could be hiding Glacier Bancorp’s real earnings torque, and the full narrative for Glacier Bancorp shows whether deposit pricing is quietly masking a stronger long term story.

Seeking Fresh Alternatives Beyond Banks?
Fresh ideas move first. Breakout stories, new momentum, and under the radar stocks often get caught by early screeners while it matters. Do not get left chasing. Act now.
- Spot early momentum in lesser known growth stories before attention sends valuations flying by scanning the curated 16 high quality undiscovered gems.
- Target resilient cash generators that aim to keep paying out even when markets wobble by zeroing in on the hand picked 6 dividend fortresses.
- Ride structural demand for critical metals that power electrification and hardware upgrades by reviewing the focused 29 top copper producer stocks.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com