
How Investors May Respond To SSY Group (SEHK:2005) China Drug Approvals
- SSY Group secured past approvals from China’s National Medical Products Administration for Letermovir Injection and Diltiazem Hydrochloride Tablets, expanding its perioperative and cardiovascular treatment range using its existing strength in intravenous infusions.
- The combination of a CMV prevention therapy for transplant patients and a chronic cardiovascular medicine deepens SSY Group’s presence in high-acuity hospital settings, which can influence capacity utilization and product mix across its injectable portfolio.
- The next area of focus is how SSY Group's broader investment narrative could be shaped by these new Chinese drug approvals.
Scan beyond SSY Group and see how other hospital-focused drug producers are positioned by running the curated list of solid balance sheet and fundamentals (195 results) alongside this latest approval news.
What Is SSY Group's Investment Narrative?
To own SSY Group, you need to believe the hospital focused model can keep turning a broad infusion base into higher value therapies. The recent approvals for Letermovir Injection and Diltiazem Hydrochloride Tablets fit that story because they plug directly into existing perioperative and cardiovascular channels rather than requiring a new commercial build out. That matters for execution risk and capital intensity. The group already reports HK$4,378.9m of revenue and HK$507.5m of net profit, so these launches look like incremental contributors rather than near term game changers.
In the short term, the interesting question is whether these hospital drugs can support a better product mix in a business where earnings have declined 6.5% per year over 5 years and net margins compressed from 14.4% to 11.6%. Forecast profit growth of 15.7% a year and revenue growth of 9.4% assume decent demand and pricing power for exactly this kind of higher acuity product. The stock trades on a 15.5x P/E, above peer and industry averages, even though analyst coverage is thin and return on equity is described as low at 6.4%. That sets a bar for execution that these approvals need to help clear rather than just decorate the pipeline.
That said, there is a quieter issue in the background that could matter far more for SSY Group if ...
There's only one way to know the right time to buy, sell or hold SSY Group. Head to Simply Wall St's company report for the latest analysis of SSY Group's Fair Value.
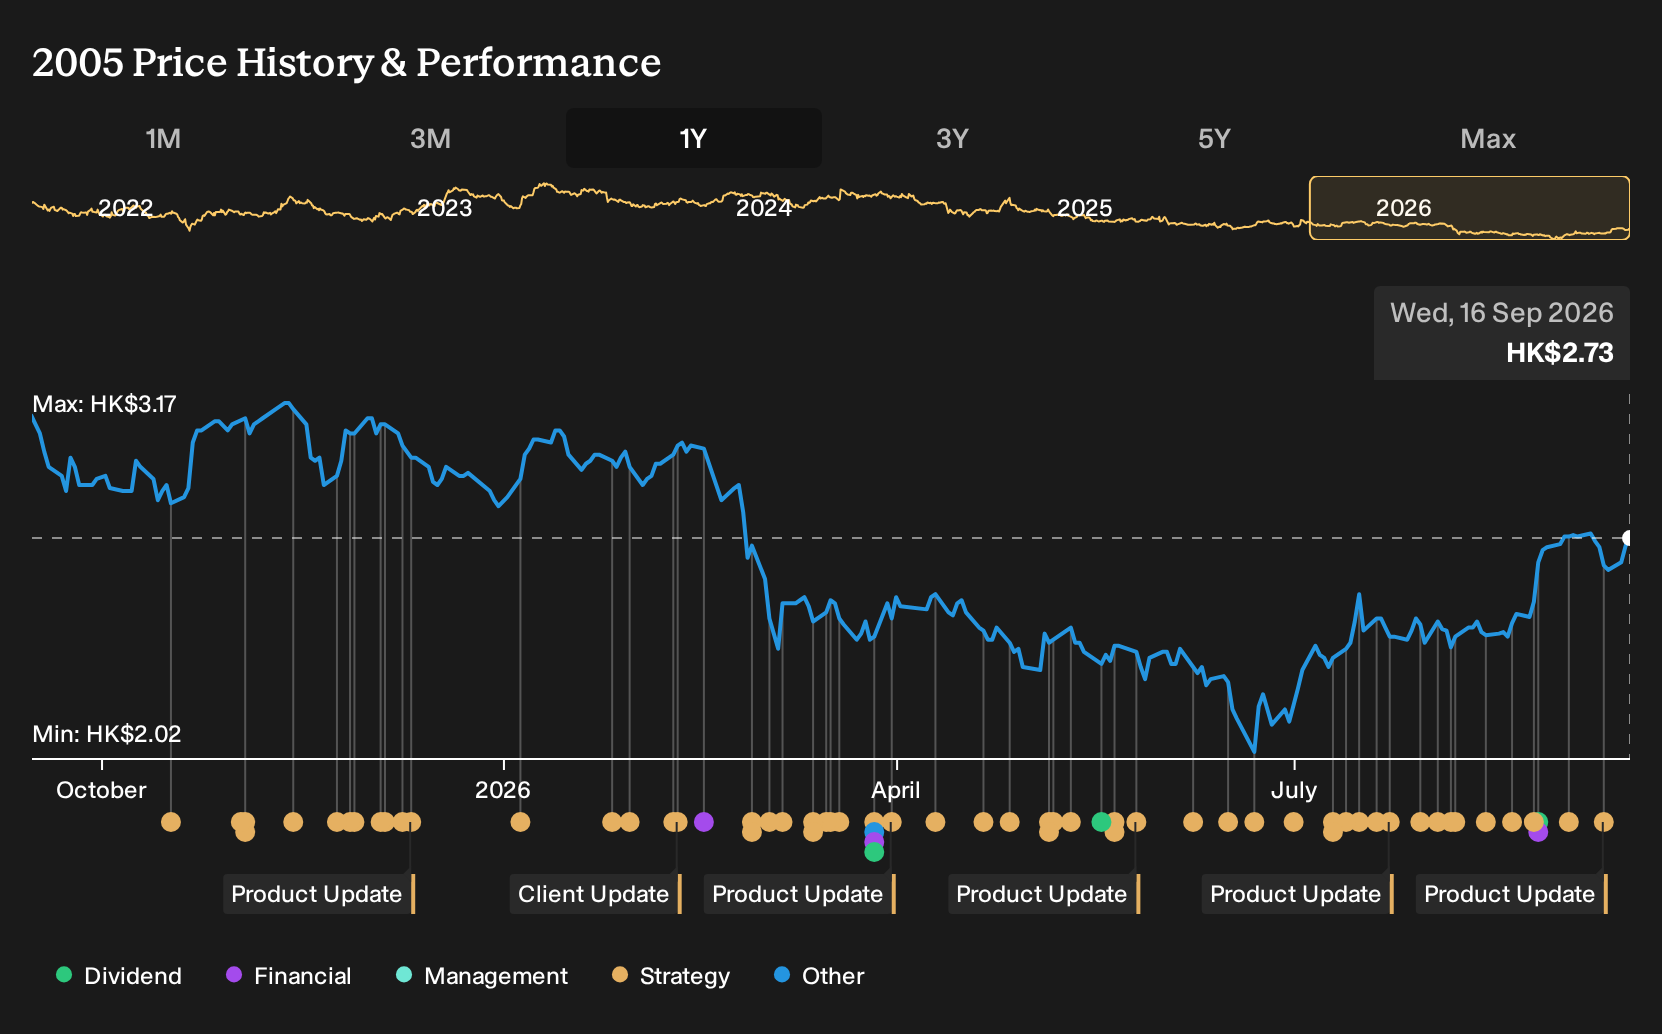
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community cluster tightly between HK$3.93 and HK$4.29, so retail views on SSY Group are narrow in price but still independent in method. These pre approval opinions sit alongside fresh CMV and cardiovascular clearances, which can change how you think about revenue mix and risk. Consider exploring several of these community viewpoints before forming your own stance.
Explore another SSY Group fair value estimate, including one that suggests it could be worth just HK$3.92!
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your SSY Group research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for SSY Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SSY Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond SSY Group?
If SSY Group is on your radar, it can help to compare it with other companies that match different risk and income profiles. Use the Simply Wall St Screener to line up multiple stocks side by side, then decide which mix best fits your own approach.
- If you prefer dependable balance sheets and cleaner financial profiles, start with a curated list of solid balance sheet and fundamentals (195 results) that meet strict quality and stability criteria.
- For investors focused on buying quality businesses at what may look like attractive prices, scan through a hand picked group of 192 high quality undervalued stocks that score well across fundamentals.
- If income is a priority and you want yield with substance behind it, review a focused set of 163 dividend fortresses that combine higher payouts with robust underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com