
Should LNG Supply Deals Require Action From Santos (ASX:STO) Investors?
- Santos Ltd has entered heads of agreement to supply LNG to South Korea's POSCO Steel for 10 years from around 2030 and to offtake about 1 million metric tons per year from Canada's proposed Ksi Lisims LNG project for up to 20 years, targeting Asian buyers.
- The combination of a long-term LNG sales deal and a separate Canadian offtake commitment provides Santos with additional flexibility regarding future supply sourcing, contract duration and market access in Asia.
- We will now examine how Santos' investment narrative could be influenced by these new long-term LNG supply and offtake commitments.
Scan Santos alongside other LNG exposed energy players by checking which stocks make the cut in our 38 power grid technology and infrastructure stocks.
Santos Investment Narrative Recap
To own Santos, you need to believe in a long-life LNG and gas business that can keep filling big projects like Barossa and Pikka with commercially viable buyers. The new POSCO supply heads of agreement and Ksi Lisims offtake deal fit that story by sketching out future demand in Asia, but they do not change the near term picture materially.
The key near term swing factor still sits with project execution and capital discipline on those large developments, especially given the pressure from decommissioning, remediation and ESG requirements. The biggest operational risk remains that high spend in politically and environmentally sensitive regions fails to translate into strong returns if pricing, regulation or demand move against Santos.
The Ksi Lisims LNG offtake heads of agreement looks most connected to the existing catalyst narrative. Santos has been leaning on long term LNG contracts to support revenue visibility, and this Canadian volume aimed at Asian customers lines up with that focus on contracted, oil linked LNG exposure through the next decade.
For investors, the interest is in how reliably Santos can turn these preliminary commitments into binding contracts that sit alongside Barossa, Pikka and its existing PNG position. Execution risk on a new supply chain, together with the long project timeline into the 2030s, means this agreement supports the story of future optionality rather than reshaping today’s earnings outlook or risk profile.
Santos' narrative projects $7.0b revenue and $1.7b earnings by 2029. This is based on 12.3% yearly revenue growth and roughly a 2.3x earnings increase from $734.0m today.
Uncover why Santos' fair value indicates Santos is roughly in line with its current price.
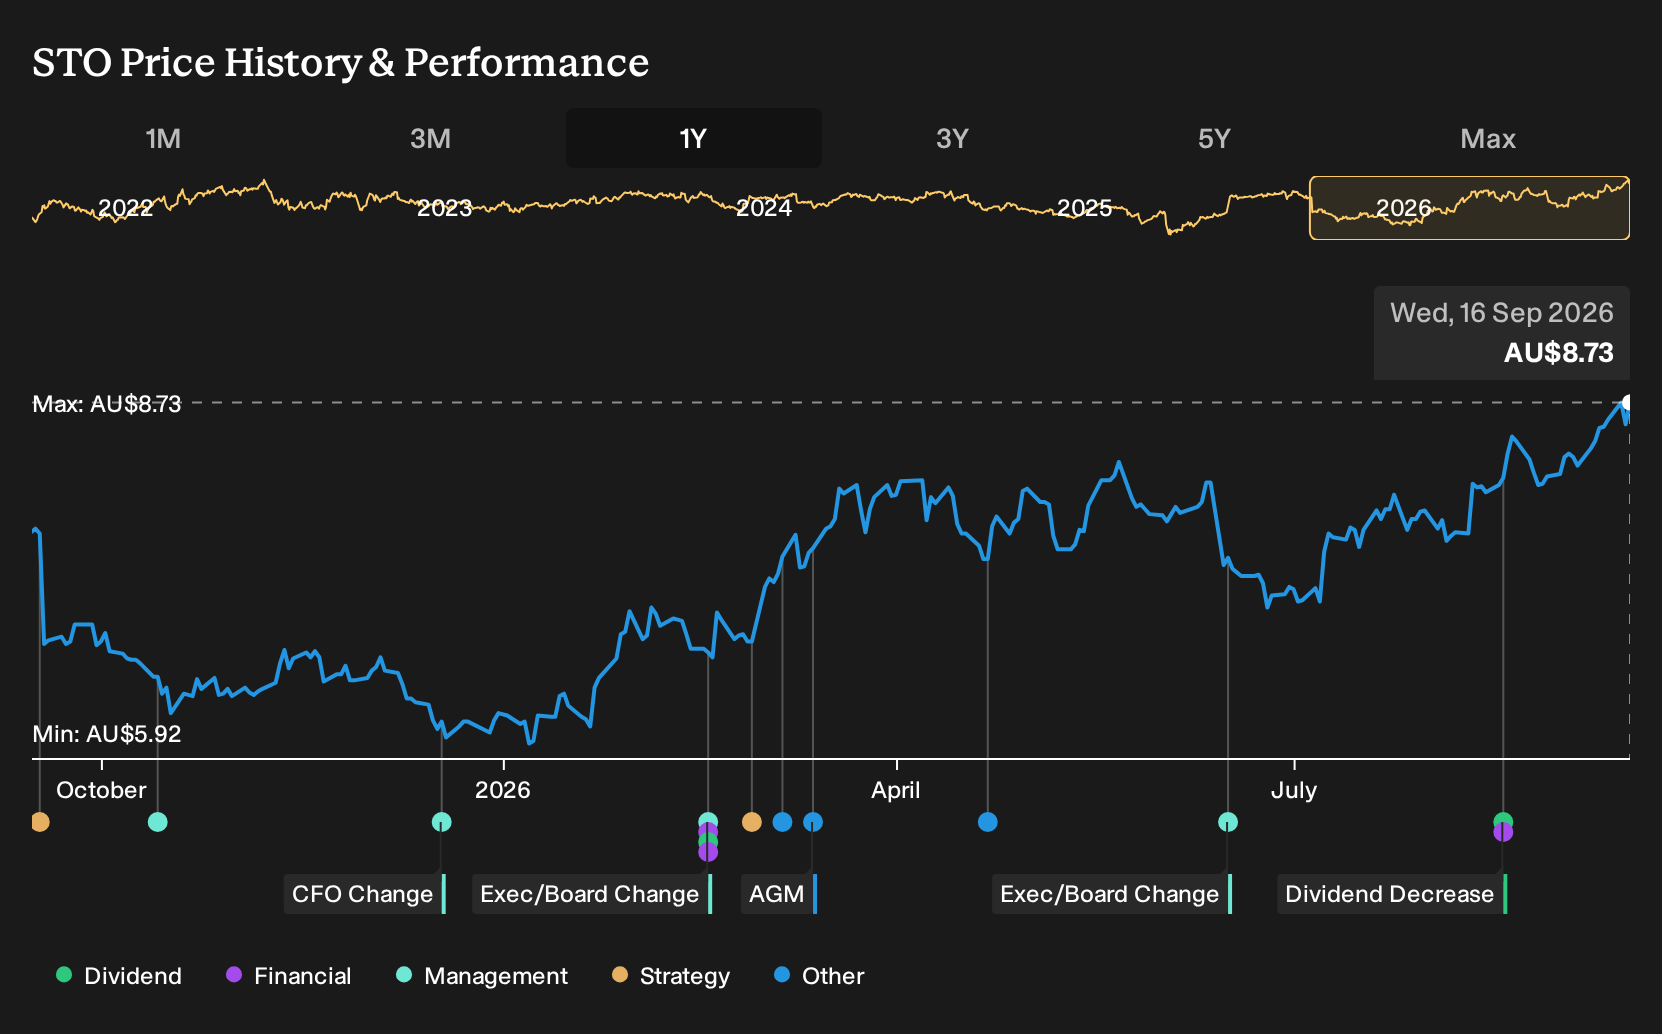
Exploring Other Perspectives
One alternative view on Santos leans heavily on project delay risk. In that narrative, slower ramp up at Barossa and Pikka keeps costs sticky and leaves 2029 earnings nearer $1.3b on about $6.6b of revenue. Those analysts sound more cautious than consensus, and this fresh LNG news could eventually shift that gap.
Explore 7 other Santos fair value estimates, including one that suggests as much as 11% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment outcomes rarely come from following the herd, so consider forming your own view.
- A great starting point for your Santos research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Santos. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to review Santos' overall financial position at a glance.
Looking For More Investment Ideas Beyond Santos?
If this Santos story has you thinking about portfolio construction more broadly, it can help to line it up against other opportunities with different risk and income profiles. The Simply Wall St Screener lets you do that quickly by filtering for the kind of businesses that fit your goals.
- For investors hunting for mispriced opportunities with solid fundamentals, compare Santos to a wider field of potential value ideas through our 5 high quality undervalued stocks.
- If income stability matters more to you than growth, take a look at companies built around reliable cash returns by reviewing our 4 dividend fortresses.
- When capital preservation and balance sheet strength come first, focus on financially resilient businesses via our 3 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com