
Are Half Year Earnings Altering The Investment Case For D'Ieteren Group (ENXTBR:DIE)?
- D'Ieteren Group reported half year 2026 sales of €3,930.6 million and net income of €256.9 million, alongside higher basic and diluted earnings per share from continuing operations compared with the prior year period.
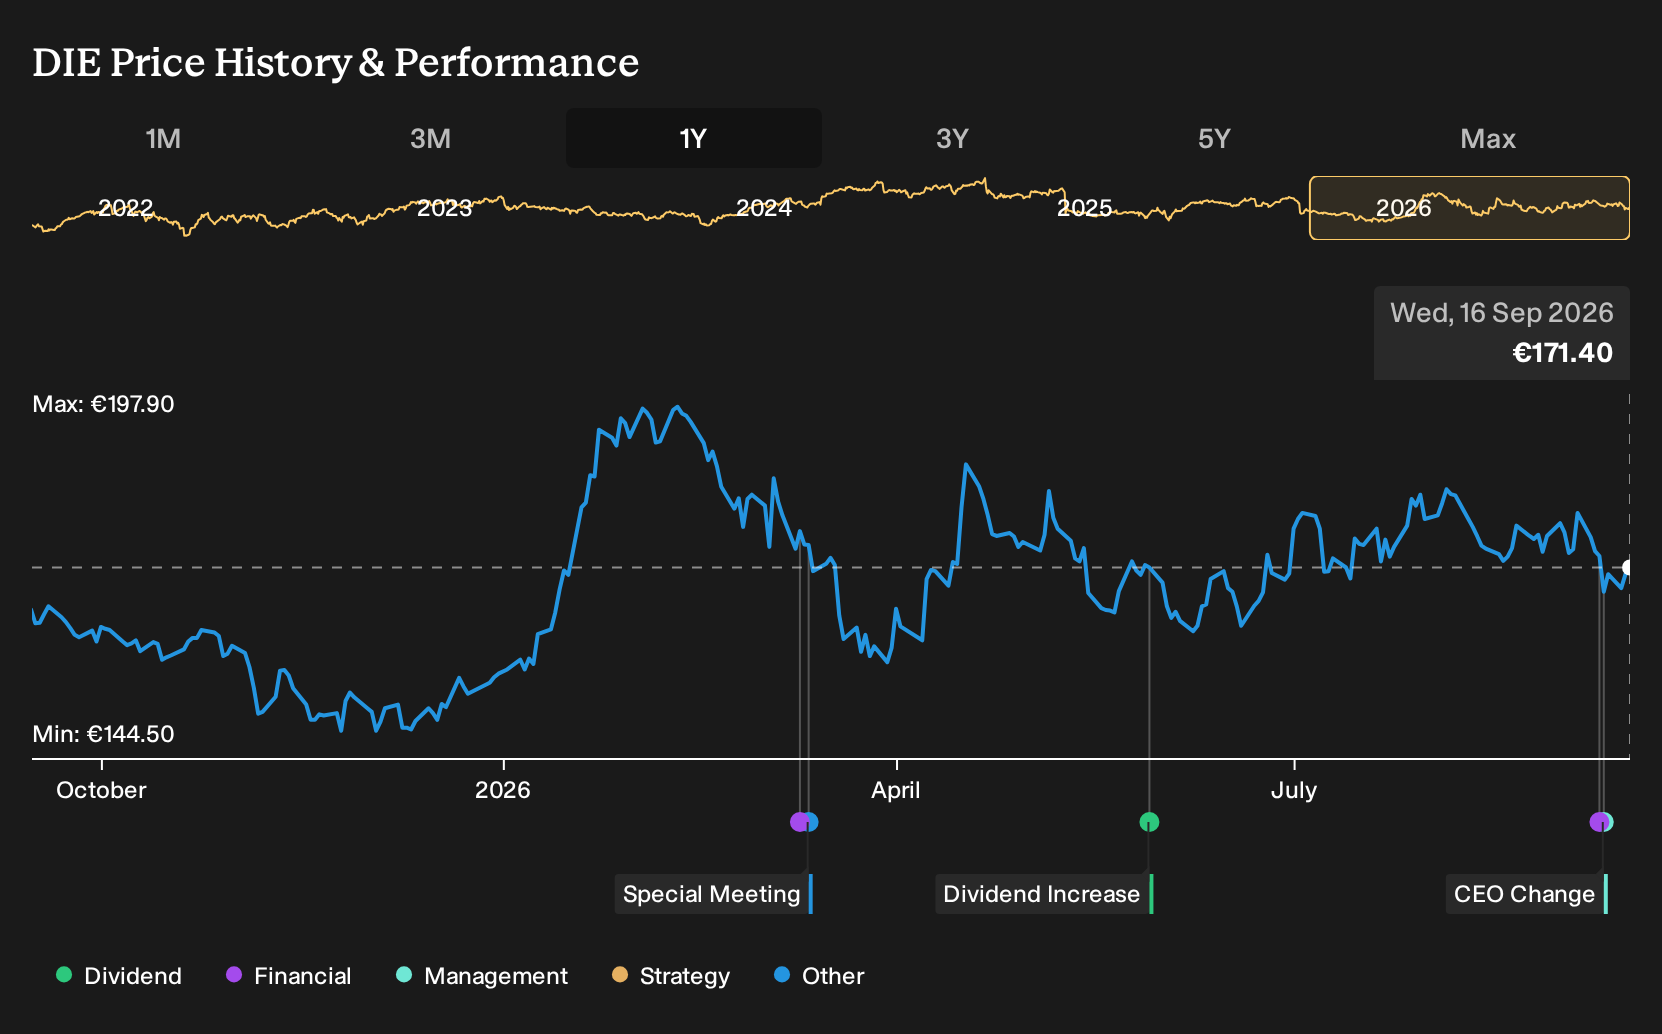
- The company also confirmed a CEO transition, with Eric Machiels, who has investment and operational experience at OMERS and Infinis Energy, set to succeed Francis Deprez from December. This development may reshape how investors think about capital allocation and execution priorities.
- Next, the focus will be on how D'Ieteren Group's stronger profitability, highlighted by higher EPS, interacts with its evolving leadership narrative.
Scan how D'Ieteren Group compares with other established businesses where earnings quality and balance sheets do the heavy lifting through our hand picked list of solid balance sheet and fundamentals (195 results).
What Is D'Ieteren Group's Investment Narrative?
D'Ieteren Group appeals to investors who prefer diversified, cash generative platforms where earnings quality and balance sheet discipline matter more than headline revenue growth. Investors are essentially backing a holding structure with exposure to automotive distribution, vehicle glass services, aftermarket parts and Moleskine, plus a record of using capital to build these positions. The recent half year numbers, with €3,930.6m of sales and €256.9m of net income, indicate profit resilience even as revenue fluctuates. Higher EPS from continuing operations aligns with a story in which earnings contribute more than top line expansion.
The near term focus is on execution. New CEO Eric Machiels brings an investment background from OMERS and prior operational experience at Infinis Energy, which is relevant for a group that acts as both an operator and an allocator. Investors already need to consider high debt and the effect of large one off items on reported figures, alongside a P/E of 20.8x that sits above retail distributor peers while analysts still see upside with a 36.6% gap to their average target. If Machiels emphasizes more disciplined capital deployment and clearer segment priorities, the current leadership change could become part of the catalysts set rather than a distraction.
However, there is one structural vulnerability in D'Ieteren Group's story that rarely makes it past the headline valuation debate...
There's only one way to know the right time to buy, sell or hold D'Ieteren Group. Head to Simply Wall St's company report for the latest analysis of D'Ieteren Group's Fair Value.
Exploring Other Perspectives
D'Ieteren Group already draws four different fair value views from the Simply Wall St Community, with estimates clustered between €160.78 and €234.08. That spread reflects how widely opinions can differ. Fresh half year results and the upcoming CEO change in December give you clear reasons to revisit those assumptions and test several competing angles.
Explore 3 other D'Ieteren Group fair value estimates, including one that suggests potential upside of up to 37% from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your D'Ieteren Group research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for D'Ieteren Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate D'Ieteren Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond D'Ieteren Group?
Once the D'Ieteren Group story is on your radar, it often helps to compare it with other listed businesses that share traits you care about, whether that is resilience, income, or overlooked potential. The Simply Wall St Screener can help you filter the wider market so you are not just reacting to headlines but working from a watchlist that actually fits your style.
- If capital preservation is high on your list, focus on companies that pair steady fundamentals with lower risk profiles through a 103 resilient stocks with low risk scores.
- For investors who want income to do more of the work, scan for robust payers and potential 163 dividend fortresses that might complement a holding like D'Ieteren Group.
- If you enjoy finding stories before they are widely discussed, look across a 618 high quality undiscovered gems that combine solid balance sheets with room for the thesis to mature.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com