
Class Action Lawsuits Could Be A Game Changer For Alibaba Stock (BABA)
- Alibaba Group Holding is facing a series of U.S. securities class actions and law firm investigations that claim misleading disclosures around its ties to Chinese authorities, its inclusion on a U.S. Department of Defense list of Chinese military companies, and alleged AI related misconduct.
- The wave of litigation concentrates investor attention on Alibaba's governance, disclosure quality, and potential constraints on its AI and cloud ambitions, which are central to its long term spending plans.
- We will now look at how Alibaba's investment narrative compares with rising legal scrutiny over its alleged affiliation with Chinese authorities.
Alibaba Group Holding Investment Narrative Recap
For Alibaba Group Holding, the long term belief still rests on its ability to turn heavy AI, cloud, and quick commerce spending into healthier profit margins over time. The recent wave of U.S. class actions and investigations adds another layer of uncertainty around disclosure practices and potential constraints on AI projects, which already carry high capital needs. The main short term catalyst remains execution in AI and cloud, with the biggest current risk coming from margin pressure, legal overhang, and any limits those claims might place on key technology partnerships.
Higher U.S. interest rates, if the Federal Reserve follows through, also matter for Alibaba because they tend to weigh on consumer discretionary spending and risk appetite for cross border e commerce groups. That backdrop can dull enthusiasm around near term earnings, even as Alibaba continues to commit large sums to AI and cloud and contends with class action timelines that could absorb management attention and introduce further headline risk.
The most relevant recent development for this legal narrative is the series of class action filings and reminders, including the Bernstein Liebhard LLP notice of an October 5, 2026 lead plaintiff deadline. Those suits accuse Alibaba of misleading statements about business operations, growth prospects, financial stability, and ties to Chinese authorities, and they reference alleged AI model misuse. For you as a shareholder or prospective investor, the key issue is less the courtroom detail and more how prolonged legal scrutiny interacts with ongoing heavy capital spending and already compressed margins.
Legal processes can be slow. As a result, uncertainty could sit over Alibaba while it is investing RMB 380b in AI and cloud and RMB 50b in consumption platform upgrades. That combination keeps the focus firmly on cash generation, disclosure quality, and access to advanced AI hardware and partnerships at a time when U.S. export controls and defense lists are in play. The catalyst remains operational proof that these outlays can support durable earnings, while the risk is that regulatory and legal friction interrupt that path or increase compliance and funding costs.
Alibaba Group Holding Consensus Forecasts Under Legal Scrutiny
Alibaba Group Holding's narrative projects CN¥1,487.6b revenue and CN¥176.3b earnings by 2029, based on analyst assumptions of 12.5% yearly top line growth and a rise in profit margins from 7.0% today. That view implies an earnings increase of roughly CN¥103.0b from current earnings of CN¥73.3b.
Uncover why Alibaba Group Holding's fair value indicates a 71% potential upside to its current price, which could narrow quickly.
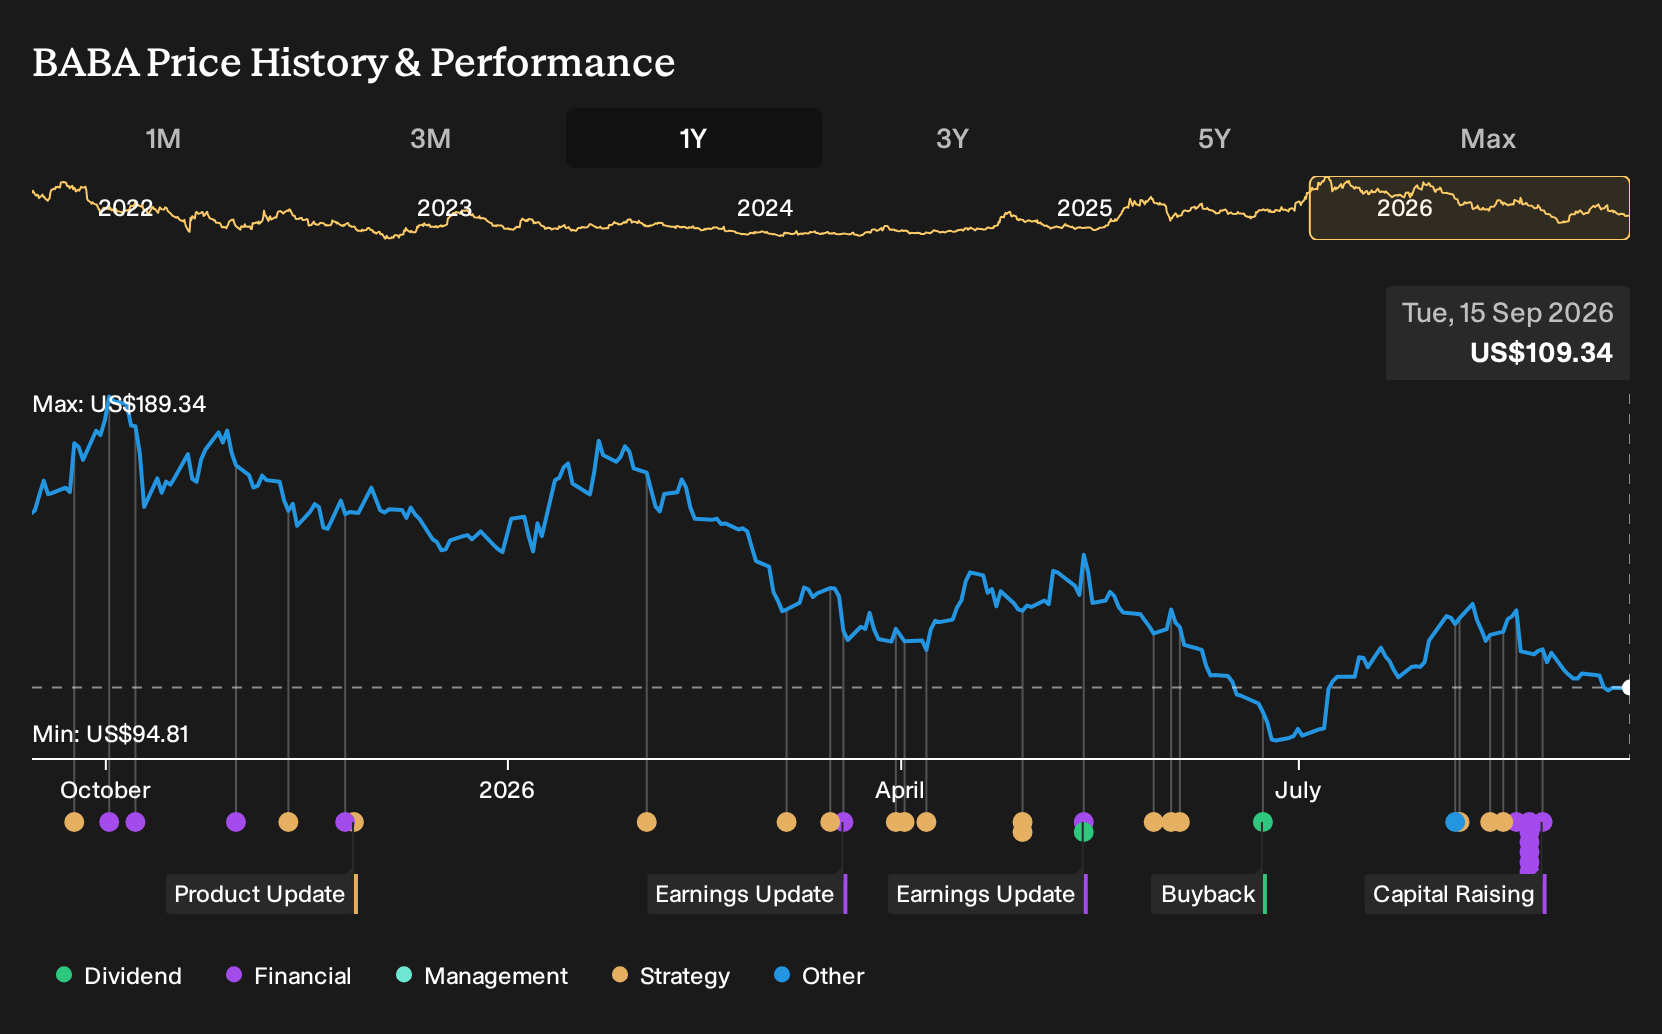
Exploring Other Perspectives
Some of the most optimistic analysts focus on Alibaba Group Holding's AI cloud traction as a counterweight to the legal headlines you are watching now. Before this news, the bullish camp was sketching out CN¥1,687.4b of 2029 revenue and CN¥362.0b of earnings. Your task is to decide whether those pre news assumptions still feel realistic, or whether this legal pressure and higher U.S. rates could push that story closer to the more cautious CN¥1,487.6b and CN¥176.3b path.
Explore 22 other Alibaba Group Holding fair value estimates, including one that suggests as much as 132% upside from the current price!
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Alibaba Group Holding research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Alibaba Group Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Alibaba Group Holding's overall financial health at a glance.
Looking For More Investment Ideas Beyond Alibaba Group Holding?
If this legal and AI story around Alibaba Group Holding has you rethinking concentration risk, it can help to widen the lens and compare it with other businesses that have different balance sheet strength, cash flow profiles, or income potential.
- For investors who care most about resilience and capital preservation, start with a curated 11 resilient stocks with low risk scores that focuses on relatively stable risk profiles while still leaving room for sentiment shifts.
- If dependable income matters more to you than headline growth, scan a handpicked set of 6 dividend fortresses that may suit a portfolio built around regular payouts.
- When you want quality fundamentals without the crowd already piling in, review a focused group of 16 high quality undiscovered gems that highlight less-followed businesses with stronger underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com