
Akamai (AKAM) Stock Seems About Right After Fresh Cloud Momentum
Akamai Technologies has had a choppy stretch on the market over the past few months, yet the share price is still well above where it was a year ago. That mix of recent weakness and longer term gains raises a straightforward question for investors who follow Akamai Technologies: whether today's valuation is adequately supported by the earnings power of the business.
- The stock has gained 38.0% over the past year, which puts real pressure on the current earnings profile to justify where the share price now sits.
- Growth in Akamai's cloud infrastructure and security offerings, alongside higher capital spending needs, can influence future profitability and the earnings base that investors are effectively paying for today.
- There is a second opinion on Akamai Technologies worth weighing. See what analysts think Akamai Technologies's shares could be worth.
The issue now is whether Akamai Technologies' current share price fairly reflects what its earnings suggest the business is worth.
If you are weighing Akamai Technologies against other earnings driven opportunities in similar territory, it can help to compare it with 60 AI infrastructure stocks.
Where Does Akamai Technologies Sit on Earnings?
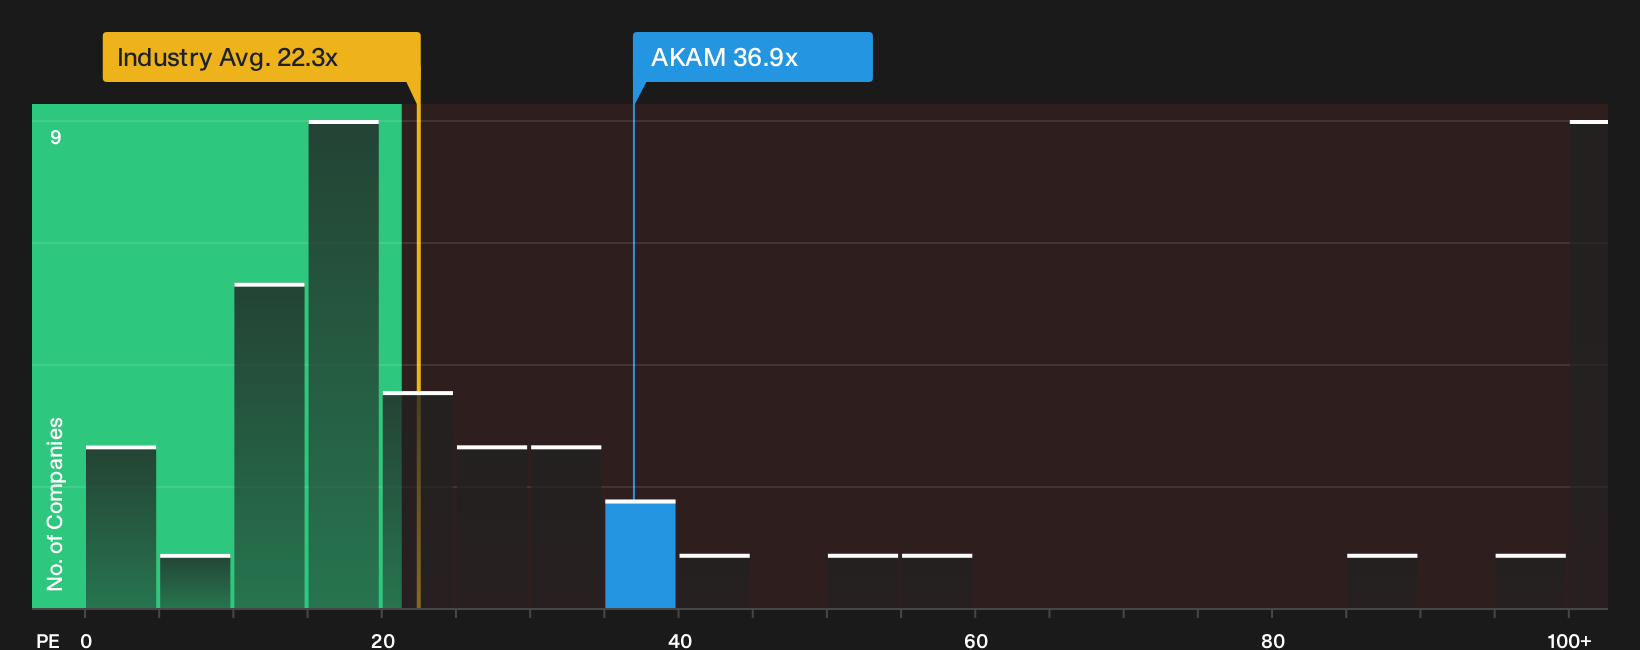
The P/E ratio works well for Akamai Technologies because earnings still sit at the centre of how investors are framing the business. On this metric, the stock trades at about 36.9x earnings, compared with an IT industry average near 22.3x and a peer group around 54.3x. That leaves Akamai at a clear premium to the wider sector while still pricing below many closer competitors in cloud and security infrastructure.
The fair multiple implied by a more tailored model, which blends Akamai Technologies' growth outlook, profitability, size and risk profile, is slightly under the current P/E. Recent commentary around cloud deals and higher capital spending suggests investors are already baking in meaningful expectations, and the present P/E reflects that optimism without stretching far beyond what the modelling implies. Because the P/E is only modestly above that tailored benchmark despite upbeat headlines about contract wins and cloud momentum, the shares come across as broadly about right on this earnings yardstick. Explore the numbers behind Akamai Technologies's P/E valuation.
The Akamai Technologies Narrative: What Would Justify Today's Price?
Narratives for Akamai Technologies pick up where this valuation puzzle leaves off by explaining which paths for growth, profitability and earnings would need to occur for the stock to be worth meaningfully more or less than today. Each view on Akamai Technologies' future presents a fair value as a thesis that can be monitored over time rather than treated as a one-off snapshot, and these are available on Simply Wall St's Community page.
One of the top community narratives on Akamai Technologies: 31% undervalued
"Rampant growth in data consumption, driven by AI powered applications, video, and real time use cases, is creating strong demand for Akamai's cloud infrastructure and edge compute offerings..."
Discover why this Narrative puts Akamai Technologies at 31% undervalued.
The Akamai Technologies share price is only one piece of the decision
Valuation work can look tidy on paper, yet research on Akamai Technologies also highlights specific risk checks that could change how you weigh everything you have just read. Take a closer look at 1 major warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com