
Despite Robust Growth, CoreWeave Remains Unattractive on Leveraging and Margin Contraction
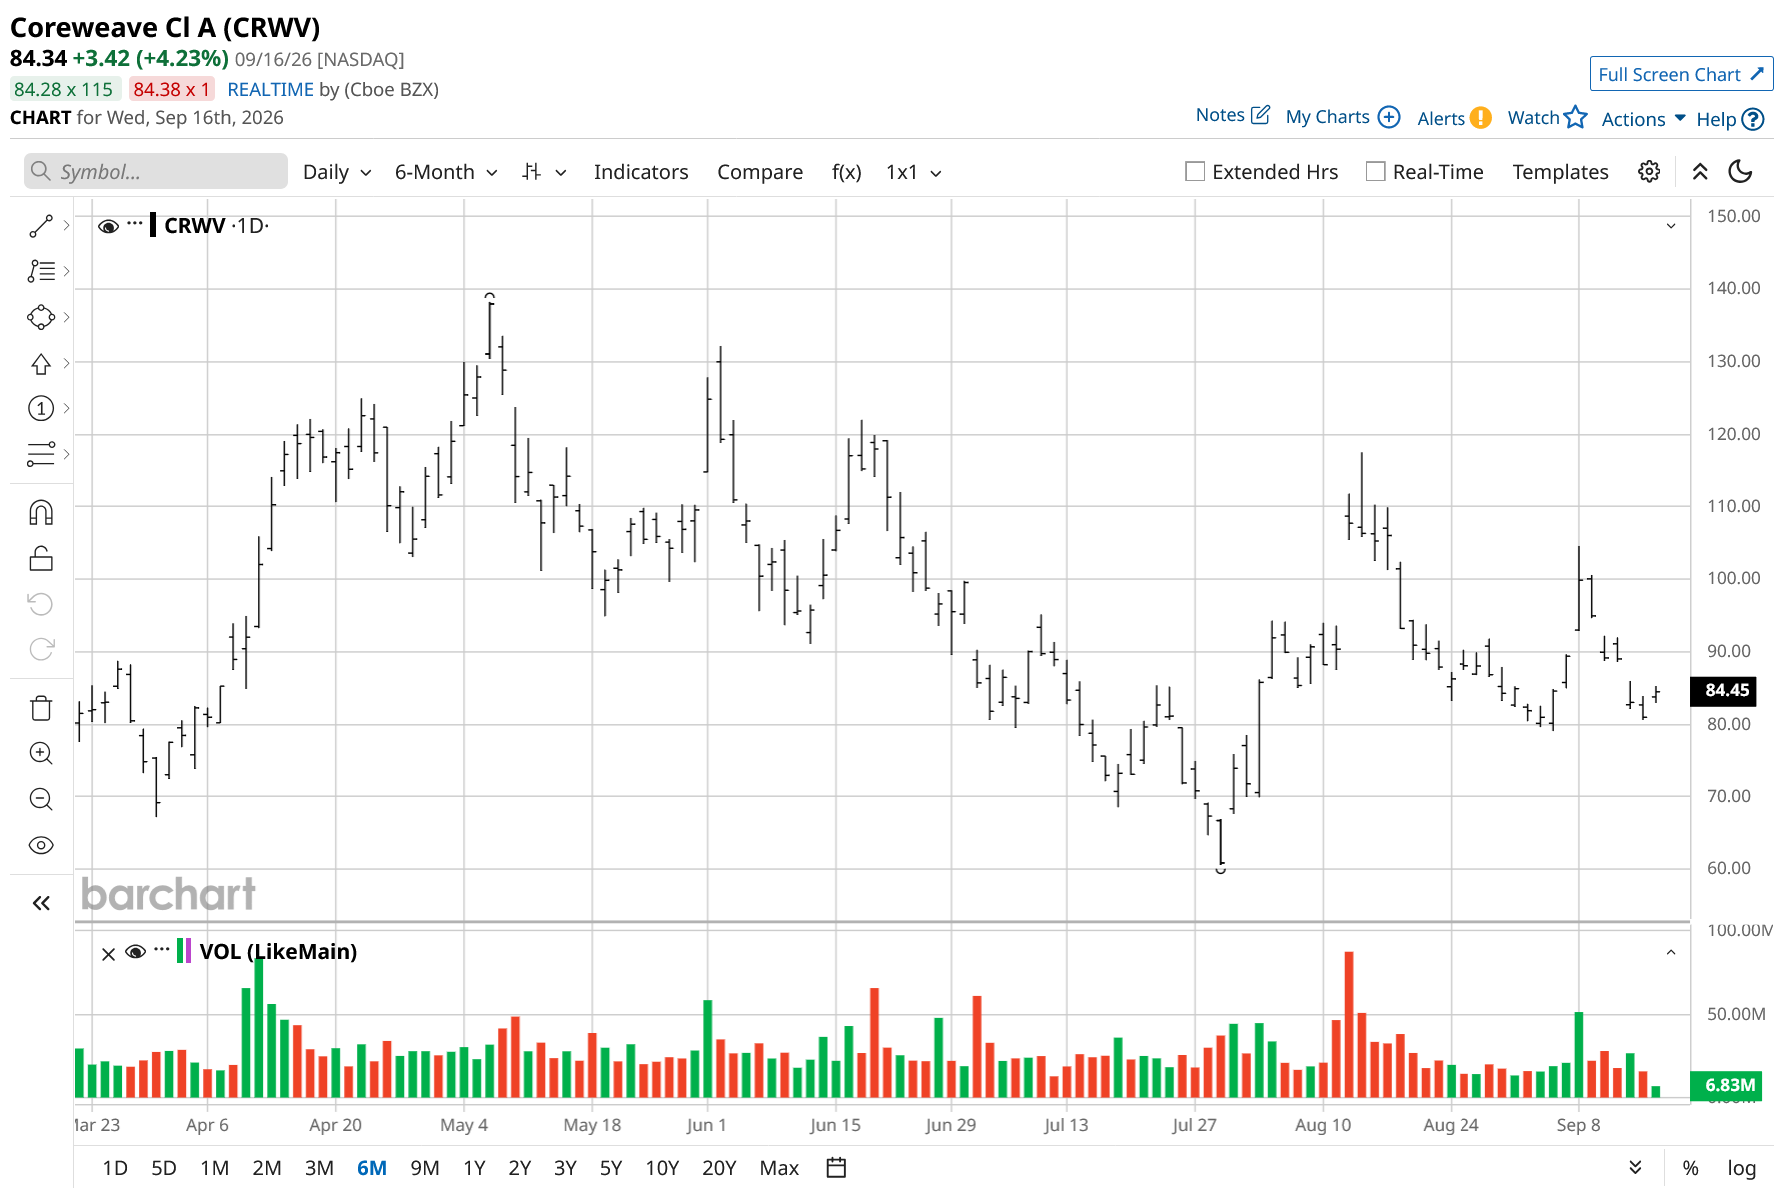
CoreWeave (CRWV), purely from the perspective of revenue growth, still looks attractive. However, CRWV stock is telling a different story. In the past 52 weeks, the stock has corrected by 29%.
Amidst this weak performance, Bernstein issued a warning. That “slowdown in the training of artificial intelligence models could negatively affect data center developers and neoclouds.” Further, CoreWeave is one of the “most exposed” to this risk.
Of course, this is not the only factor that’s concerning. For FY24, CoreWeave reported an adjusted EBITDA margin of 64%. There was a 400-basis-point compression in margin in FY25 to 60%. Further, for 1H FY26, adjusted EBITDA margin has declined to 57%. This compression in margin is another factor that has subdued CRWV stock.
The debt overhang also needs to be considered. As of Q2 FY26, CoreWeave reported total debt of $35.1 billion. As the debt swells, CoreWeave reported an interest expense of $1.2 billion for the first half of 2026. This implies an annualized debt servicing burden of $2.4 billion.
Therefore, considering the risk of slowdown coupled with stressed credit metrics, it seems prudent to stay on the sidelines.
About CoreWeave Stock
Headquartered in Livingston, New Jersey, CoreWeave is a cloud infrastructure technology company. The company’s CoreWeave Cloud platform enables the full lifecycle of AI, including large-scale model training, inference, data movement, continuous iteration, and agentic workflows.
CoreWeave delivers its cloud services through Infrastructure Services, Managed Software Services, and Application Software Services (including proprietary storage solutions, CoreWeave Mission Control).
In the last few years, CoreWeave has scaled rapidly. To put things into perspective, as of December 2023, the company operated 10 data centers with approximately 70 MW of active power. However, as of December 2025, the company operated 43 data centers with over 850 MW of active power.
This has translated into robust revenue growth. For FY25, CoreWeave reported revenue of $5.1 billion, which was higher by 168.4% on a year-over-year (YoY) basis. For the same period, the company’s adjusted EBITDA increased by 158.3% to $3.1 billion. Further, for the first half of 2026, CoreWeave reported revenue growth of 116.7% on a YoY basis to $2.6 billion.
However, even with robust top-line growth, CRWV stock has remained sideways in the past six months. The key factors weighing on the stock are leverage, margin compression, and a relative slowdown in industry growth.
Positives Amidst the Concerns
While the overall sentiment for CRWV stock is cautious, there are reasons to keep the company on the radar. CoreWeave has been pursuing aggressive growth and already has 51 active data centers. The total contracted power stands at 4.2 GW as of Aug. 11, 2026.
It’s also worth noting that the company’s revenue backlog has swelled by 264% on a YoY basis to $104.2 billion as of Q2 FY26. Additionally, CoreWeave has $25 billion in new customer commitments as of Q3. This adds to the revenue and growth visibility for the coming years.
For the first six months of FY26, CoreWeave reported a capital expenditure of $16.1 billion. Aggressive growth has been in sync with high levels of capex. As of Q2, the company had a cash buffer of $5.5 billion (excluding restricted cash). It, however, seems that further leveraging will be necessary for capital investments.
Overall, a strong backlog backs top-line growth visibility. Moreover, debt financing has supported the company’s ambitious expansion plans. Yet it remains to be seen if operating level margin expands meaningfully to support cash flow upside and possible deleveraging.
What Do Analysts Say About CRWV Stock?
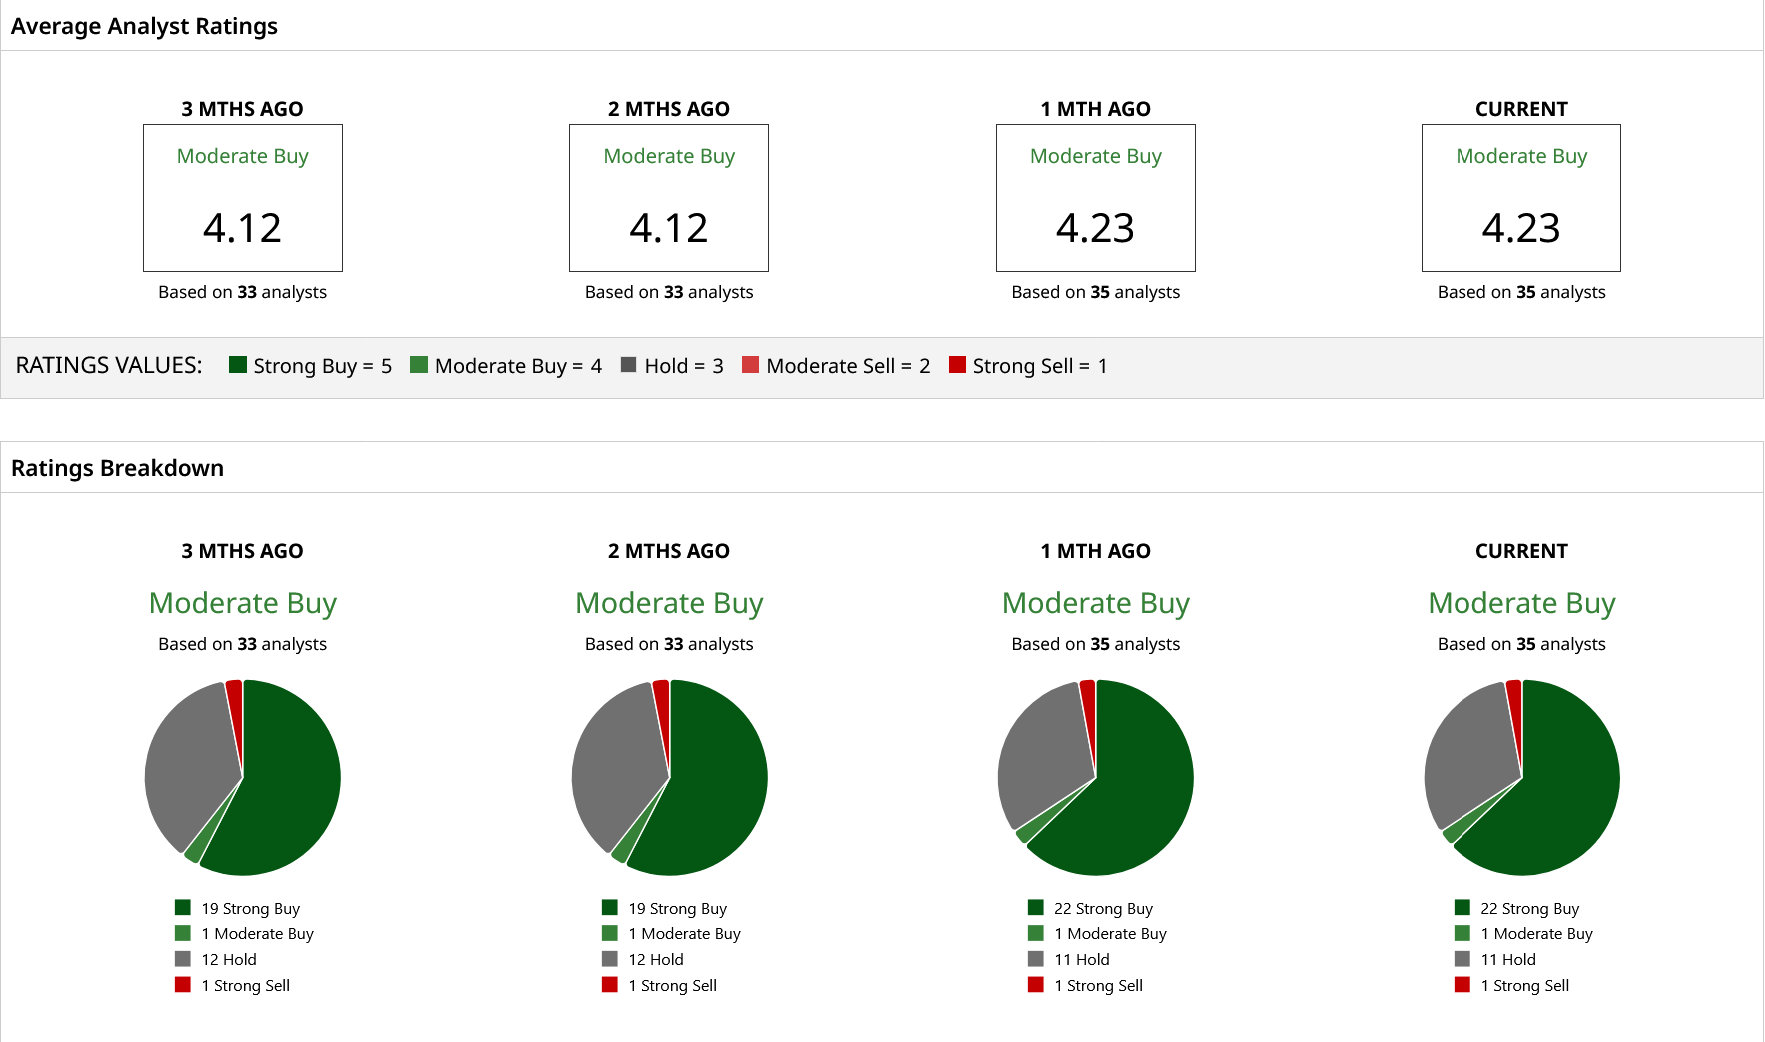
Based on 35 analysts with coverage, CRWV stock has a consensus “Moderate Buy” rating. While 22 analysts have a “Strong Buy” rating for the stock, one has a “Moderate Buy,” 11 have a “Hold,” and one analyst has a “Strong Sell” rating.
The mean price target of $140.30 represents potential upside of 66% from current levels. Further, the most bullish price target of $250 suggests that CRWV stock could climb as much as 196% from here.
On the date of publication, Faisal Humayun Khan did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.