
Should Dividend Payout Require Action From SPIE Stock Investors?
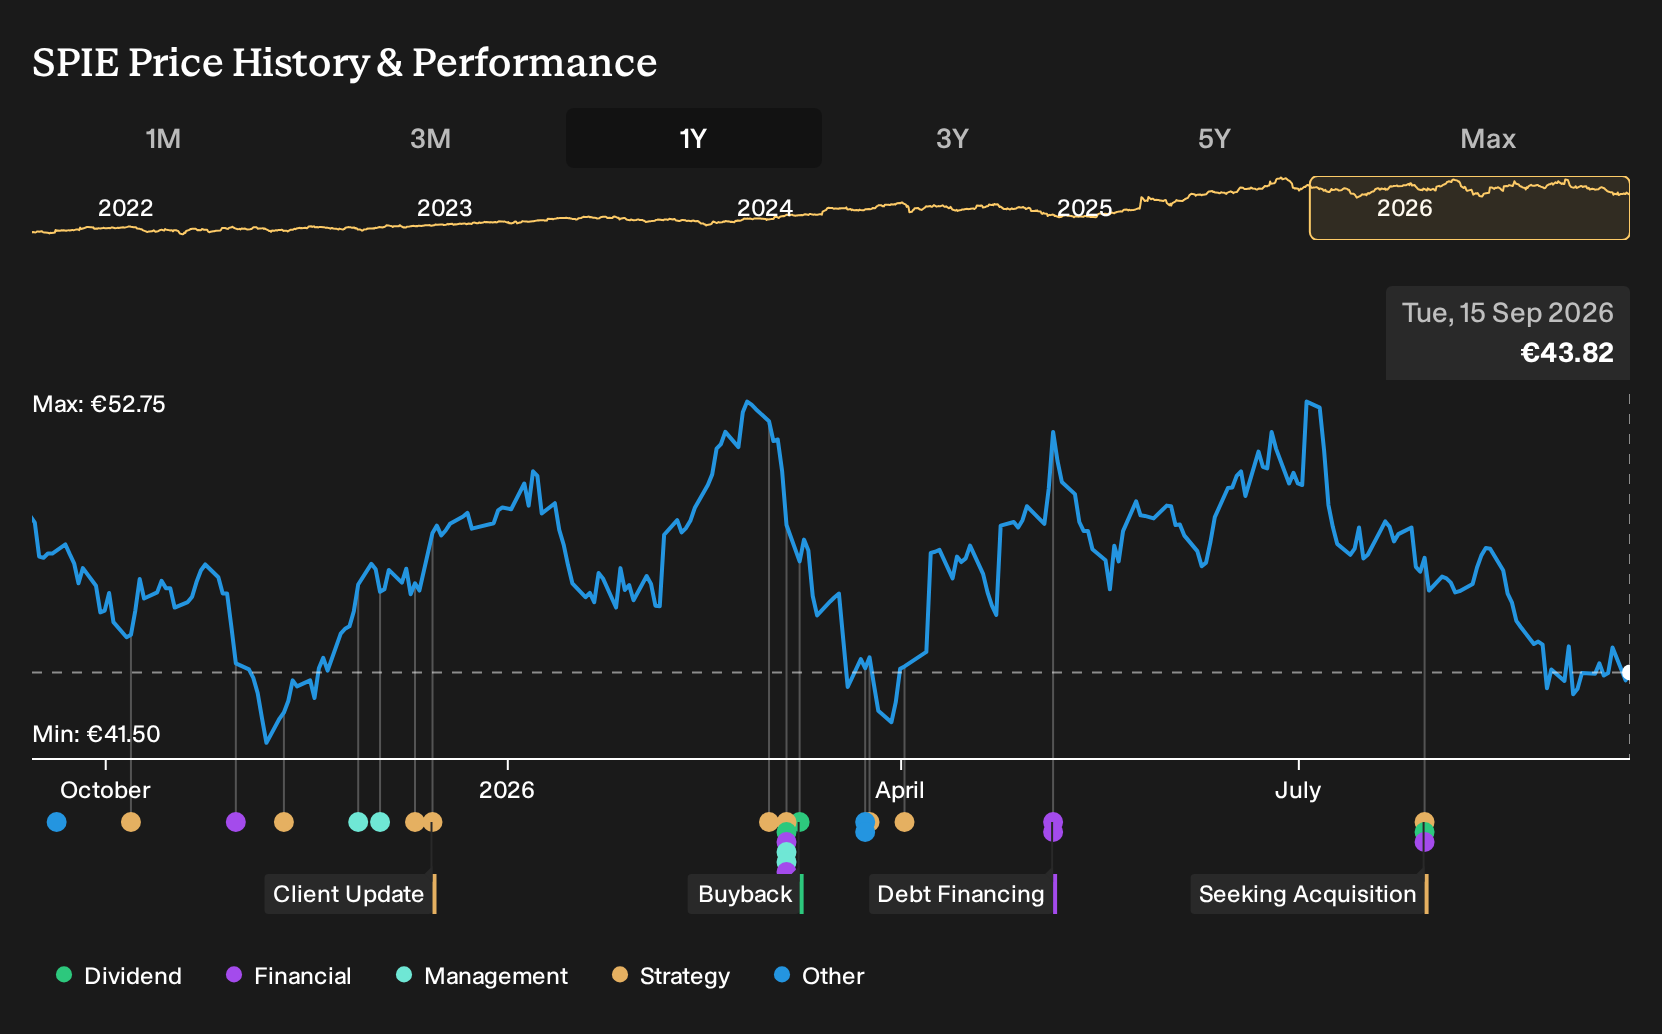
- SPIE recently paid a total dividend of $0.09 per share following the 16 September 2026 ex-dividend date, alongside operational updates in renewable energy management and digital education services.
- The combination of a 0.57 dividend payout ratio and fresh contracts in both energy and education services highlights how SPIE is balancing shareholder distributions with reinvestment in growing service lines.
- We will look at how SPIE's investment narrative is influenced by the dividend announcement and its expanding role in renewable energy.
Scan beyond SPIE and see how other infrastructure and services players with renewed income streams line up in our hand picked 162 dividend fortresses.
SPIE Investment Narrative Recap
To hold SPIE, you need to believe its mix of energy transition work, digital projects and technical services can keep turning a large European footprint into dependable cash generation. The latest $0.09 dividend and 0.57 payout ratio point to a company still prioritising reinvestment. The near term swing factor is execution on complex projects while managing wage pressure and regulation.
The sharp 8.5% share price decline over the past month and small rise in short interest keep sentiment fragile. That does not fundamentally change the core risk. SPIE remains heavily exposed to Europe and lumpy contract timing, so any delay or slowdown in major grid, data centre or industrial projects can quickly show up in earnings volatility.
The most relevant piece of recent news for this story is SPIE Energotest rolling out the ECONTROLoze platform for centralised management of photovoltaic assets at PVE Group. This is an operational proof point in renewables, directly tied to the company narrative around energy transition services and higher value, tech enabled maintenance work.
If SPIE can replicate ECONTROLoze style deployments across more clients, that could deepen its role in recurring energy management and support the main growth catalyst in grid, storage and renewables services. The flip side is execution complexity. Managing cybersecurity, regulation and performance guarantees across many sites raises operational risk, which could stress margins if projects are mispriced or delayed.
SPIE's analyst narrative points to revenues of €12.7b and earnings of €490.3m by 2029, based on an assumed 6.5% yearly top line growth and an earnings increase of roughly €314m from €176.4m today.
Uncover why SPIE's fair value indicates a 28% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view puts less weight on SPIE's energy transition pipeline and focuses on the risk of weaker industrial and public investment. The most cautious analysts were pencilling in revenues of about €12.8b and earnings of €465.0m by 2029 before this dividend and ECONTROLoze news, so their story is more muted. Use that gap as a prompt to explore several viewpoints.
Explore 3 other SPIE fair value estimates, including one that suggests it could be worth just €52.00.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your SPIE research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for SPIE. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate SPIE's overall financial health at a glance.
Looking For More Investment Ideas Beyond SPIE?
If the SPIE story has you thinking about portfolio balance, income, and resilience, it can help to line it up against a wider field of opportunities using the Simply Wall St Screener.
- For investors hunting for value with quality at the core, compare SPIE against a 195 high quality undervalued stocks that pair strong cash generation with disciplined balance sheets.
- If capital preservation ranks high on your checklist, scan a 102 resilient stocks with low risk scores to see which businesses score well on financial strength and earnings stability.
- When you want to widen the search beyond well known tickers, weigh SPIE against a 622 high quality undiscovered gems that combine solid fundamentals with lower market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com