
Distribuidora Internacional De Alimentación (BME:DIA) Following Strong Gains Looks Pricey On P E
Distribuidora Internacional de Alimentación (BME:DIA) has drawn fresh attention after recent performance data showed a 1 day return of 0.36%, with gains over the past week, month and past 3 months.
For context, Distribuidora Internacional de Alimentación’s recent upswing comes on top of a 9.04% year to date share price return and a 1 year total shareholder return of 67.07%. The 3 year total shareholder return has reached 208.15%, which points to momentum that has been building over a longer stretch rather than just a short term bounce.
Capitalize on Distribuidora Internacional de Alimentación’s recent momentum by scanning a curated 195 high quality undervalued stocks that share solid fundamentals and may be primed for the next leg higher.Distribuidora Internacional de Alimentación has delivered strong recent returns and growing revenues and net income. The real tension now is simple: Are investors paying a fair price for that progress, or too much?
Price-to-Earnings of 21.7x: Is it justified?
Valuation now gets tricky. Distribuidora Internacional de Alimentación swaps hands at €41.60, while recent data flags a P/E ratio of 21.7x that sits well above key comparison points.
The P/E multiple compares the current share price with earnings per share. For a retailer like Distribuidora Internacional de Alimentación, this yardstick often reflects how much investors are willing to pay today for each unit of profit, based on expectations for future earnings and business resilience.
DIA has moved from losses to profitability over the past 5 years, with earnings growth reported at 69.3% per year over that period and 102.2% over the last year. Forecasts also point to earnings growth of about 15.1% per year, quicker than the wider Spanish market, although revenue is expected to rise more slowly than both the local market and a 20% high growth threshold. The high reported 62.85% Return on Equity is described as skewed by leverage, and interest costs are not well covered, which suggests part of the richer P/E may be tied to optimism about future cash generation rather than a low risk balance sheet.
The gap to peers is clear. DIA is described as expensive on a P/E of 21.7x against a Spanish Consumer Retailing peer average of 14x, and also high compared to the wider European Consumer Retailing industry at 17.4x. That premium implies the market is already baking in stronger profit growth or sustained returns than the typical retailer, even though DIA’s revenue outlook is more modest than the domestic market.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 21.7x (OVERVALUED).
Still, the narrative around Distribuidora Internacional de Alimentación could shift quickly if high leverage strains interest coverage or if revenue growth of 4.8% slows further.
Find out about the key risks to this Distribuidora Internacional de Alimentación narrative.
Another View on Distribuidora Internacional de Alimentación’s Value
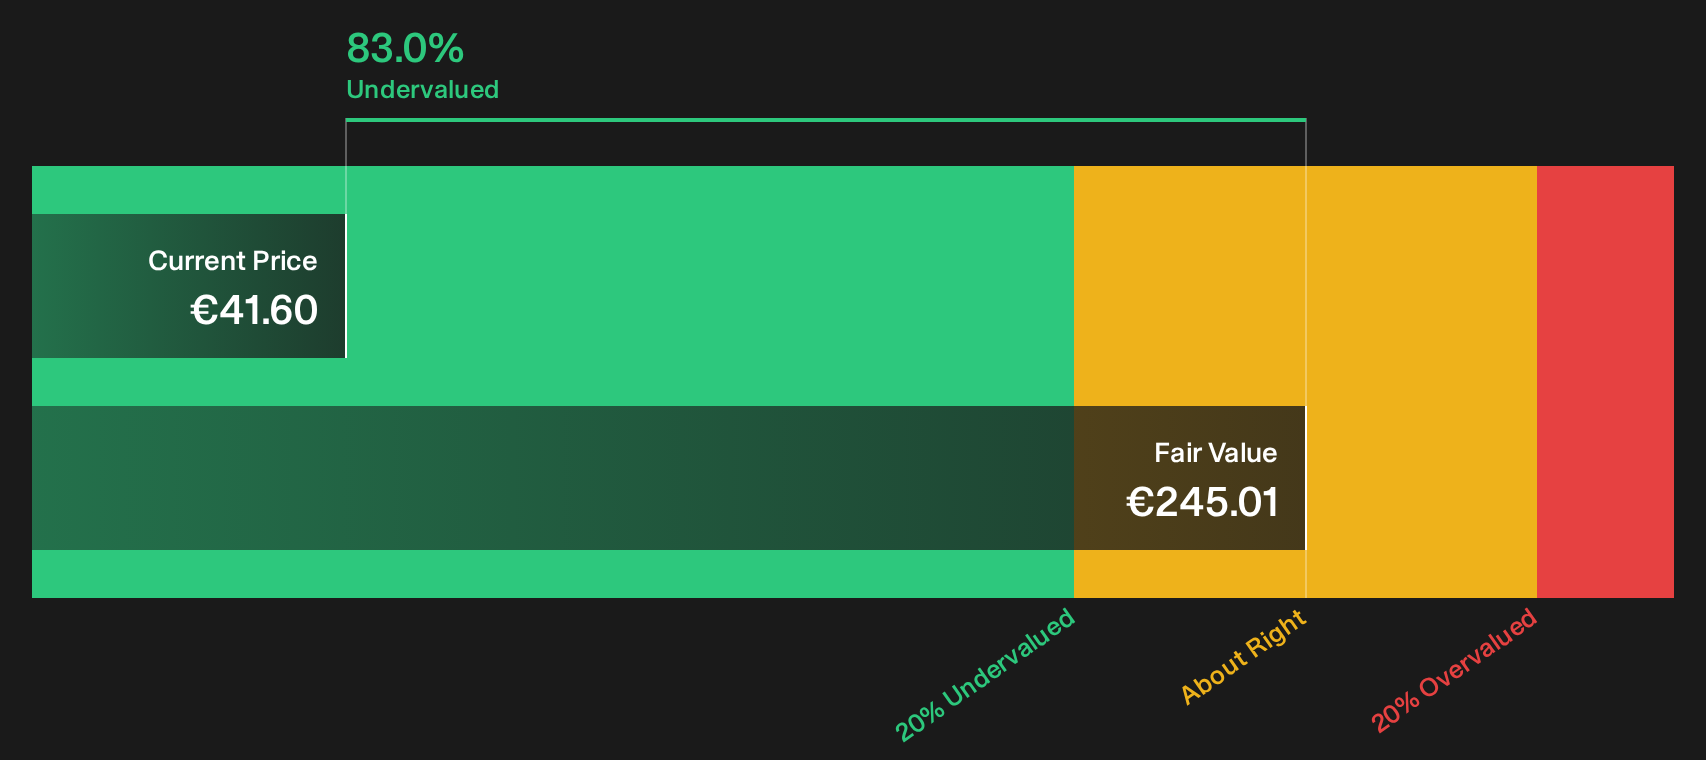
The P/E screen paints Distribuidora Internacional de Alimentación as expensive, while the SWS DCF model points the other way. At €41.60, the shares are described as trading well below an estimated future cash flow value of €245.01. On this method, the stock is framed as heavily undervalued. Which yardstick should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Distribuidora Internacional de Alimentación for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 195 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Big moves in Distribuidora Internacional de Alimentación can feel exciting, but the real edge comes from testing the numbers yourself and forming an independent view. Act while the data is fresh and weigh both sides of the story through 3 key rewards and 3 important warning signs
Looking for more ideas beyond Distribuidora Internacional de Alimentación?
If you stop with Distribuidora Internacional de Alimentación, you only see one angle. Scan other opportunities now so you are not reacting when others move first.
- Target stability and income by reviewing a shortlist of potential income plays screened as 160 dividend fortresses.
- Hunt for mispriced quality by scanning a focused 195 high quality undervalued stocks that may offer stronger fundamentals than the price implies.
- Prioritise resilience by checking a curated 102 resilient stocks with low risk scores that aims to limit downside while keeping upside on the table.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com