
Carpenter Technology (CRS) Stock Could Be 11% Undervalued On Stake Cut
Carpenter Technology has delivered a very long run in its share price over the past few years, and the recent pullback now puts the spotlight on a different issue. The question is whether the current valuation can still be explained by the cash flows the business is expected to generate.
- Over 5 years the stock has returned about 13x, which puts a lot of pressure on Carpenter Technology to keep producing cash flows that measure up to that kind of share price journey.
- The recent decision by Dan Loeb’s Third Point to cut its Carpenter Technology stake by 31% may prompt investors to reassess what future cash generation and capital needs look like for the metals producer.
- If you'd rather focus on earnings, this one's for you. See why Carpenter Technology's 38.9x P/E tells a different valuation story.
The issue now is whether today's Carpenter Technology share price is aligned with what its cash flows suggest the business is worth.
If you want to stress test the same cash flow questions you are asking of Carpenter Technology across a broader set of companies, scan through 34 high quality undervalued stocks.
Is Carpenter Technology a Bargain on Cash Flow?
The Discounted Cash Flow model here looks at how much cash Carpenter Technology might return to shareholders over time and then discounts those streams back to today. On the latest numbers, the business generated about $429 million of free cash flow over the last twelve months, which gives you a starting point that is already sizeable against its market value.
The projections used in this DCF assume that free cash flow continues growing from that base rather than shrinking, with the larger step-ups front loaded in the next few years before growth rates slow. Those stronger early years help explain why the Discounted Cash Flow projections put Carpenter Technology's estimated intrinsic value modestly above the current share price of $415.32. Because Dan Loeb’s Third Point has cut its stake so sharply, the decision highlights how different views on future cash generation can arise even when the DCF still suggests the stock trades a little below what those cash flows support. Find out what Carpenter Technology could be worth using our Discounted Cash Flow (DCF) estimate.
The Carpenter Technology Narrative: What Would Justify Today's Price?
Simply Wall St Narratives picks up where the Carpenter Technology valuation puzzle leaves off. It spells out which assumptions on growth, margins and earnings would need to hold for the stock to be worth materially more or less than today's price on the Community page. Each storyline links a specific fair value to a particular mix of potential catalysts and risks for Carpenter Technology, which gives you a way to track over time which version of the future is actually unfolding.
One of the top community narratives on Carpenter Technology: 23% undervalued
"This narrative explores a more pessimistic perspective on Carpenter Technology compared to the consensus, based on a Fair Value that aligns with the bearish cohort of analysts..."
Discover why this Narrative puts Carpenter Technology at 23% undervalued.
One more Carpenter Technology check that belongs next to the cash flow story
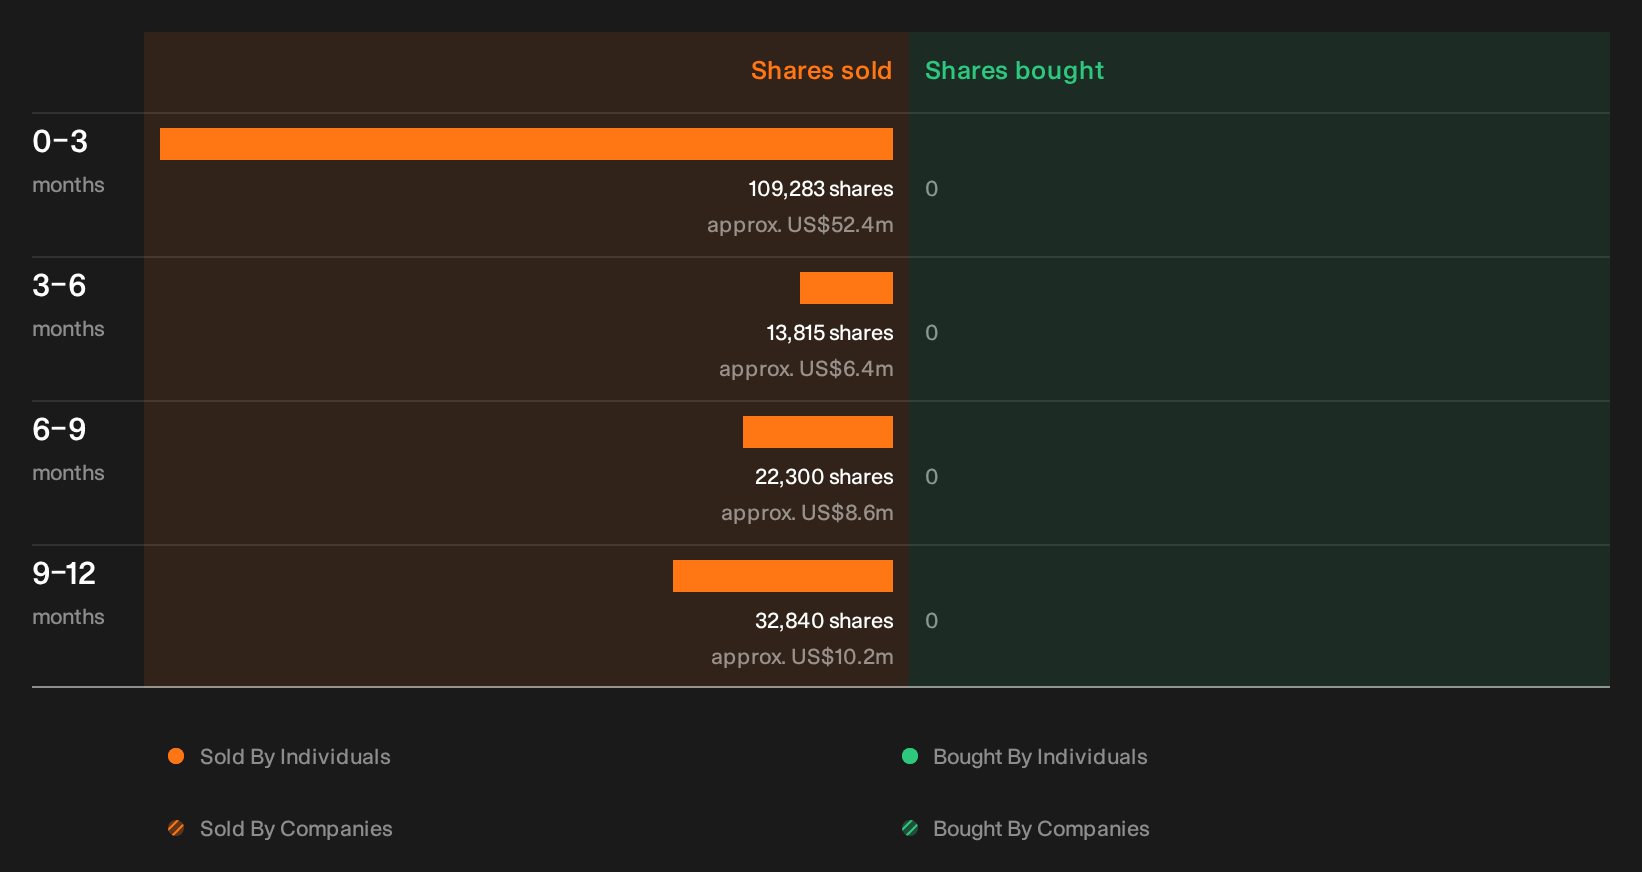
Carpenter Technology also has recent insider share sales flagged by our checks, and the who, how much and possible read through are all sitting in one place for you to review. See the recent insider selling flagged for Carpenter Technology.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com