
Turning Point Brands (TPB) Lands Matchroom Deal As Valuation Questions Grow
Turning Point Brands (TPB) is in focus after ALP Supply Co., one of its nicotine pouch businesses, secured exclusive nicotine pouch rights for Matchroom Boxing events across the UK and Ireland.
The Matchroom Boxing agreement lands at a tricky moment for Turning Point Brands investors, with the share price down 19.83% over the past 30 days and 36.48% year to date, even though the 3-year total shareholder return of 199.41% still points to a very strong longer-run outcome.
Scan how Turning Point Brands stacks up against other potential rebound candidates by running through the curated 34 high quality undervalued stocks that already meet strict quality and balance sheet filters.
Turning Point Brands now trades at a steep discount to analyst targets after a sharp slide in the share price. Is that gap mispricing fresh ALP momentum, or is it a fair warning signal about risk?
Most Popular Narrative: 46.1% Undervalued
On the widely followed narrative, Turning Point Brands screens well below its assessed $130 fair value, compared with the last close at $70.02, which puts the spotlight on whether Modern Oral and hemp products can carry the story.
Strong growth in the Modern Oral nicotine pouch segment, with sales growing nearly 8x year-over-year and now accounting for 26% of total revenue, positions TPB to capture significant market share in a category projected to reach $10 billion by decade's end. This will drive long-term revenue and margin expansion as the modern oral segment scales and premiumizes.
See why 7 investors see Turning Point Brands as 46% undervalued.
Result: Fair Value of $130 (UNDERVALUED)
Still, the whole Turning Point Brands narrative leans heavily on Modern Oral execution. Regulatory shifts or tougher competition are capable of quickly reshaping those optimism-fuelled assumptions.
Find out about the key risks to this Turning Point Brands narrative.
Another View On Turning Point Brands Valuation
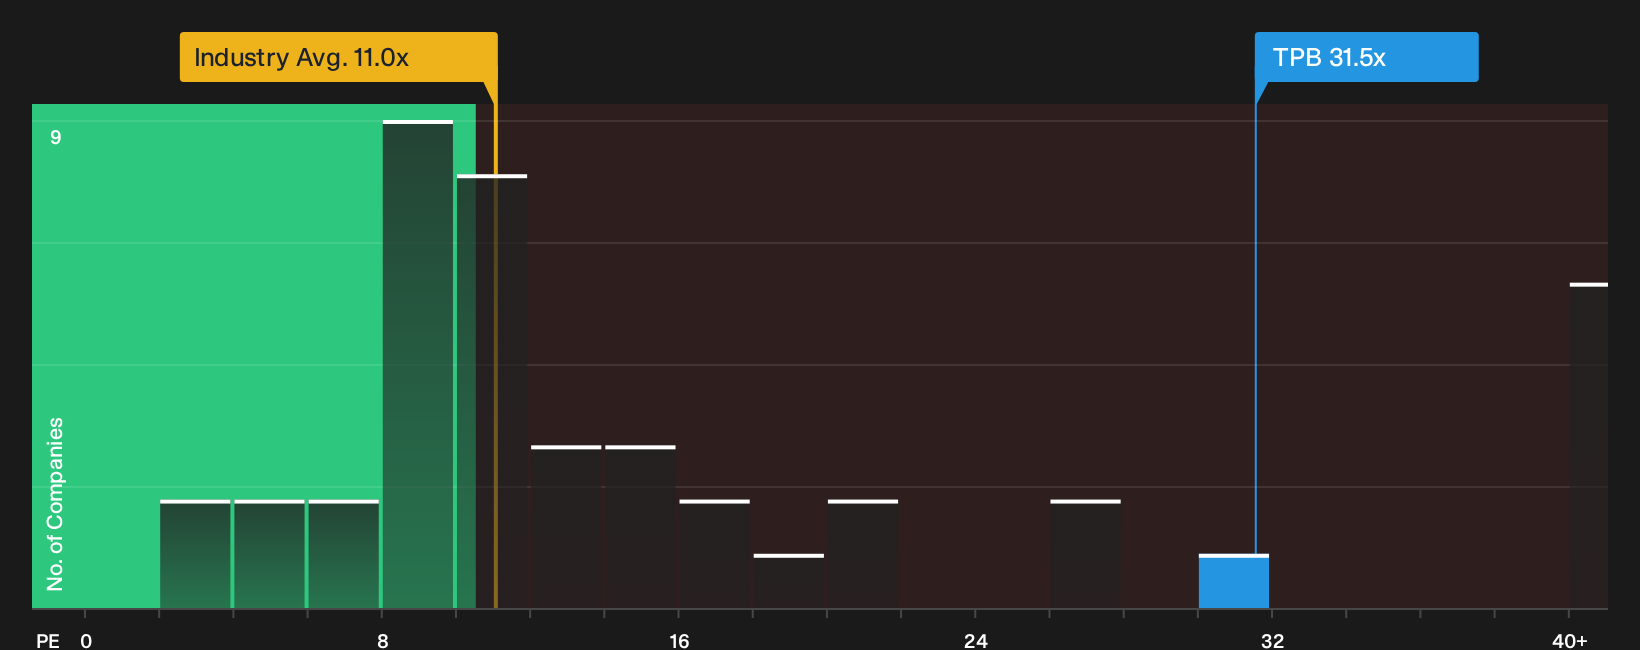
The fair value story for Turning Point Brands looks very different when the focus shifts to the P/E ratio instead of that $130 target. TPB trades on 31.5x earnings, compared with 11.2x for the global tobacco group and 34.6x for close peers, while the fair ratio sits at 32.5x. That mix points to a richer price tag than the broader industry but one that is closer to peer and fair ratio levels. This raises a simple question: Is the higher multiple reasonable compensation for growth expectations, or a margin of error that could shrink if sentiment cools?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Turning Point Brands valuation and risk can feel messy, so move quickly, test the numbers yourself, and weigh both the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Turning Point Brands?
Do not stop your research with Turning Point Brands. Fresh opportunities often show up where capital has not fully paid attention yet, and that is where a screener helps.
- Scan for income-focused opportunities and see which companies qualify as 6 dividend fortresses with payouts that may better match your cash flow goals.
- Hunt for sturdier balance sheets by reviewing the list of solid balance sheet and fundamentals (22 results) to spot businesses that may handle shocks more comfortably than highly leveraged peers.
- Zero in on potential mispriced ideas and use the 16 high quality undiscovered gems that might not yet be crowded with short term traders.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com