
Apotex Health (TSX:APTX) Stock May Trade At A Premium As Its Secondary Offering Grows
Apotex Health has delivered a strong year to date gain, yet the recent secondary share offering and shifting sentiment now put a spotlight on whether the current stock price lines up with what its sales can support. With the shares recently changing hands close to the bought deal offer price, investors are starting to ask how much of the business’s revenue story is already embedded in that valuation.
- The stock is up 23.2% year to date, which raises the question of how much of Apotex Health’s sales profile is already reflected in that move.
- The upsized bought deal secondary offering at $34.00 per share may influence how the market weighs future growth in Apotex Health’s product sales against existing shareholder supply.
- There is a second opinion on Apotex Health worth weighing. See what analysts think Apotex Health's shares could be worth.
For investors, the debate is whether Apotex Health’s recent share price level is adequately supported by its current sales when set against the industry average.
If you want to see how Apotex Health compares with other businesses where valuation is anchored on fundamentals, you can line it up against the companies in the solid balance sheet and fundamentals stocks screener (7 results).
Does Apotex Health Look Pricey on Sales?
P/S suits Apotex Health because revenue is a cleaner yardstick than earnings while the business invests and its P/E is distorted.
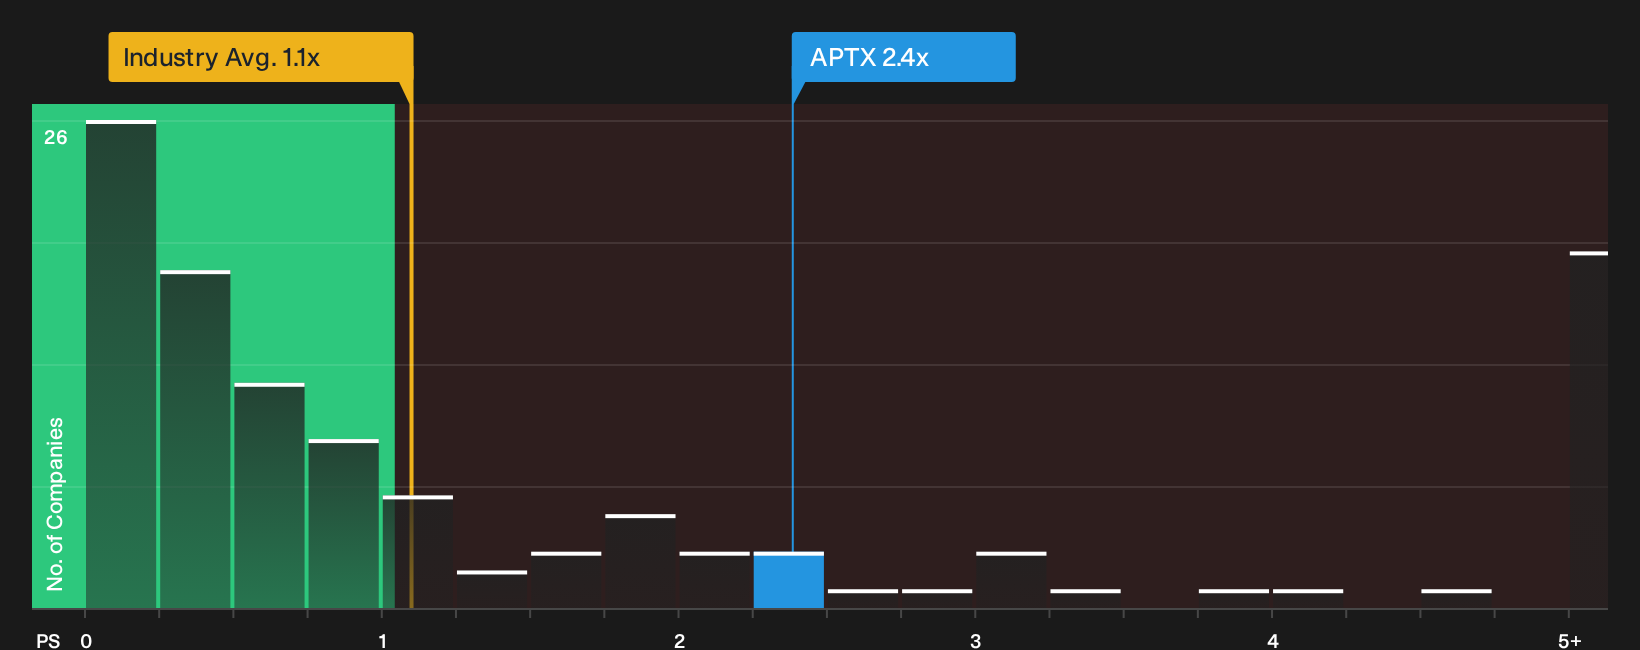
At a P/S of 2.4x, Apotex Health trades above the Pharmaceuticals industry average of about 1.1x but below the peer group at roughly 2.9x. The stock screens overvalued against the broader sector on this metric, since investors are paying a richer price for each dollar of Apotex Health’s sales than they would for the typical listed drug manufacturer.
Because the recent upsized bought deal secondary offering lifted free float without sending the P/S ratio meaningfully below peers, the current tag still reflects a full revenue multiple relative to the space. Anyone weighing this stock now needs to decide whether Apotex Health’s product mix and pipeline justify paying closer to peer pricing than the sector at large. Explore the numbers behind Apotex Health's P/S valuation.
The Apotex Health Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/S conversation leaves off for Apotex Health by spelling out which growth paths, margin shapes and earnings outcomes would need to play out for the stock to be worth materially more or less than it is today. Each scenario links its number to a clear view on how Apotex Health's future expansion, profitability profile and risk mix might evolve, which you can revisit on the Community page as new information comes through.
One of the top community narratives on Apotex Health: 19% undervalued
"A multi-year launch plan of more than 480 products, with an emphasis on first-to-market and differentiated generics in Canada and the U.S., positions Apotex Health to add new revenue streams…"
Discover why this Narrative puts Apotex Health at 19% undervalued.
One more Apotex Health check that belongs beside the price tag
Valuation only tells part of the story for Apotex Health, because Simply Wall St’s broader review has also highlighted specific risk checks that deserve your attention before you make up your mind. Take a closer look at 1 major warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com