
NextDecade (NEXT) Stock Looks Hard To Pin Down On Book Value
NextDecade has delivered a powerful run for long term holders, yet the current share price of US$7.15 now raises a sharper question about how much of the business is really backed by book value on the balance sheet. With that kind of move already in the rear-view mirror, the issue is whether the stock price still lines up with the accounting value of the assets funding the liquefied natural gas story.
- Over the past 5 years, NextDecade has returned 212.2%, which puts a lot of weight on whether the current market value can be supported by the equity recorded on its books.
- The company’s capital heavy model means investors are effectively funding large upfront project spending, so the relationship between that spend and the book value that builds up on the balance sheet can be critical to how the stock is judged.
- Your read on NextDecade is one view; the desks covering it have another. See what analysts think NextDecade's shares could be worth.
The stock’s next move may depend on whether that US$7.15 price still lines up with what NextDecade’s book value suggests the equity is worth.
If you are weighing whether NextDecade’s US$7.15 price really lines up with its book value, it can help to compare it with other capital intensive plays using the 34 high quality undervalued stocks
Where Does NextDecade Sit on Book Value?
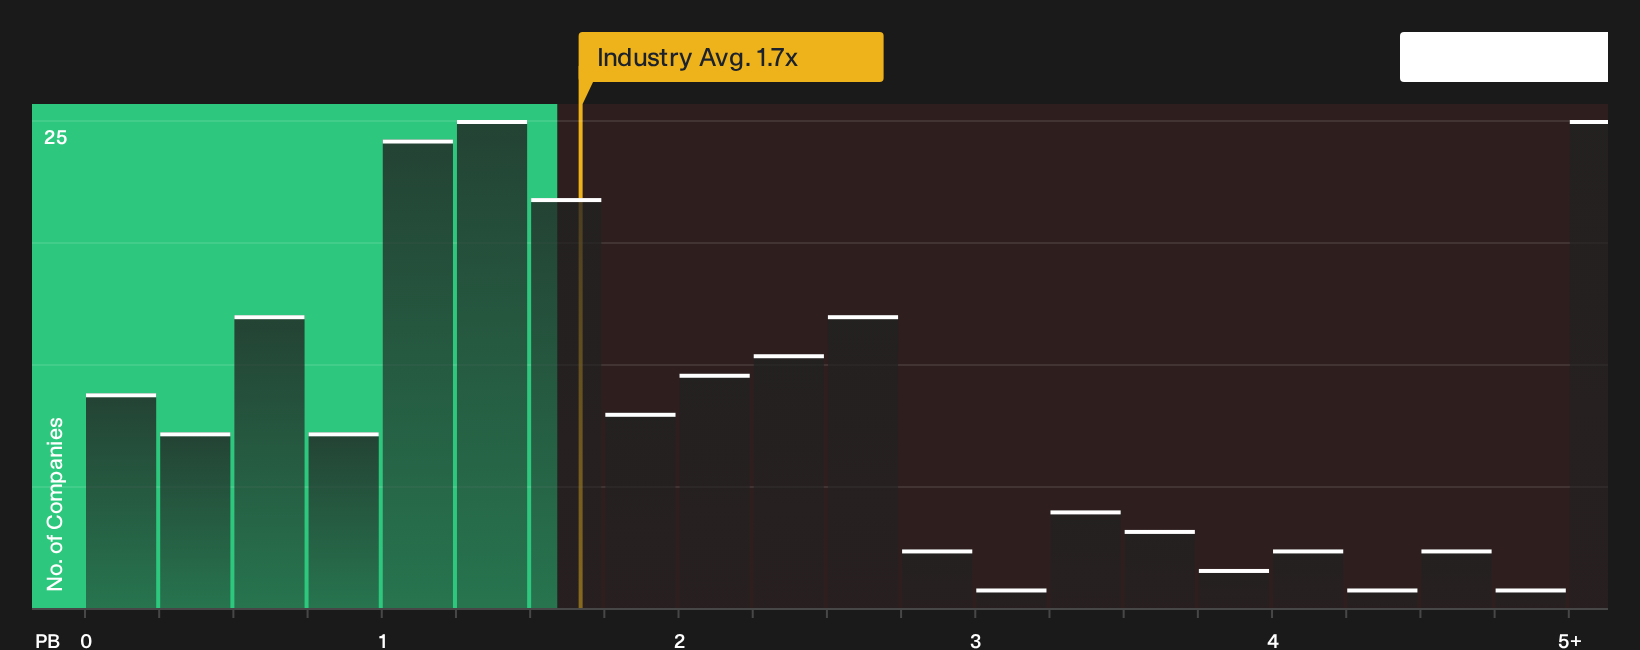
For a capital heavy LNG developer like NextDecade, the P/B ratio can give a quick sense of how the market is treating the balance sheet. Here that shortcut breaks down. The stock is trading on a P/B of -33.2x, which reflects that shareholder equity is negative, so there is no positive book value for the share price to be measured against.
A negative P/B like this does not indicate that NextDecade is cheap or expensive relative to its assets. It simply flags that past funding and accounting decisions have left the company with an equity deficit. For you as a holder or potential buyer, that means the current US$7.15 price is being anchored more by expectations around future LNG cash flows, funding access and project execution than by the reported book value on the balance sheet. With this multiple ruled out, take a closer look at what NextDecade's balance sheet and debt position show instead.
The NextDecade Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where this valuation puzzle around NextDecade leaves off. They spell out which assumptions on growth, margins and earnings would need to hold for the shares to be worth materially more or less than today, and each one turns that fair value view into a clear thesis about the business that you can watch play out over time on the Community page.
Community views on NextDecade are split between those who see more upside left in the LNG build out and those who think expectations already bake in the key wins.
Bull case: 35% undervalued
"Large scale LNG capacity under construction at Rio Grande, with 30 million tonnes per annum across Trains 1 through 5 and long-term SPAs that include approximately US$3b of annual fixed fee cash flow before escalation, sets up a substantial contracted revenue base that can support distributable cash flow visibility and earnings stability..."
Discover why this Narrative puts NextDecade at 35% undervalued.
Bear case: roughly fairly valued
"Reliance on early LNG cargo margins of US$3 to US$5 per MMBtu to help repay term loans and move toward a 3 to 3.5x debt to adjusted EBITDA target leaves limited room for weaker pricing or operational hiccups..."
Explore why this Narrative puts NextDecade at roughly fairly valued.
One more piece of the NextDecade puzzle before you move on
Big LNG projects live or die on the judgment of the people steering them, and how those leaders are rewarded can heavily influence the risks you are really taking. See who runs NextDecade and how they are paid.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com