
CONMED (CNMD) Stock Looks Reasonable After Its 62% Five Year Fall
CONMED has delivered a mixed ride for shareholders, with the stock changing hands at US$46.95 after a period where the share price has fallen sharply over several years but moved up over shorter stretches. That uneven path puts the spotlight on a simple question for investors who care about fundamentals: Is today’s price properly backed by the company’s earnings power?
- Over the past 5 years, CONMED’s share price has declined 61.7%, which puts a lot of focus on whether the current earnings justify where the market now values the business.
- The medical device group’s ability to turn its procedures and equipment sales into consistent profits and cash flow can shape how much confidence you place in the sustainability of its current valuation.
- Your read on CONMED is one view; the desks covering it have another. See what analysts think CONMED's shares could be worth.
The stock’s next move may depend on whether CONMED’s present earnings profile, and what it suggests about future profitability, is enough to support the price investors are paying today.
If you are weighing CONMED’s earnings against its current share price, it can help to compare that trade off with companies screened for 34 high quality undervalued stocks.
Does CONMED Look Undervalued on Earnings?
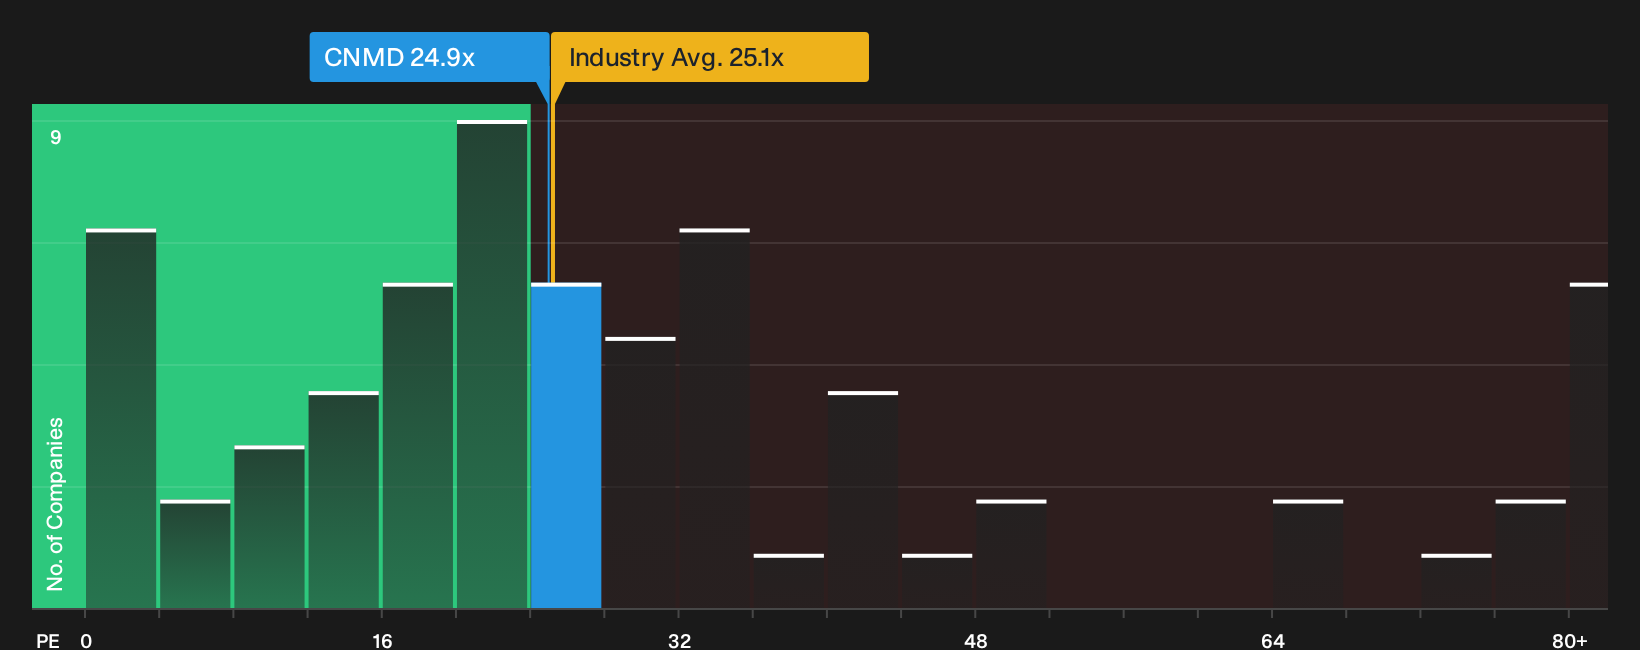
The P/E ratio fits CONMED because earnings remain the main yardstick investors use for medical equipment groups. At roughly 24.9x, CONMED’s P/E sits just under the broader medical equipment industry average of about 25.1x and below the peer group on roughly 31.9x. That means the market is valuing each dollar of CONMED’s profits at a lower level than many directly comparable businesses.
The Fair Ratio model, which blends factors like sector, profitability profile, scale and risk, points to a higher P/E than where the stock trades today. Since the current multiple is below that tailored yardstick, the price implies a discount relative to what this framework suggests for CONMED’s earnings power. For anyone weighing whether that gap reflects caution or an opportunity, it becomes important to test whether the company’s future profitability can support even the current P/E. Explore the numbers behind CONMED's P/E valuation.
The CONMED Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St’s Community page pick up where this valuation puzzle leaves off by spelling out which assumptions about CONMED's future growth, margins and earnings would need to hold for the stock to be worth meaningfully more or less than it is today. Each narrative treats fair value as a thesis about how CONMED's business might play out over time that you can revisit as new information arrives, rather than a single frozen snapshot.
CONMED draws two very different readings from the community, with one camp seeing enough in the story to call the stock roughly fairly valued while the other argues it is 9% overvalued.
Bull case: roughly fairly valued
"The company’s focus on minimally invasive solutions like BioBrace, AirSeal, and advanced smoke evacuation systems positions it to benefit from the ongoing migration of surgeries toward less invasive approaches…"
Discover why this Narrative puts CONMED at roughly fairly valued.
Bear case: 9% overvalued
"Rising global healthcare cost controls and looming reimbursement cuts are expected to limit hospital capital expenditures, which could dampen demand for elective surgical equipment and slow top-line revenue growth for CONMED over the long term…"
Explore why this Narrative puts CONMED at 9% overvalued.
One more piece of the CONMED puzzle is still off the page
You have a sense of what today’s P/E implies for CONMED, but professional coverage also sketches out where revenue, margins and earnings might land a few years from now. Explore where analysts expect CONMED to be in a few years.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com