
Bombardier (TSX:BBD.B) Stock Could Trade Below Fair Value After Political Risk
Bombardier has delivered a powerful share-price run over the past few years, which now sits against sharp short term pullbacks and rising political scrutiny. That mix puts the focus squarely on one question for investors who follow the stock closely: whether the current price is still supported by the earnings the business is generating.
- Over the past 5 years the share price has produced a very large gain, which raises the stakes on whether underlying profits justify where the stock now trades.
- Fresh headlines around potential restrictions on selling jets into the U.S. market, along with approvals for high end aircraft access to London City Airport, can shape expectations for future earnings resilience and potential margin strength.
- There is a second opinion on Bombardier worth weighing. See what analysts think Bombardier's shares could be worth.
The stock's next move may depend on whether Bombardier's current earnings profile is strong enough to support the valuation investors are paying today.
If you are weighing Bombardier's sharp 5 year share gain against political risk and earnings support, it can help to compare it with 3 high quality undervalued stocks.
Is Bombardier a Bargain on Earnings?
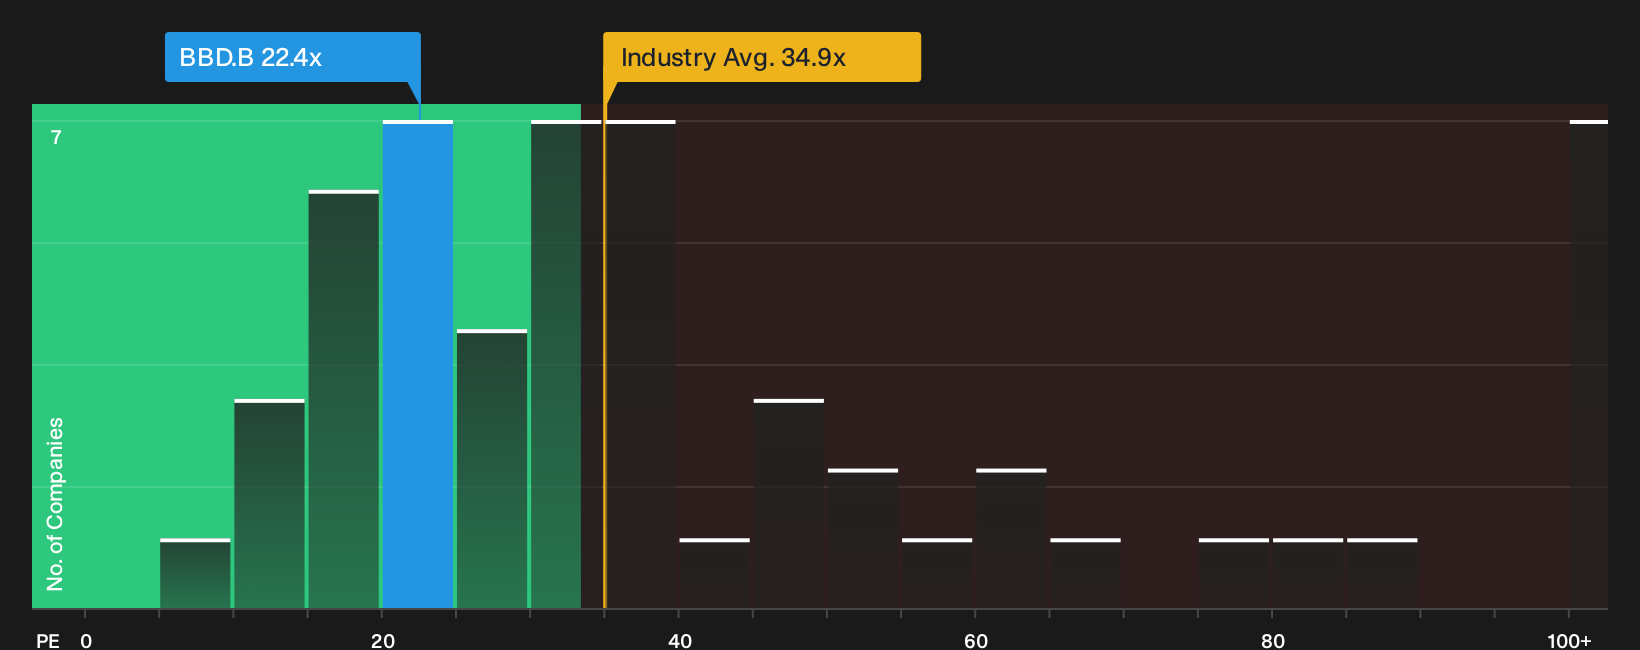
P/E fits Bombardier because the market is clearly paying attention to the earnings power behind its business jet franchise. The stock trades on a P/E of about 22.4x, which is well below the Aerospace & Defense industry average of roughly 40.6x and also under the peer group level near 39.2x. Against a basket of similar companies, investors are paying a lower price for each dollar of Bombardier's reported profit.
The fair multiple implied by a more tailored model that factors in Bombardier's margins, risk profile and scale sits above the current P/E. This points to the shares screening as undervalued on this yardstick. Because the recent threat of restrictions on U.S. jet sales has pulled political risk into focus, the fact that the P/E still sits at a discount to both peers and that tailored benchmark matters for anyone weighing whether the news flow is already reflected in the price. Explore the numbers behind Bombardier's P/E valuation.
The Bombardier Narrative: What Would Justify Today's Price?
Bombardier's valuation puzzle raises a simple follow up question for you as a shareholder or potential buyer. Narratives on Simply Wall St's Community page spell out the specific combinations of future growth, margins and earnings power that would need to play out for the stock to be worth materially more or less than it is today. Where a single ratio or model produces one valuation figure, the narrative behind it shows the future it relies on so you can watch how that story unfolds over time.
Community views on Bombardier are split between those who see execution on services and defense as underappreciated and those who think concentration and regulation risks matter more.
Bull case: 14% undervalued
"Robust growth in Bombardier's services and aftermarket business, including expanded facilities and high utilization, points to a durable, high-margin recurring revenue stream..."
Discover why this Narrative puts Bombardier at 14% undervalued.
Bear case: 13% overvalued
"Heightened environmental regulation and global carbon reduction initiatives are expected to increasingly restrict private jet usage and sales worldwide, directly threatening Bombardier's future revenue growth..."
Explore why this Narrative puts Bombardier at 13% overvalued.
One more Bombardier check that belongs beside the valuation story
Price multiples only tell part of the story for Bombardier. Separate research checks have highlighted specific risk signals that deserve your attention before you lean on the numbers. Take a closer look at 4 warning signs (1 major) before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com